Coffee Drops Amid Expectations of a Significant Global Surplus by 2026
- Bullish
- Oil continues to pressure the commodities complex;
- Smaller harvest and sales restrictions strengthen arabica coffee differentials in Brazil in the short term;
- Stocks remain low in Europe and Japan.
- Bearish
- Global surplus expected for the 2026 harvest;
- Record harvest projections in Brazil;
- Positive crop development and stable weather in Brazil;
- Optimistic projections for Vietnam and Indonesia volumes in 2025/26;
Coffee Falls as Brazil's Harvest Nears, Despite Short-Term Restrictions and Tight Global Stocks
Last week saw the continuation of the corrective movement in coffee futures prices, driven by the anticipation of a robust harvest in Brazil. Though certain short-term bullish factors persist—such as historically low stock levels in Europe and Japan and uncertainties surrounding the Middle East conflict—the market has largely focused on the outlook for increased global availability, particularly with Brazil’s harvest approaching.
Arabica: The May contract closed the week at US¢ 295.4/lb on the New York exchange, down 2%. Prices remained under pressure as more optimistic forecasts for Brazil’s 2026/27 harvest solidified. The imminent start of the harvest, expected to ramp up between late April and May, also reinforced the seasonal pattern of weakening prices as the market anticipates greater physical supply.
- Despite the bearish trend, the price decline has been gradual, with funds slowly reducing long positions without signs of abrupt liquidation.
- Additionally, the moderate pace of sales from Brazilian producers, influenced by the recent appreciation of the real, has helped limit more significant downward pressure on prices.
- Certified stocks have seen slight replenishment in recent weeks but remain historically low, limiting the scope for sharper price declines in the short term.
- The market is also awaiting export data from Cecafé, with partial figures indicating shipments of approximately 2.2 million bags in March—significantly below the three-year average of 3.3 million—which continues to support firm arabica differentials.
Robusta: The equivalent contract in London closed the week at US$ 3,448/ton, down 4.0%. Despite the more pronounced drop, prices remain relatively supported compared to arabica, reflecting the ongoing tightness in ICE-monitored stocks, which remain near recent lows. This situation has provided support for nearby contracts, even in a globally favorable supply scenario.
- Last week, this was further reinforced by data from Indonesia showing a sharp decline in robusta coffee exports from the Sumatra region, down 25.4% compared to the same period last year.
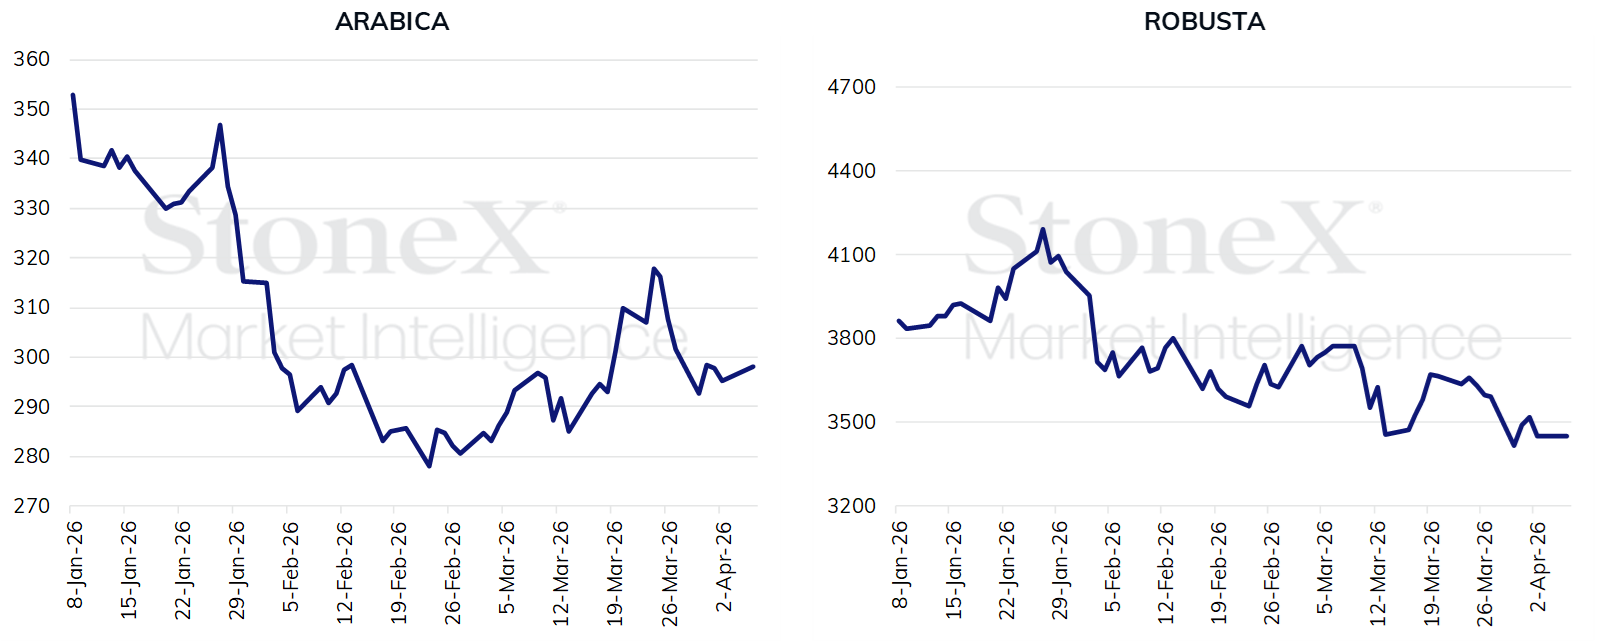
Source: CmdtyView. Prepared by: StoneX.
Physical Market: The Cepea arabica coffee indicator closed the week at R$ 1,870/bag, down 3.9% for the week. Meanwhile, the robusta coffee indicator registered a slight decline of 7.7%, closing at R$ 937/ton.
This Monday: The market started the session with a significant divergence between exchanges, extending recent sharp declines seen in London, with a 2.3% drop for robusta coffee and a 1% gain for arabica coffee.
StoneX Projects a 10-Million-Bag Surplus for the Global Coffee Balance in 2026
On Monday, we published for our clients a revision of our estimates for the global coffee supply and demand balance for 2025, along with projections for 2026.
- The full analysis, accessible via this link, provides a comprehensive review based on detailed data from key producing, exporting, and consuming regions, including specific mappings for Europe, the United States, Brazil, and Asian countries.
StoneX Projections: Our updated outlook suggests a more comfortable global balance in 2026, with production forecast to rise to 182.5 million bags and consumption recovering to 172.5 million bags.
- As a result, a surplus of 10 million bags is projected, which should allow stocks to recover from historically tight levels to above 48 million bags.
- For 2026, the stock-to-use ratio is projected to recover to 28.0%, the highest level since 2022, reflecting our expectation that the projected surplus for 2026 will significantly rebuild stocks.
Outlook: Despite the larger estimated surplus, it is unlikely that the market will feel "well-stocked" in the coming weeks.
- Even with Brazil's harvest starting, stocks may initially remain unevenly distributed, and normalization depends heavily on Brazil’s post-harvest productivity confirmation, as well as weather developments in other origins.
- On the demand side, easing inflation should support a gradual recovery, but consumers remain price-sensitive amid macroeconomic uncertainty.
- In a context of evolving regulations (including EUDR), trade policy risks, tariffs, and logistical concerns amid ongoing geopolitical tensions, 2026 is set to be a transitional year—where improved supply prospects reduce the risk of extreme events, but vigilance remains crucial as small shocks could still translate into volatility.
Potential Shift in Stock Distribution: Given this outlook, as previously noted, the stock-to-use ratio is expected to show recovery. However, this anticipated stock replenishment is likely to occur asymmetrically across the global supply chain.
- The current shape of futures curves, often inverted, combined with high international interest rates and the industry’s recent adjustment to operate with leaner stocks, discourages stock accumulation in consumer regions.
- In this context, replenishment is expected to focus primarily on origins, particularly Brazil, while consumer markets like the U.S. and Europe are likely to maintain relatively low levels in the short term.
- This unequal distribution suggests that, even in a global surplus scenario, perceptions of tightness may persist in certain parts of the supply chain, maintaining firm differentials and heightening price sensitivity to logistical disruptions or localized supply shocks.
Global Coffee Supply and Demand (millions of bags), Stocks, and Stock-to-Use Ratio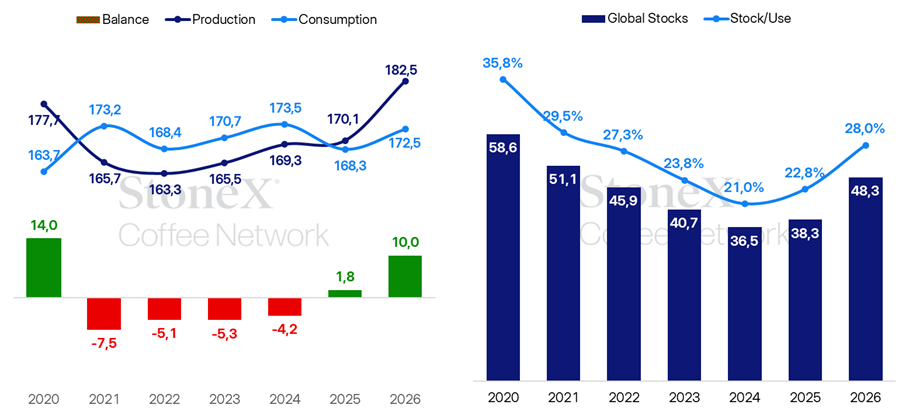
Sources: StoneX, USDA, ECF, and AJCA. Design: StoneX
Certified Stocks Remain Low in Japan and Europe
Data released last week reinforced the perception that green coffee stocks remain historically low in major consumer regions.
- In Japan, volumes remained close to 2.21 million bags in February, below the five-year average (2.75 million). In Europe, stocks fell to 6.8 million bags, showing both monthly and annual declines, and remain significantly below levels observed in 2022.
Colombian President Criticizes the National Federation of Coffee Growers
Recent statements by Colombian President Gustavo Petro have reignited debate about the dynamics of coffee production in the country.
- In his remarks, the president criticized the Federation’s handling of the recent production decline, which saw volumes drop from 13.5 million bags in the 2024/25 cycle to an estimated 12.6 million bags between October and December 2025.
- Petro also attributed part of the issue to the Federation's lack of structural studies, citing resistance to recognizing the impacts of the climate crisis.
- From a technical standpoint, however, the Federation presents a different view. It argues that the observed slowdown is largely due to cyclical factors, particularly the physiological exhaustion of crops following consecutive high-yield cycles and excessive rainfall since late 2025. This diagnosis suggests a temporary supply adjustment rather than a structural deterioration of Colombia’s production capacity.
In Detail: Within this context, the Federation believes Colombia remains relatively well-positioned in the medium and long terms.
- One key factor is the ongoing renewal of coffee plantations, which has been intensified since 2008. The modernization of crops, with widespread adoption of rust-resistant varieties better suited to climate variability, is expected to enhance production resilience over time.
- Furthermore, the development of new cultivars, set to launch in 2027, reinforces the country’s competitive position as a key supplier of washed arabica coffee in the global market.
- From a market perspective, the predominant view is that Colombia’s current production decline supports firm arabica differentials in the short term, particularly in an environment still marked by tight stocks in major consumer nations.
- Overall, there are few indications at present to justify structural long-term concerns about Colombian production. However, upcoming harvests will be crucial in determining whether the recent downturn is merely a temporary adjustment or could signal a more enduring shift in the country’s production trajectory.
INDICATOR TABLE
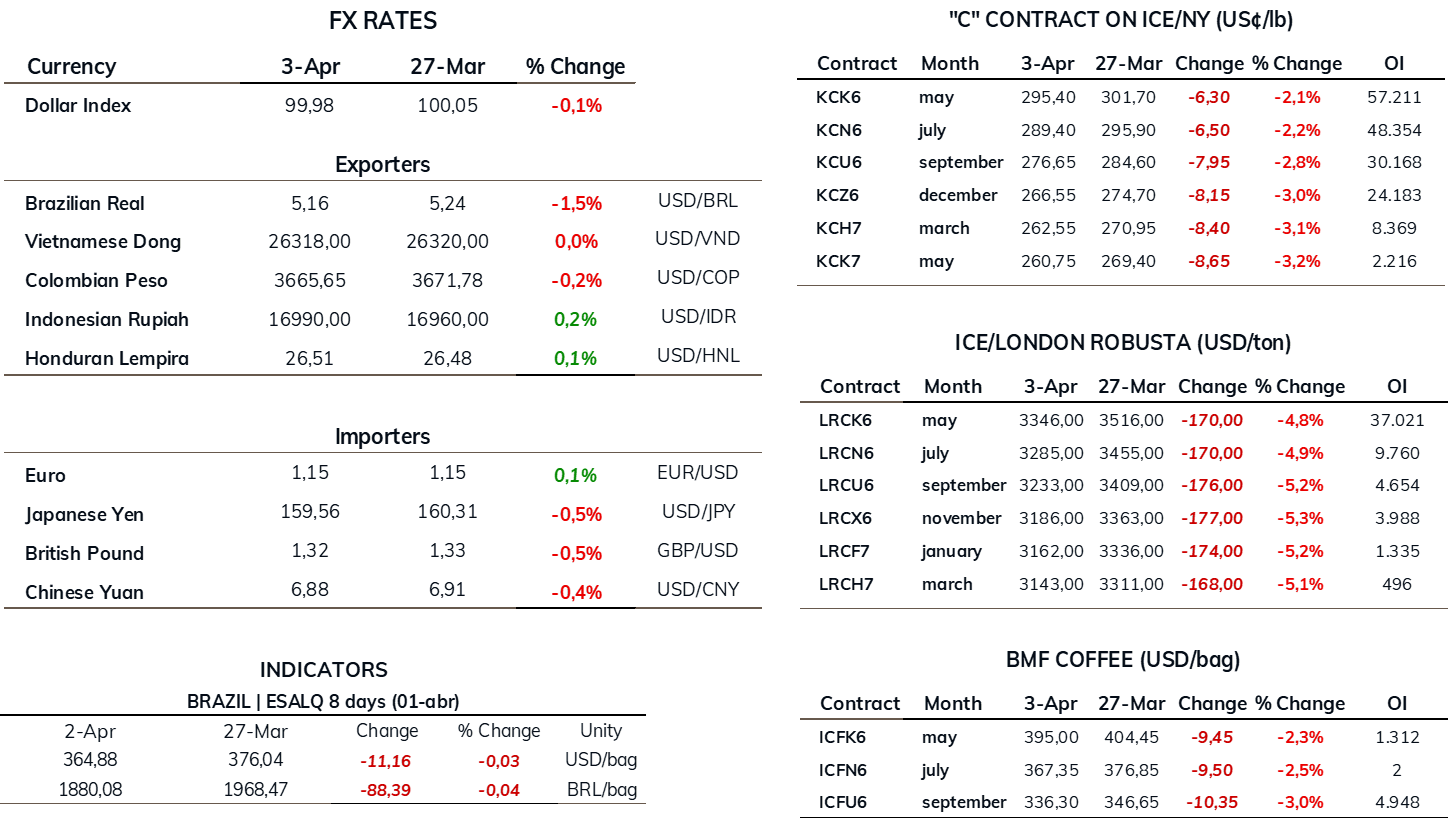
Sources: ICE/NY; ICE/EU; B3; Commodity Network Trader’s Pro.