October '25 POTASH
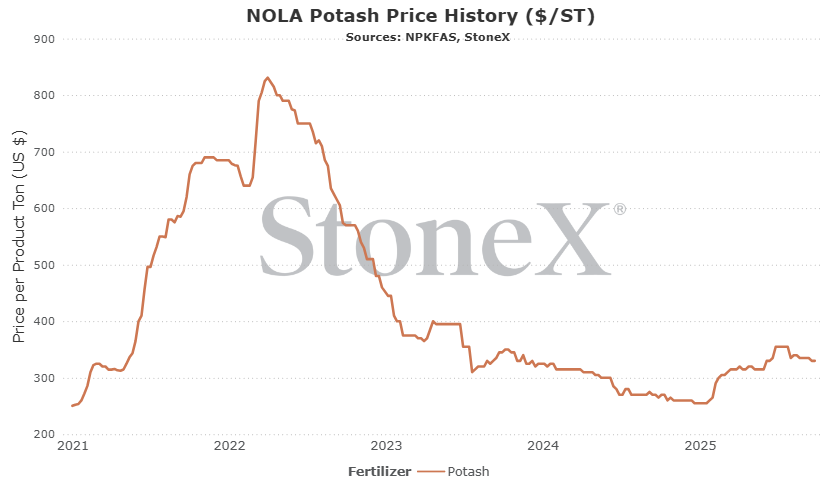
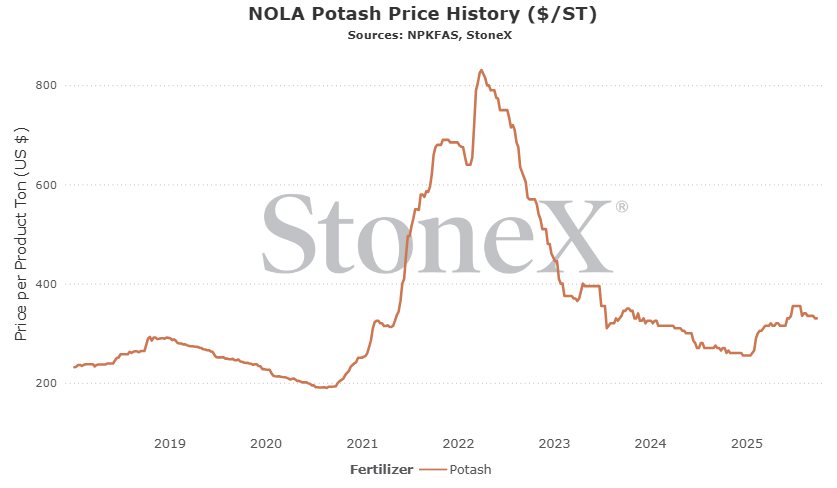
NOLA Potash Price Graph
Please remember that this is looking at the cost of one short ton of potash sitting in a barge at NOLA (New Orleans, Louisiana). Your cost is not going to be the same. This should be looked at more in regards to the price direction rather than the actual pricing.
What everyone wants to know first, what do we think will happen going forward
Global
Nothing has really changed on the global potash market front. Supplies continue to look solid, but manufacturers/exporters also appear comfortable. There just isn't anything to get excited about today.
The longer range forecast is still an even better supplied global market. Russia's expansions should happen if/when peace is found with Ukraine. China continues to invest in Laos. Belarus should return to normal one day. Canada continues on their path to ramp up product. Even the U.S. is sinking a lot of money into new potash production...for some damned reason.
All this to say that global potash looks fairly stable. If I have to pick a side, I would say very light lean to the bullish side short-term just with looming demand. Longer term I still lean bearish as global production gains continue to outpace global demand gains.
North America
If potash were viewed by itself across North America, one would be right to think that demand should be pretty good this fall. While the price itself is high historically, it is at least "in line" with grain values. That, coupled with a big harvest that should remove a lot of nutrients from the soil, should mean big fall demand. However, farmers do not look at potash alone a lot of times. They look at potash and phosphate together. That is where I get a little nervous.
Will farmers skip their phosphate application, and also skip their potash because they are not going to pay for 2 applications?
Will farmers reduce their phosphate spending and decide to invest more on potash to build those soil levels?
Will the fall play out normally, completely dismissing all the summer conversations?
Guess we will know in 60 - 90 days!!
Today, I still see potash values remaining flat as there is not much to get the market excited. However, do not be surprised if there is an in-season price jump as demand starts coming forward. Especially if the farm gate does not adhere to its demand destruction threats.
Overall, potash supplies are solid. Just might see some timing issues.
General Global Potash Information
What has happened in the last 30 days?
World watches sanctions threats against Russia
As with most fertilizer products excluding UAN, the probability of recent western threats of sanctions on Russia having an impact on Russia’s potash export flows are very low…but not zero.
As has been described over every product this month, the U.S. is trying to lead the charge on placing very heavy-handed sanctions on Russia due to their unwillingness to find peace with Ukraine. Personally, I was very hopeful after Putin and Trump held in person meetings in Alaska. I saw that as a major step forward. Those hopes were dashed. Not only has progress been stopped, but President Trump’s patience has run out and he is now trying to rally allies to put sanctions in place.
So why is it very unlikely that these sanctions will impact Russia’s potash export capabilities? It comes down to countries like Brazil, China, and India who have all shown a willingness to ignore anything that comes from the west.
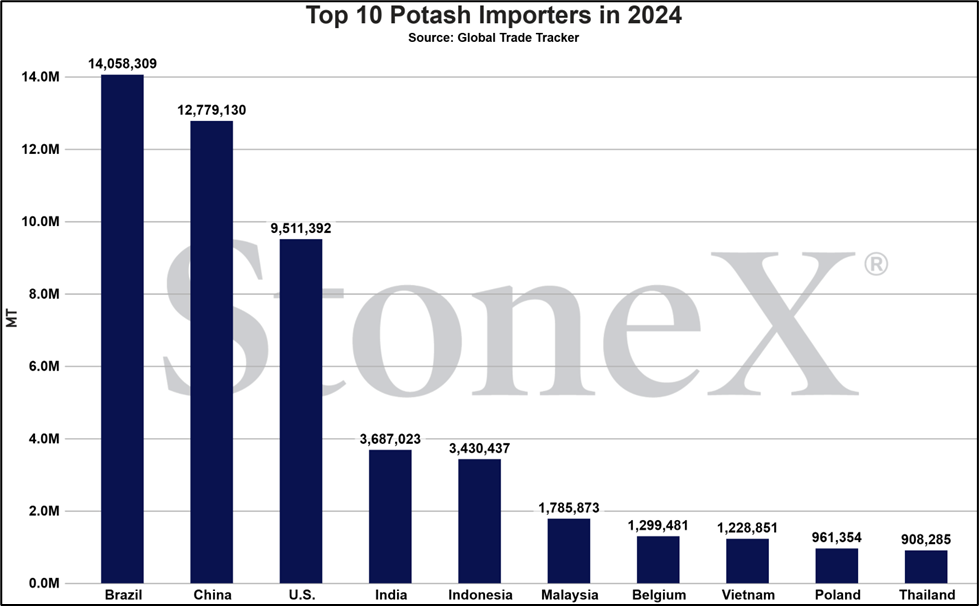
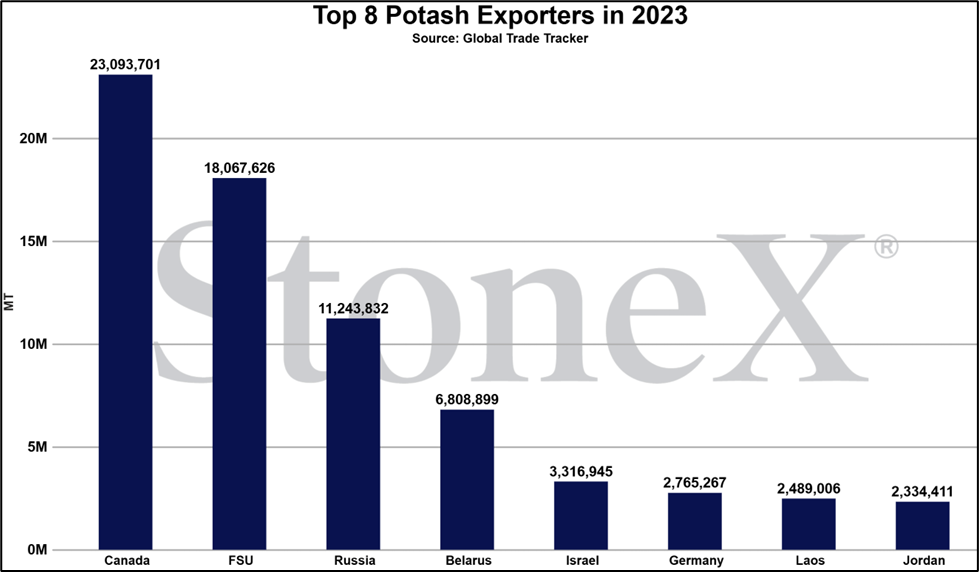
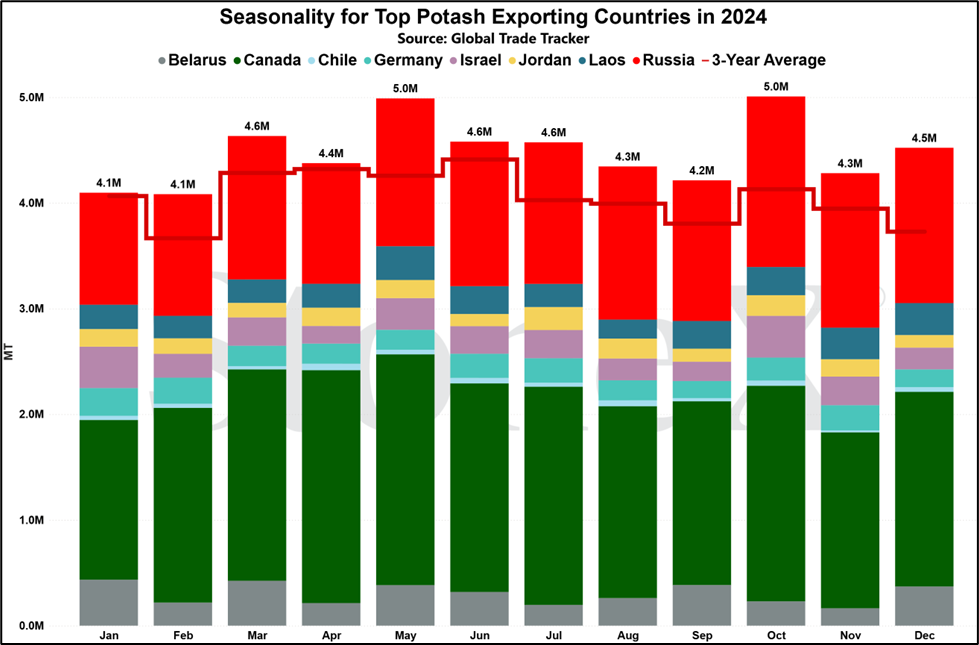
These countries are all major potash buyers as you can see above on the top 10 import graph. Yes, Russia is a major potash exporter, but these 3 countries alone could easily digest what Russia exports. If they ignore western sanctions, Russian potash has little to worry about. Sure, they will need to contemplate these new trade flows, but trade flows are likely to continue.
However, what happens if these countries are effectively forced to follow along? That is where this story could take a dark turn.
With Russia being such a major supplier to the world, any downturn in export flows would have a major impact on the global S&D.
Again, lets remember that the current chances of lower Russian exports is very low. It would take near global support of sanctions to start fundamentally changing the potash market. However, we should keep a close eye until peace is finally found.
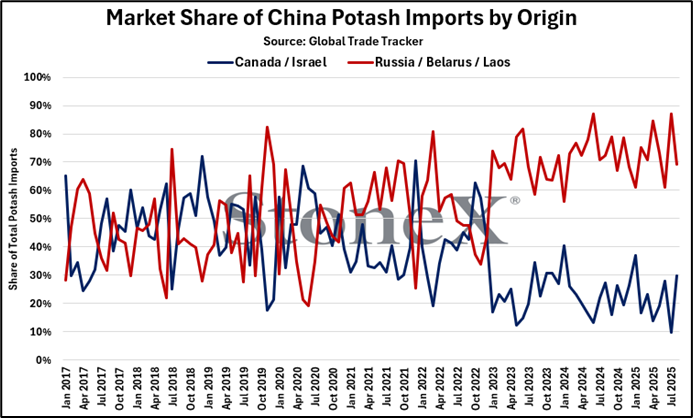
Chinese potash supply origins show a changing global potash market
This piece doesn't really do anything to describe a massive change in the global potash market. It doesn't change demand. It doesn't change supply.
It does, however, show how global trade flows are shifting as government relationships change.
For years, China was highly reliant on potash supplies from Canada (and Israel to a certain extent). It was a normal trade flow that wasn't really ever questioned. However, in recent years, the Chinese government has been shifting its approach.
China hasn't exactly been the biggest fan of western nations and we have seen in recent years that the government is starting to take notice more of its fertilizer markets. Its heavy handed approach to its urea and phosphate export allowances show that the government understands the power it wields. For urea and phosphate, is realized that by cutting back on export flows, it could maintain very large domestic stockpiles which weighed on domestic price ideas. Both are wins for its farmers. However, China is a very large importer of potash. That means it does not have the same power as it does over its exports...
...but that does not mean it does not have power...
Rather than continuing to rely on supplies from western countries, we have seen a shift more toward tons supplied by allied countries like Russia, Belarus, and Laos. No doubt from their vantage point, if they are going to spend money on potash, it is better to send those cash flows to friendly nations vs sending it to nations it seems to view as an enemy.
Again, this does very little to nothing to change the global S&D. This does not do anything to substantially change price ideas around the world. However, it does a great job of showing how global politics can have an impact on trade flows.
N.A. fall application weeks away, questions remain on demand
North American farmers are heavy into harvest which means one thing: fall fertilizer application is just around the corner!
At this point, we are about a month away from most regions going to the ground with their fall applications but one question remains unanswered: what is demand going to look like?
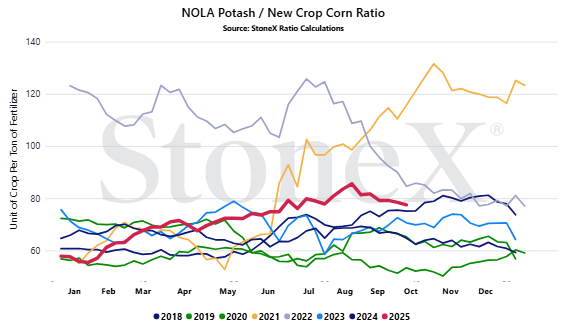
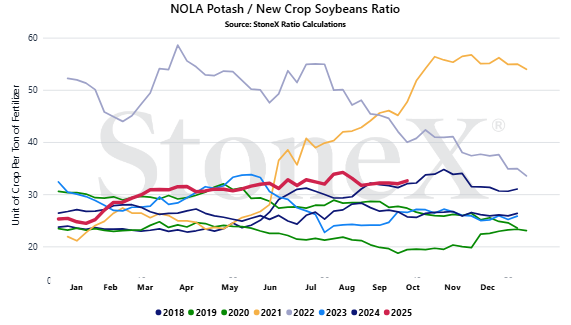
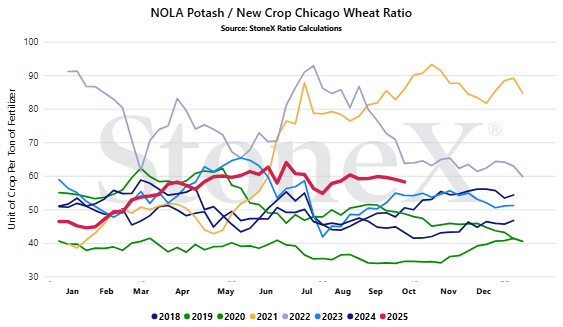
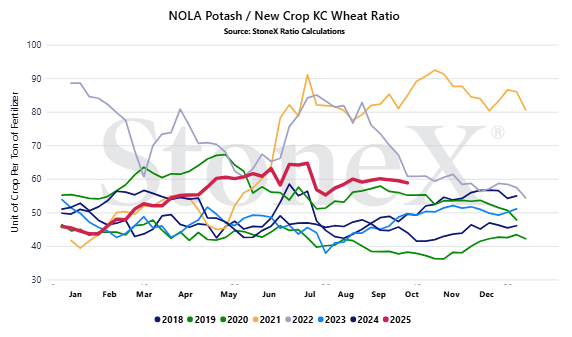
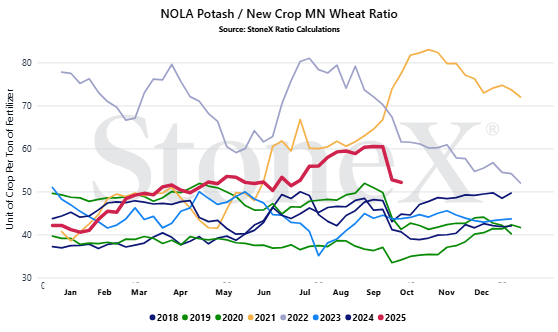
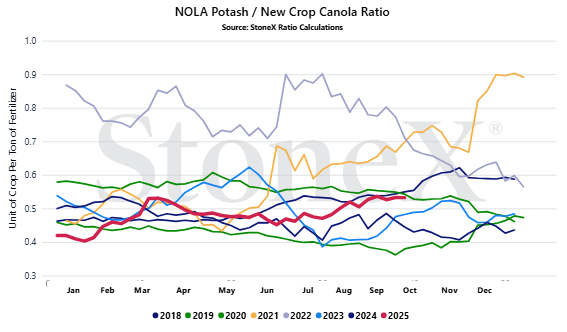
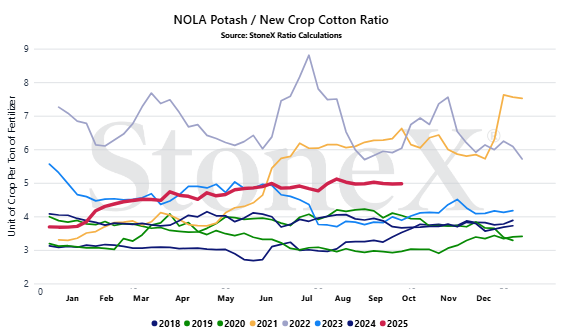
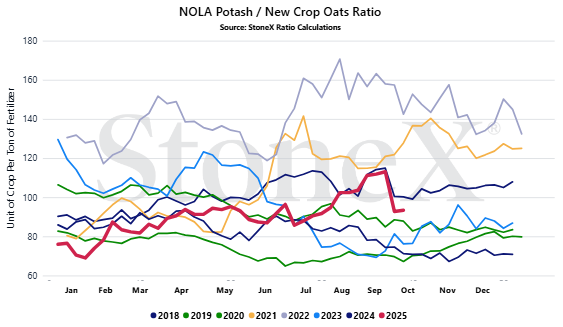
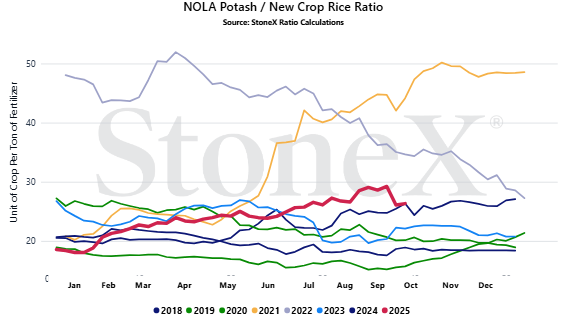
If you scroll toward the bottom of this newsletter to the ratio chart section, you should notice that the potash charts are not terrible. Well, let me back up. The potash/grain ratios are still on the higher side. Maybe a better way to say that is that potash is nowhere near as high as what we are seeing for nitrogen and phosphate ratio charts. In comparison, potash almost "feels" decently priced (it isn't...).
If we only looked at it from this POV, one would think that potash demand this fall is going to be solid. However, conversations would quickly dispel that notion.
This is why we are 30 days from the widespread start of fall application season and we still have more questions than answers.
These are the different POV's that folks in the market seem to have today:
Potash is decently priced by itself/vs other high fertilizer prices
I am using the term "decent" very loosely. In no way am I saying that it is cheap. What I am saying is that compared to its own historical pricing and against the other fertilizers high prices, potash tends to be one of the most attractive values out there. This could help boost demand this fall.
Phosphate prices are sky high, should increase potash demand
Most everyone agrees that phosphate values are outrageously high priced. The most common discussion point out there is just how much phosphate demand destruction there will be this fall. So what does this mean for potash? There is a group that believes potash demand will be higher as a result. As farmers look at phosphates high price, there could be a shift of spending over to potash. My fear is that this assumes there is cash to spend...
Phosphate prices are sky high, will hurt potash demand
To me, this seems the more likely result. Farmers are not likely to pay to apply their potash in the fall and then pay again to apply their phosphate in the spring. If the price of phosphate is so high that farmers drag their feet in hopes of better times this winter/next spring, it could cut the knee's out from potash demand. Today, this is where my head is.
Yields look to be solid, removes a lot of nutrients that need replaced
This is my biggest fear factor for not only potash, but phosphate. Farmers have rightfully been screaming about the high price of fertilizers. The numbers simply do not work today for a lot of operations. I do not believe anyone has been fibbing about their intentions to reduce/cut their fertilizer applications this fall. However, there is a big crop out there. I am not going to get into the "how big" conversation. Not my place. Realistically, it is still going to be a large overall yield. That means a lot of nutrients are going to be removed from the dirt. As farmers see their yield monitors popping off big numbers, the realization that replacement needs to happen starts happening. Suddenly, we could see a late October/early November demand wave...that could have big implications on the market.
Normally by this point, we have a pretty good idea of what is coming and the market can prepare for it. This year is not normal. This year is seeing far too high fertilizer prices against far too low grain prices. This year is seeing farmers struggling more financially than they have in a very long time.
That means this year is going to be different with uncertainty being the only constant. My only advice is that once you know you need something for the fall, go have that conversation with your coop/retailer/supplier/etc. This fall could get...messy.
Where are current values in relation to the past
NOLA/New Orleans Louisiana
Vs 30 days ago - -1% or approximately $5 lower
Vs 90 days ago - -7% or approximately $25 lower
Vs 6 months ago - 3% or approximately $10 higher
Vs 1 year ago - 25% or approximately $65 higher
U.S. Midwest Average (average of several points across the Midwest)
Vs 30 days ago - -3% or approximately $10 lower
Vs 90 days ago - -5% or approximately $18 lower
Vs 6 months ago - 4% or approximately $16 higher
Vs 1 year ago - 13% or approximately $42 higher
Bull/Bear Factors
Because no market is ever guaranteed to go higher/lower, we try to consider the factors that can sway values so that we are able to act when they occur rather than react.
- Bullish Factors
- Any sort of traction regarding Russian sanctions – as mentioned so many times across all the products this month, President Trump threatening tariffs against Russia is a big deal. Now, the chances that sanctions happen and are widely adopted enough around the world to the point that Russia exports start to slow/stop is incredibly low. Russia has too many "friendly" countries that are likely to ignore the west. However, if we start down the road and that looks more likely, watch out.
- N.A. fall season sees bigger demand due to high phosphate pricing - we will get this answer in a couple months. I have heard feedback across the full spectrum for fall potash demand. Anywhere from "I'm not touching anything" to "I'm going heavy on potash in spite of phosphate". If that latter crowd becomes more popular, potash may be in for a demand surprise. If farmers edge away from phosphate and decide to use those funds on potash to build those soil levels, that surprise will keep supplies low and prices supported.
- U.S. pushes through farmer assistance checks – this is something no one is going to like reading...but it is the truth. If the U.S. government goes ahead with the currently expected farmer assistance checks, I would expect fertilizer prices to jump. That is because fertilizers like potash and phosphates will be the first cut from programs. However, if money rolls in, potash could be one of the first to benefit. That surge of demand will hit the market and likely cause prices to jump.
- Bearish Factors
- Russia/Ukraine peace starts to find traction – add this to the list of "stupidly low probability" events. However, all wars eventually find peace so we have to continue watching for it. Now, I do not think that peace would change Russia's export flows. They are already shipping out huge amounts of potash. What it could do is remove any war-time premiums as well as allow the world to go back to normal global trade routes which could also lower price ideas. It wouldn't be major, but we will take what we can get at this point.
- N.A. fall demand is lower due to poor farmer economics - the story of 2025 is that farmers are struggling. My fear is that the story will be repeated in 2026. If today's outlook is any indication, that will be the case. The market thinks that demand has to come. To a certain extent, it is right...but not completely. Farmers very well may skip fall application in hopes of lower winter/spring pricing. Farmers may skip fall application because they do not have the funds to pay for it. If we get into the fall season and demand isn't there as expected, it will send a shiver up the spine of the supply market. That typically has sellers more aggressive.
- Belarus continues to take steps to returning normal global relations – this is another very low probability, but it is still worth watching. Belarus has taken very small steps toward improving its relationship with the world after allowing Russia to use its lands to invade Ukraine years ago. Their biggest penalty was losing access to Lithuania where they sent their potash to be exported to the world. If Belarus were to find common ground with Lithuania to the point that relations returned to normal, those trade flows could resume as well. Again, very low probability, but worth keeping on the radar.
Where are the current potash/grain ratio values today
We believe that only looking at the flat price of either grains or fertilizer can be misleading:
We look at the ratio "value" to get a better indication of where we are or how many bushels of X does it take to pay for 1 ton of fertilizer.
Would you rather:
When we compare the current ratio value against recent years, we start to see if we are high or low.
YOUR VALUES MAY LOOK DIFFERENT
This graph looks at the NOLA potash price vs the flat grain price. There are no logistics on either product. Your location will look different due to fertilizer logistical costs, grain basis, etc.
- Josh Linville’s Focal Points
- The world vs Russia, can it affect their potash export flows? - given that Russia is the 2nd largest potash exporter in the world, this matters. As I have said repeatedly this month, I think the chance that everyone in the world will adhere to sanctions that block trade flow with Russia is very low. Countries like China, India, and Brazil have shown little issue in going against "western" decisions if it means locking in guaranteed fertilizer supplies at lower prices. However, in the event that Russia exports are harmed, watch out. Potash prices could jump without warning.
- Will fall demand be higher/lower because of high phosphate values? - I continue to get different feedback on this. Some tell me that because the price of phosphate is so high, they will take the money they would have spent on it and put it into higher potash applications. Others say that because phosphate is gobbling up so much cash, they will lower their potash rates to offset. That doesn't even get into the "will I apply or not this fall" conversation. At this point, it is still too early to tell which story wins out. Probably will not know this answer until late November/December. However, your decision may very well get mirrored by those around you. Basically, you may know FAR more than the market before the market figures it out.
- Will overall poor farmer economics hurt potash on its own? - this goes more into the will we/won't we/when will we conversation. Farmers are hurting. I do not need to tell you that. Cash flows are tight. I think we are going to see a lot more folks waiting until the last minute this fall before buying what they need OR deciding to wait until spring to see what happens by then. Poor outlooks change buying habits which absolutely can affect markets.
StoneX Ratio Calculation
The ratio calculation is derived from Bloomberg historical grains values as well as fertilizer values from StoneX, NPKFAS, and Argus.
The calculation is simply dividing the fertilizer price by each grain price.
All data was sourced from StoneX unless otherwise noted.
This material should be construed as the solicitation of an account, order, and/or services and represents the opinions and viewpoints of the individual authors or presenters. It does not constitute an individualized recommendation or take into account the particular trading objectives, financial situations, or needs of individual customers.
The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.
The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.
References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.
StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.
R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.
StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.
This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.
StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).
SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.
StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.
StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.
StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.
StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.
Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.
The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.
© 2026 StoneX Group Inc. All Rights Reserved.