Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Bi-Weekly Plastics Report - August 7, 2026

Alex Hodes
Alex Hodes

Energy Analyst - KC Energy

Polyethylene (PE)

  • U.S. polyethylene prices fell by 10cpp on the month and appear to be headed for more downward pricing. Supply continues to outpace demand, and exports have started to reduce substantially.
  • Feedstocks have not been supportive of PE pricing but continued disruptions upstream could have an effect on crude oil and natural gas pricing ahead. 

Supply

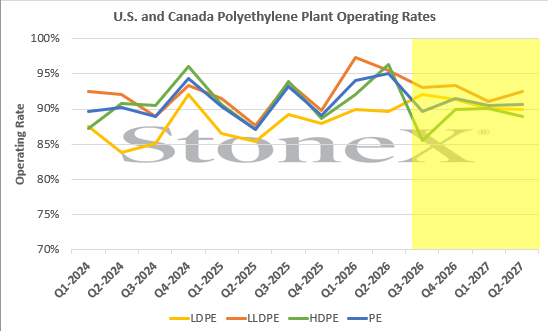
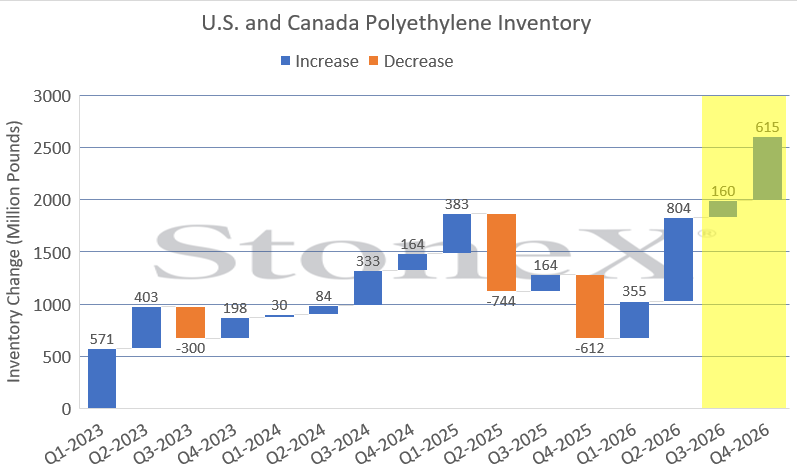
The supply side appears ample but producers have started to moderate their operating rates. U.S. and Canadian PE production fell 6.8% from May to June but still are running at elevated levels of 92.7%. Year-to-date production numbers are up 8% since 2025. Days of inventory fell from 54 days in May to 49.9 in June, which is above the 12-month and 24-month averages - indicating that inventories are well-supplied. 

Demand

Domestic demand remains stable but exports have softened substantially. The balancing act has been by producers who have started to throttle rates lower. Domestic demand was up 4.1% from May to June but buyers remain cautious after several months of falling prices and are largely restocking only as needed. 

Export demand is a large concern after the huge surge in exports helped lift markets in April and May. Year-to-date exports are still up from 2025 but May export levels are reported to be near the lowest level since October of 2024. Buyers abroad have stepped back and are waiting for lower prices. However, the recent escalation once again in the Middle East could have buyers start to jump back in. 


image-20260708101742-1

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

image-20260708101859-2

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

Feedstocks

Ethylene costs moved slightly higher in July but the feedstock prices have not offset the weaker resin fundamentals. Further upstream, natural gas prices continue to move lower - hitting their lowest point in 2026. North America still has a structural cost advantage, but that advantage is being diluted by weak export netbacks, Chinese export competition, and the possibility that Middle East supply gradually returns. The EU tariff removal on U.S. PE is a constructive development and should support flows into Europe, but it is unlikely to fully offset the broader global oversupply pressure.


Price Outlook

PE contract pricing was down 10cpp on the month and the momentum continues to be moving lower. However, current markets are pricing their lowpoint in October before stabilizing. Markets still have a large amount of upside potential - with the Strait of Hormuz and expanded disruptions in the Red Sea affecting oil and gas markets. Supportive crude oil prices should eventually spill over into feedstock pricing, and any ethylene production disruptions could cause price spikes but the current momentum is down. 

Polypropylene (PP)

  • Polypropylene prices rebounded - moving 3cpp higher on the month. The ongoing risk to Strait of Hormuz flows has helped keep exports supported. 
  • Polymer-grade-propylene (PGP) supply tightened over the month after several PDH units went offline. PGP pricing will be very important with regards to PP pricing ahead - and remains to be the single source of potential upside price risk. 

Supply

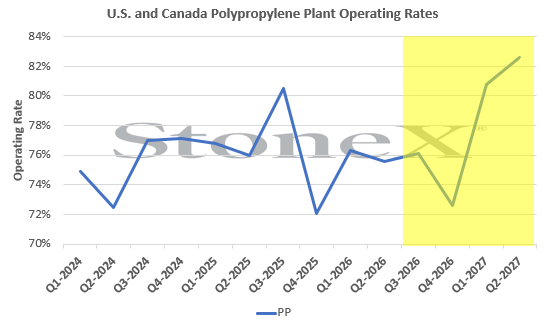
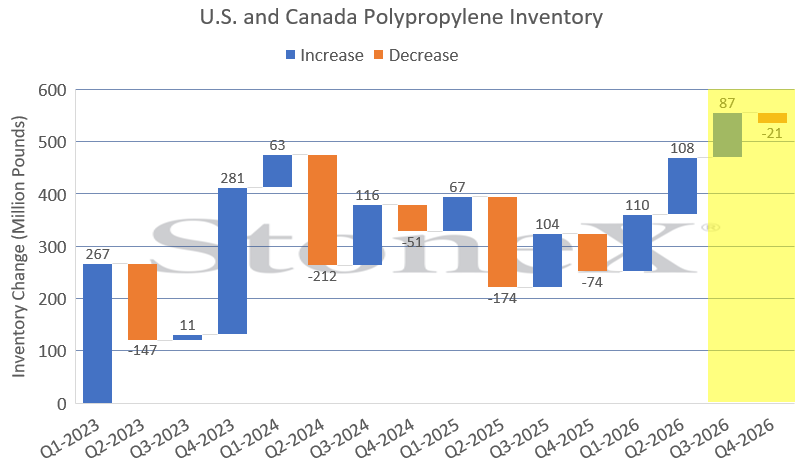
North American PP supply is healthy but producers are throttling rates currently - going from 82.8% in May to 80.3% in June. Production in 2026 is still outpacing 2025 levels but now we are seeing days of inventory tightening somewhat. Outages in August and September could add to the drop in inventory and production is expected to stay capped. 

Demand

Domestic demand is steady but it has not been enough to absorb production if exports start to retreat. Domestic demand is up 1.4% from May to June and almost flat with 2025 year-to-date levels. End-use demand is mixed but is stronger than demand in PE. Exports remain elevated but are expected to decline ahead. Exports are up 58.6% year-over-year in May from 2025 as buyers look to the U.S. to fulfill their appetite. Continued disruptions in the Strait of Hormuz may provide more support for U.S. exports and will provide the outlet for markets to be supported. 

image-20260708102429-4

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

image-20260708102222-3

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

Feedstocks

PGP spot prices were volatile. U.S. PGP spot prices ranged from the high 30s to the high 40s cpp during July due to outages, but prices fell into the low-to-mid 30s by the end of the month. Capacity availability fell to 83% in July, down 3 percentage points from June. Enterprise PDH 1 had a brief disruption, Enterprise PDH 2 was offline in mid-July, and Dow’s PDH was down for planned maintenance. There is expected to be a return of some PDH plants in August which could put pressure downward on PGP and the big question will be whether China reduces its PDH rates if the Strait of Hormuz remains closed. 

Price Outlook

PP prices are expected to move lower in August. July GP homopolymer contract prices moved to 73.5-77.5 cpp, and injection-molding copolymer moved to 76.5-81.5 cpp. Spot domestic PP fell 3.25 cpp in July to 52.5 cpp FOB Houston, while export prices averaged 56 cpp FAS USGC and DAP Laredo prices fell to 55.75 cpp. The disconnect between higher contracts and weaker spot/export values is the key reason margins are expected to compress. Feedstock modeled PP prices are about 5-6cpp lower than what CMA indexes are pointing to - suggesting margin compression is expected. 

The biggest upside risk is renewed Middle East disruption. If the Strait of Hormuz or Bab el-Mandeb remain restricted and Middle Eastern PP exports cannot normalize, the expected August/September margin compression may need to be revised. The potential upside is where the risk lies - especially in the very near-term to Q4 of 2026. 

  • Energy

This material should be construed as the solicitation of an account, order, and/or services and represents the opinions and viewpoints of the individual authors or presenters. It does not constitute an individualized recommendation or take into account the particular trading objectives, financial situations, or needs of individual customers.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.
Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Energy

Perspective: Morning Commentary for October 26

October 26 – Stock futures pointed modestly higher overnight as we head into “Fed Week” on Wall Street, but traders will be monitoring plenty of other potential market-moving headlines as we go through the week. We still have two wars on commodity logistics in major commodity producing areas of the world that have every appearance of escalating in the days and weeks ahead, instability continues in France, increasing demand for U.S. Treasuries, and now we can through Brazil into the mix of places where political uncertainty has significant implications. The VIX remains modestly elevated near 19 this morning as a result, while the dollar index trades near 101.9. Yields on 10-year Treasuries are trading near 4.99% at this hour, while yields on 2-year Treasuries are trading near 4.71%. WTI crude oil is trading notably lower near $102, while Brent trades near $116 per barrel. The grain and oilseed markets were also mostly lower to start the week.

Arlan Suderman
Arlan Suderman
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for October 23

October 23 – The tech heavy Nasdaq saw its worst day since June yesterday, closing 2.9% lower, with concerns regarding the sustainability of the ongoing AI buildout in the backdrop of rising borrowing costs and increasing sovereign debt driving investors into safe havens, as evidenced by the surge in buying in the bond markets. Stock futures are pointing to a lower open again today, though Nasdaq futures are showing the smallest losses among the major indexes, a potential sign of an easing of selling pressure in the tech sector. The VIX is up 6% to start the day, trading just below 20.2 at the time of writing, hovering near its highest level since last Friday. The dollar is looking at a quiet start to the day after a largely quiet week, sitting just above unchanged near 101.68. Treasury yields are modestly higher this morning after falling notably this week, with 2-year yields at 4.66%, 10-year yields at 4.97%, and 30-year yields just above 5.29%. Crude oil prices are on the rise as the market rebuilds geopolitical risk premium amid escalatory rhetoric from the U.S. / Israel and Iran, raising fears of renewed and potentially even more intense back-and-forth strikes. Nearby WTI is up 2.5% to start the day, carving out a fresh five-week high of $101.60 at the time of writing, while nearby Brent is up another 1.35% on the day to trade near $114.70, nearing a six-month high. Meanwhile, the ags are looking at a quietly mixed open.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Hormuz Disruption Keeps Brent Elevated and Stagflation Fears Alive

Strait of Hormuz disruption is keeping Brent crude oil near its yearly highs, and the inflation cost is landing on major economies. A breakout would deepen stagflation risk, while a de-escalation path would ease the pressure.

Razan Hilal
Razan Hilal
  • Energy
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.