Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Bi-Weekly Plastics Report - June 17, 2026

By: Alex Hodes, Energy Analyst - KC Energy

Polyethylene (PE)

  • U.S. polyethylene prices were flat on the month in May and are now expected to move lower in June. The bullish case for prices is if peace does not return and if normal flows do not resume as quickly as the market anticipates. 
  • Feedstock prices have been moving lower - especially ethylene as supplies are ample. Expect feedstocks to not be an area of support moving forward. 

Supply

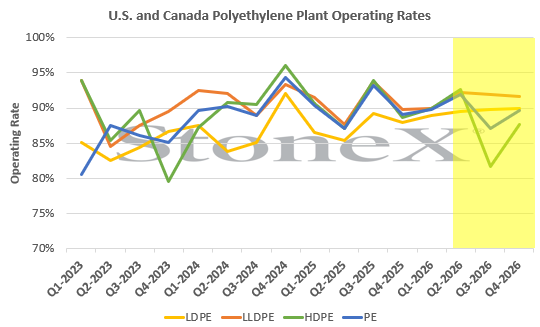
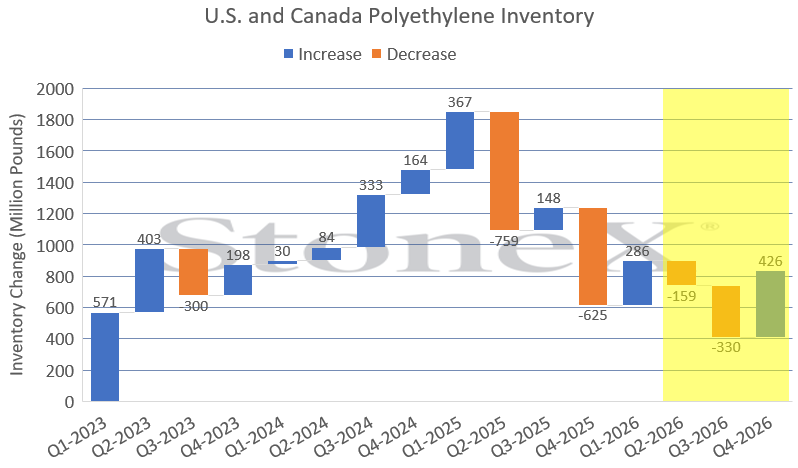
The supply side remains highly active, but the tightness seen in March and April has eased. May PE production in North America was around 5.77 billion pounds (up 2.2% from April), with operating rates near 98%, as producers responded to strong export demand and elevated margins. Days of inventory increased from 42.5 days in April to 54.4 days at the end of May due to production outpacing demand. Producers still have strong cost advantages, but the market no longer appears supply-short in the near term.

Demand

Domestic PE demand remains relatively healthy, but it is no longer strong enough to offset slower export activity. March domestic PE sales reached a record level, but by May domestic demand had moderated to 2.87 billion pounds. Buyers appear more cautious after the April price spike, and many are waiting for additional price relief before restocking aggressively.

Asian demand remains a major concern. Mainland China and other Asian markets have shown weak downstream demand, cautious procurement, and increasing availability of competitively priced cargoes. This has reduced the urgency for global buyers to chase U.S. material at elevated levels. Demand destruction in Asia was one of the first areas to show up in the market.


image-20260211150922-2

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

image-20260211150941-3

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

Feedstocks

Ethylene costs have been more mixed. Ethylene supply in North America remains adequate, with the market described as long in the near term, but sustained derivative demand could draw down inventories if production remains strong. The bigger picture is that North America still has a structural feedstock advantage, but the benefit is now being offset by falling PE prices and weaker export netbacks. Ethylene prices have been in freefall since May - indicating feedstocks will not be a supportive factor in the near-term.


Price Outlook

PE contract prices were flat in May from the previous huge jump. Buyers have stepped back in anticipation of a deal or a return of more supplies in the market. Prices are currently under pressure and the potential easing of Middle East supplies will alleviate any disruptions. Prices will likely move lower if the peace deal is signed on Friday and supplies begin to flow. 

Polypropylene (PP)

  • Polypropylene prices moved lower in May by 7 cpp after a massive spike the previous month. Prices are not expected to completely fall off and should be supported around the 65cpp level. 
  • Polymer-grade-propylene (PGP) prices moved lower on the month and the supply and demand picture appears healthier than before. An increase in PDH rates in China will likely weigh on PGP pricing ahead. 

Supply

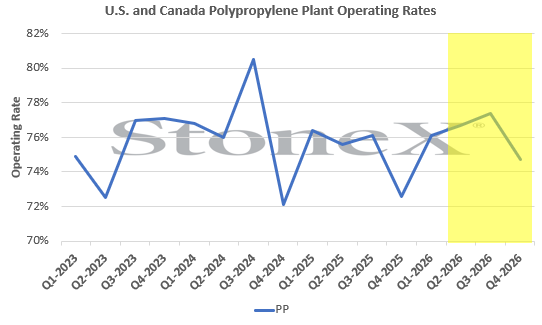
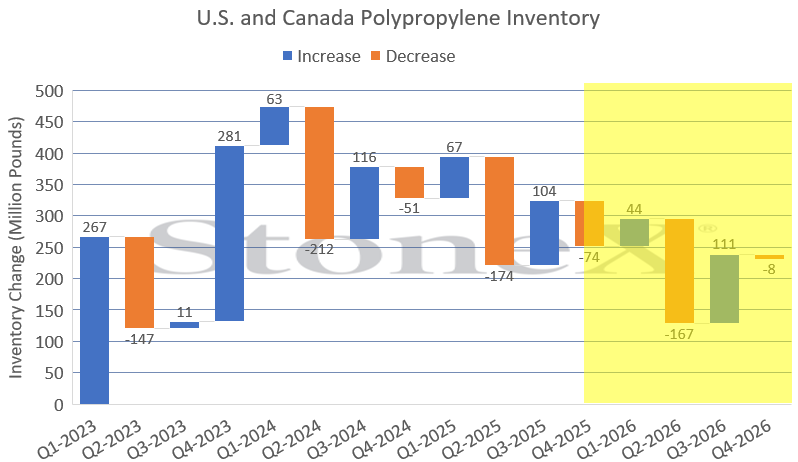
North American PP supply has loosened from the tightest levels seen in April. March operating rates were around 81.1%, and effective operating rates were estimated near 100% in April because outages reduced available capacity while producers ran hard to capture elevated margins. By May, however, the balance shifted. PP inventories have built rapidly as production exceeded total sales, pushing days of inventory from 34.2 days to 38.8 days heading into June. Producers are now expected to throttle rates in the coming months to better match demand and prevent further inventory pressure.

Planned and unplanned outages supported the market earlier in Q2, but the latest data suggest that supply is no longer the dominant bullish factor. The issue is now whether producers can reduce rates quickly enough to prevent oversupply while demand and export markets soften.

Demand

Domestic PP demand appears steady but not strong enough to absorb higher production and weaker exports ahead. March data showed a strong demand rebound, with domestic sales up 12.3% from February and total sales up 14%. Several end-use segments improved, including cups and containers, nonwovens, distributors, and compounders. However, May saw an easing in demand by buyers as prices were elevated.

Exports remain important but are not as dominant for PP as they are for PE. North America benefited when Europe and Latin America looked for replacement supply after Middle East disruptions reduced availability. Still, Asian offers into Europe and South America have created price resistance, and the market expects North American export volumes to decline as Middle Eastern trade normalizes.

image-20260211151057-5

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

image-20260211151038-4

Data Source: American Chemistry Council, Chemical Market Analytics by OPIS *Forecasts shaded in yellow

Feedstocks

Polymer-grade propylene remains the main driver of PP pricing. PGP spot prices rose sharply in April, peaking around 62.5 cpp, as the market dealt with Strait of Hormuz uncertainty, PDH disruptions, and strong derivative demand. Propylene availability was constrained by operational issues at PDH units and crackers, while FCC propylene continued to compete with alkylation economics. However, prices have retreated substantially from their high level and a resumption of PDH plants in China could shift the supply demand balance. 

Price Outlook

PP prices likely peaked in April and we are expecting prices to move slower in the near-term. Producers will likely ease their rates to prevent the market from being too far oversupplied, but the biggest upside risks will be a resumption of the war or price rallies in PGP. 

  • Energy

This material should be construed as the solicitation of an account, order, and/or services and represents the opinions and viewpoints of the individual authors or presenters. It does not constitute an individualized recommendation or take into account the particular trading objectives, financial situations, or needs of individual customers.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Energy

Perspective: Morning Commentary for October 14

October 14 – Stock futures are pointing to a mixed open after yesterday's decline, with all eyes on the upcoming September CPI release this morning as the market looks for signs of the pass-through of inflationary pressures currently held at the producer level. To that end, we’ll also get updated producer level inflation tomorrow with September PPI on tap. The VIX remains relatively muted to start the day, hanging near 15.3 at the time of writing. The dollar is sitting just above unchanged, near 102.25 after a sharp reversal yesterday after reaching a fresh 18-month high on Monday. Treasury yields are off slightly this morning, with 2-year yields at 4.776%, 10-year yields trading back below the 5.20% mark, and 30-year yields at 5.55%. Crude oil is pushing higher to start the day following notable escalations between the Saudis and Houthis, with nearby WTI up 1.2% to trade just above $95.90 and nearby Brent up 0.6% to trade near $106.30. The Houthis launched widespread attacks across Saudi Arabia over the last 24 hours, striking the Aramco headquarters complex in Dhahran while also targeting multiple sites in the Riyadh area, while the Saudis respond with heavy airstrikes on Houthi targets in Yemen, as well as fuel infrastructure in the capital city of Sanaa. Both sides appear to be signaling further escalation ahead, keeping this flashpoint in focus. Meanwhile, the ags are looking at a mixed start to the day, with soybeans seeing the biggest strength and the wheat complex seeing the biggest weakness.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Crude Oil's Middle East Risk Keeps Dollar Bulls Within Easy Reach

Crude oil prices and bond yields are steering the U.S. dollar against the euro, and Middle East military activity keeps the risk of renewed dollar strength in play. Softer energy prices can pull the greenback lower, but the same link can reverse quickly after EUR/USD's five-week slide.

Fawad Razaqzada
Fawad Razaqzada
  • Energy

Perspective: Morning Commentary for October 13

October 13 – Stock futures are pointing to a mixed open as the tech sector sells off both in the U.S. and Asian markets amid a fresh round of AI jitters ahead of upcoming third quarter earnings season. The big banks are kicking off that earnings season today, with mixed results thus far as Goldman Sachs showed a huge earnings beat with its second-best quarterly revue on record, though JPMorgan Chase had a headline earnings miss, taking out some momentum. Traders will continue parsing through this morning’s data and reacting in turn, with more big earnings reports on deck in the days ahead. The VIX is off to a relatively muted start, holding near 15.3 at the time of writing. The dollar is giving back yesterday’s gains as it trades 0.35% lower at the time of writing to hang near 102.2 after closing at a fresh 18-month high on Monday. Treasury yields are mixed as trade resumes, with the front-end of the curve higher and long-end lower this morning, as 2-year yields rise back near 4.80% but 10-year yields fall to 5.206%, and 30-year yields fall to 5.559%. Crude oil is quietly lower to start the day, with nearby WTI down 0.3% on the day to trade near $92.90 and nearby Brent down close to 1% to trade near $105.60. The ags are quietly mixed, with selling pressure seen overnight but fresh escalations in the Black Sea that we’ll dive into below providing support.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.