October '25 UREA
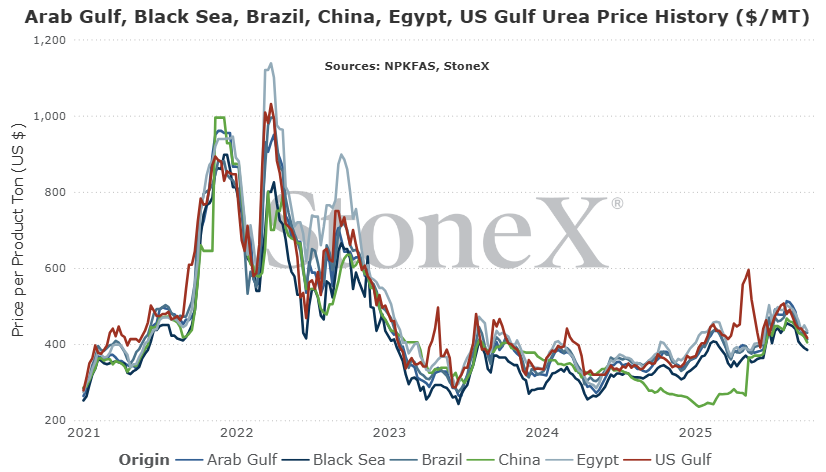
Major Global Urea Export Location Price Graphs
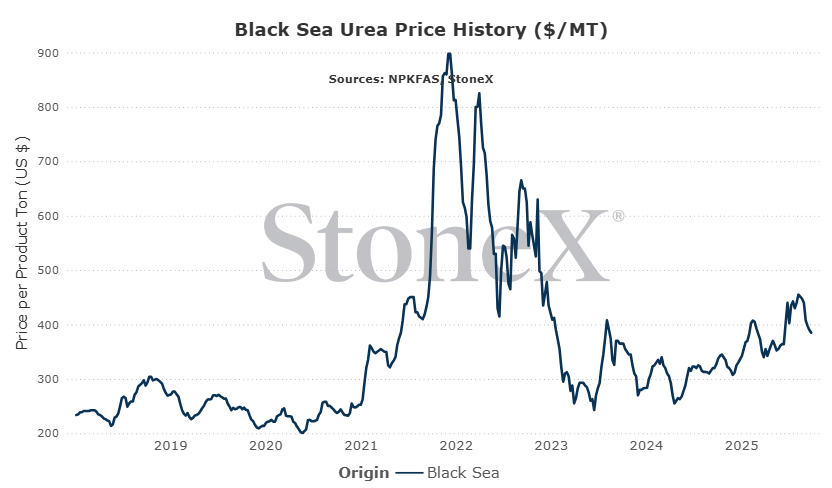
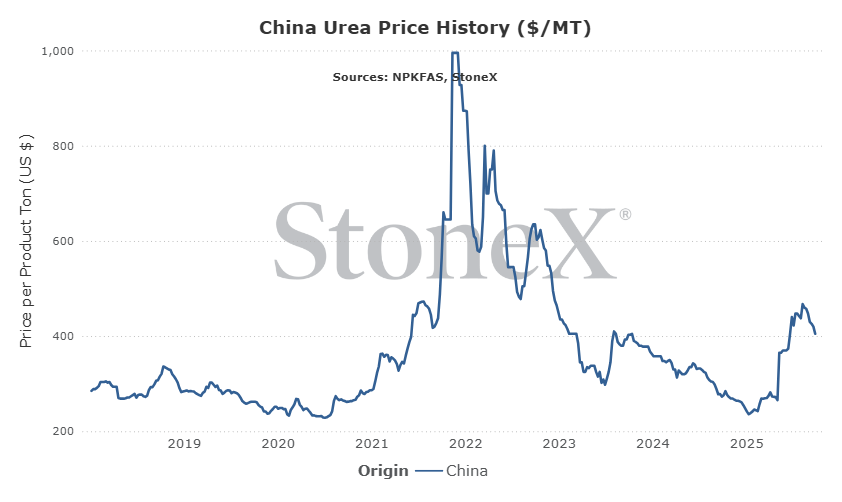
The intention of the below graphs are not to use to say "my price should be X based on this graph". These prices are derived from an FOB price point average. The intent is to show major global price movement trends. Your values will likely have significant basis difference (similar to your local grain price being different than the traded market price).
This graph is labeled as MT in USD currency.
What everyone wants to know first, what do we think will happen going forward
GLOBAL
Right now, we finally have the market set up in favor of the buyer. Global demand has slowed to a crawl. Chinese exports are continuing to ramp up (as expected). India is toying with the market in terms of their next/likely last purchase tender of the year. Global production may not be 100%, but there has not been a shock/surprise recently.
Things are...quiet, and fertilizer struggles with quiet!
However, how long can this last? That is my biggest question. It can certainly last longer than just right now. Farmers around the world who are susceptible to price movements are in no hurry. That could extend this quiet period in favor of the buyer. Eventually, preparations for spring must begin. The longer the market demand waits, the more pressure it puts on nearby values, but the stronger the snap-back demand will be when it hits.
The global urea market has been bearish in recent weeks and that should continue...until buyers return. That is the balancing act global demand must take on. Step in too soon and it limits the downside potential. Step in too late and the rest of the world may step in before and you are left playing catch up. Hoping Chinese exports continue to be large as that creates even more nervousness/bearishness in the market.
NORTH AMERICA
North America is still in the time of year where it needs to stay "attached" to the global market. Get the price too high and imports begin to arrive. Get the price too low and exports begin which means more make up later down the road. With the global market still bearish, so too should N.A. values.
However, couple things to consider. The first is that the initial rounds of demand appear all but dead. Wheat farmers are pulling back (especially in the south) as they struggle with finances. We are also not seeing a lot of excitement for barges that can make the Upper Mississippi River before winter closure. That is helping to tamp down price jumps. Second are inland manufacturers sales books. The combination of earlier sales, their own storage to fill, and numerous inland plant downtime means inland values do not need to drop as fast as is being seen elsewhere. The longer the global price declines, the more pressure it creates, but it can handle a bit for now.
Ultimately, like the world, the N.A. urea outlook remains bearish for now. That said, I also do not think we are that far away from a price that sees buyers returning and that should help provide a price floor. Remember the global and domestic supply situations are still tough. There are pieces missing which is going to provide price stability but for now, at least prices are coming off.
General Global Urea Information
What has happened in the last 30 days?
Chinese exports finally star to flow, helping ease global price ideas
The thing that global urea market bears have been hoping for has finally started to happen.
Chinese urea exports have finally started to arrive and arrive in a big way.
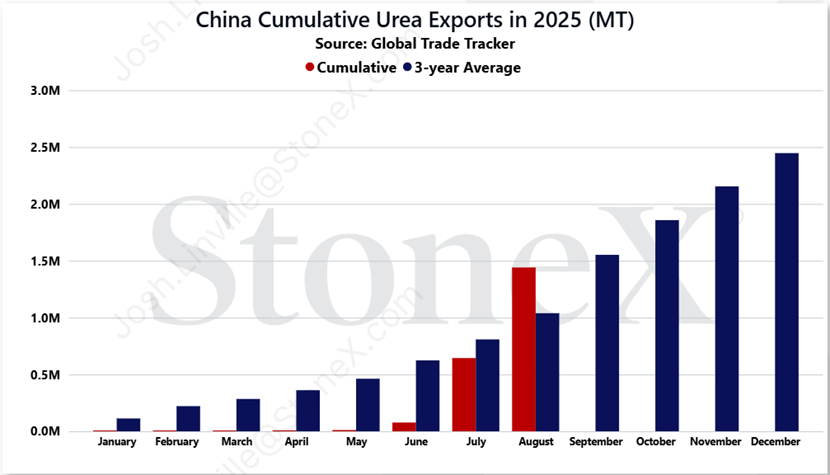
For a bit of backstory, a big reason for urea values to be as high as they were in the first half of the year was the near complete lack of Chinese exports. Historically, China would export between 5 to 5.5M tons on an annual basis. For calendar year 2025, January through June saw a cumulative total of 77K tons. However, as summer started, hope started to grow. The rumors from China were that exports for the year would be 2M tons. Then it rose to 3M tons. Now, the belief is they could export between 4 and 4.25M tons. However, the lingering fear was “when are the tons coming”?
The answer first came in July. 567K tons of urea exports occurred according to Chinese trade data. That was a great step that got them at least close to their 3-year average…even though that 3-year average is about half of what it used to be! However, if July was good, August was great! Trade data showed that nearly 800K tons of urea was exported in the month of August alone! If the market tried to discount the exports in July, there was no ignoring August.
Now, with Chinese exports arriving to the marketplace, there is suddenly much more significant competition.
The question going forward is whether China will stick with their export plans. If they do, they should continue to be a major supplier to the world. This, assuming the government allows it, creates more tons available to India for what should be their last purchase tender of the year. This should free up tons elsewhere that can become available to normal trade lanes.
For now, China’s return is a win for buyers.
Global urea market anxiously watches sanctions threats against Russia
As you have either already read or will read almost repeatedly this month, my focus in recent weeks has been President Trumps shift on Russia. Before, he appeared eager to find peace between Russia and Ukraine. That allowed him to have patience. Unfortunately, it appears that patience has run out. Rather than pushing for peace, he now appears to be solely backing Ukraine and has been much more tough on his comments regarding Russia. Part of those conversations have been centered on possible sanctions.
Now, to be honest, I currently am not expecting to see any sanctions that are so strong that they impede the export flow of Russia’s urea. However, the moment I decide to skip it, something will happen. I would rather cover it and it not happen than vice versa.
If sanctions were to happen, there is a widespread range of effects. This could be anywhere from the U.S. going it alone to a worst-case global urea scenario that includes Russian exports dropping significantly as the world either cannot or will not buy from them.
Let’s start with the scenario where the U.S. goes it alone and what it would mean for the North American markets.
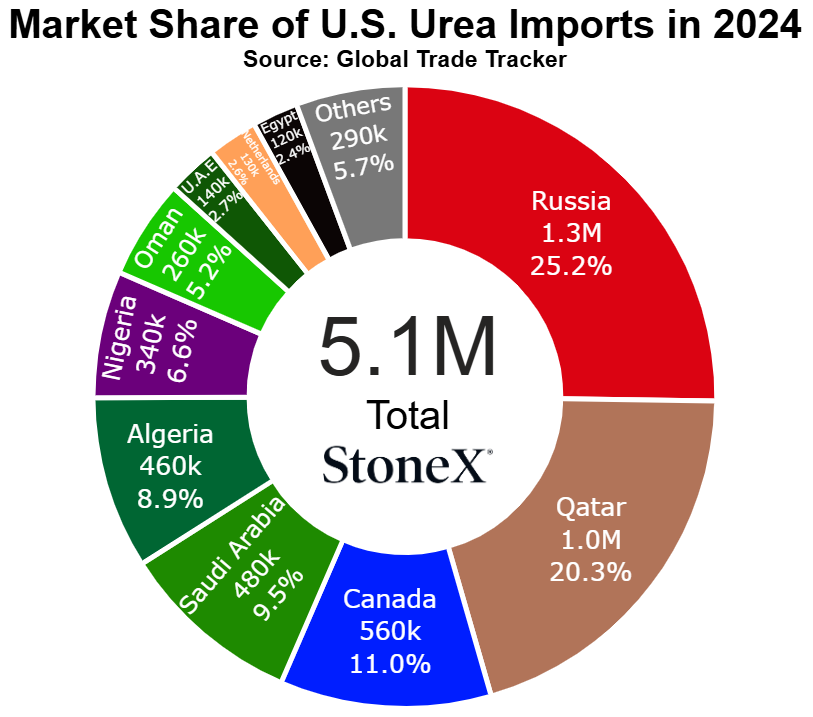
No doubt the immediate reaction would be bullish for North America. Russia has been the U.S. single largest urea supplier in recent years. The loss of this biggest supplier would likely cause a shock through the system. However, after a bit of time, the market would figure out a new “normal”. With only the U.S. blocking Russia, those tons would be able to find new destinations which would free tons to become available to the U.S. It might involve higher freight rates and longer sail times, but a new normal would be established.
How about if western countries blocked Russia? This would cause more of a reaction as global trade flows would be even more impacted. Again, I think a new normal in global trade flows would be found. When you look at demand from only Brazil and India, Russia could target just those two countries and move all the product they export. As both countries have shown in the past, there is a willingness to ignore the west if it ensures guaranteed supplies and lower prices.
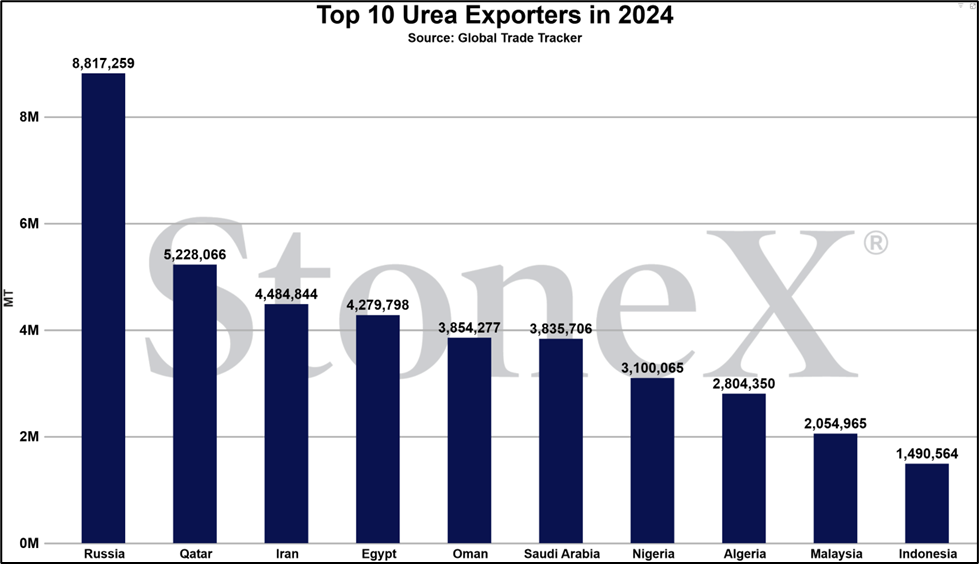
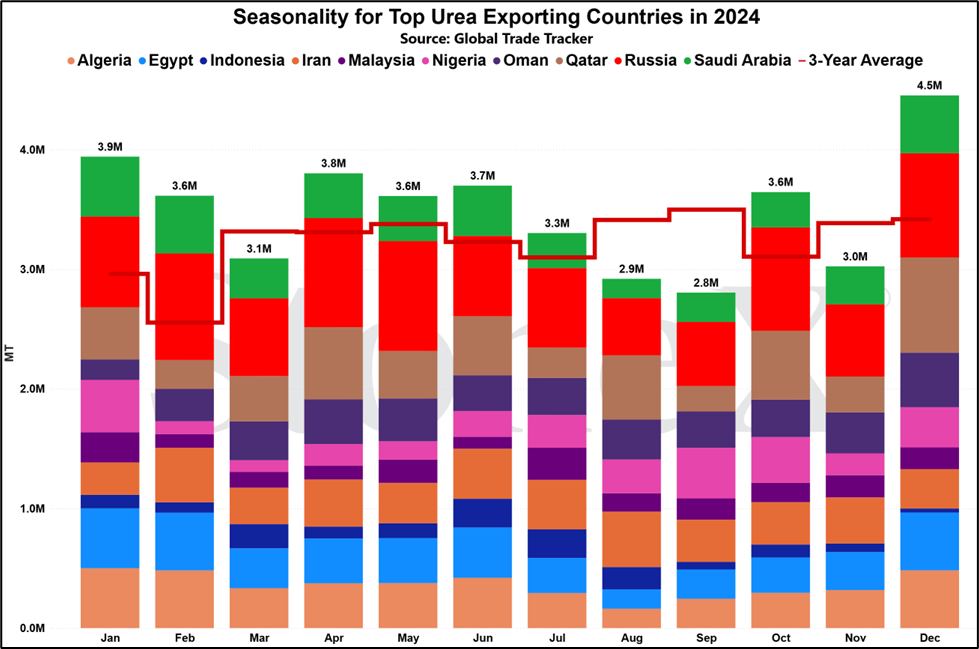
The worst-case scenario is if sanctions were so severe that most of the world stopped doing business with Russia. Now we must consider Russia’s role on the global stage. Look above at the top global export list. Russia sits in the number 1 slot. Number 2 is well below. In this scenario, there are legitimate concerns surrounding global supplies. Think the current phosphate market…
Again, now it does not look like the U.S. is proceeding with sanctions and if they do, it will be likely be something between the U.S. going alone and some western allies signing up. The impacts “should” be minimal…but always keep an eye out. If recent history has taught us anything, it is to expect the unexpected.
India locks up another 2M tons, one more tender expected
India’s most recent urea purchase tender made history from our vantage point!
The combination of a long shipment window (through to October 31) and the surge of Chinese exports meant a record setting 5.6M tons were offered for consideration. India was in full control of what they wanted to purchase. Before the awards were finalized, there was a part of the market that thought they may lock up 3M tons and call it a year. Others believed they would cap it between 1.5M and 2M tons with the hopes of putting more pressure on prices for their next purchase.
In the end, they decided to secure 2M tons. It was certainly a large block of tons, but it still left them short of their needs to finish the year. However, it also left a lot of unsold tons in the world marketplace that wanted/needed a home. This helped to create a bearish environment.
So, what next for India?
Another tender is coming. Demand has been solid following a very good monsoon season. Originally, market expectations were that their last tender would only target 1M tons but that has since been raised to the 1.5M to 2M range. As for the timing of the announcement, it seems the market is expecting something by the first half of October. There are pros and cons to their announcing sooner…and later.
If they announce something soon, they have the market nearly to themselves with a lot of tons still in the market following their last tender. They do not have to compete with other buyers who may swoop in while offers are being put together, which rallies price ideas. They also have the market on their heels, which bodes well for offered values. On the flip side, announce too early and you limit the price downside potential. If India continues to wait, so too may other global buyers. If that continues, unsold inventories grow, putting manufacturers in an uncomfortable position.
However, if they wait, prices may continue to decline. It appears that few buyers around the world are ready to step forward for spring purchases. After years of the Indian government paying hefty subsidy rates, they are no doubt looking for a deal. This comes with more dangers. Will global production continue, or will there be more hiccups as has become the norm in recent years? Will other buyers step forward, setting a floor that would allow the market price to get excited at the tender?
For now, the market sits back and waits.
Urea values starting to look "good" vs UAN, will it matter?
In recent months, I have expressed my concern regarding the UAN marketplace and what that could mean. This last spring saw the nightmare scenario where large parts of North America struggled to find physical supplies in the middle of spring. My POV for this fertilizer year is that our starting line is significantly closer to that ending story.
What does that mean for the price relationship between urea and UAN?
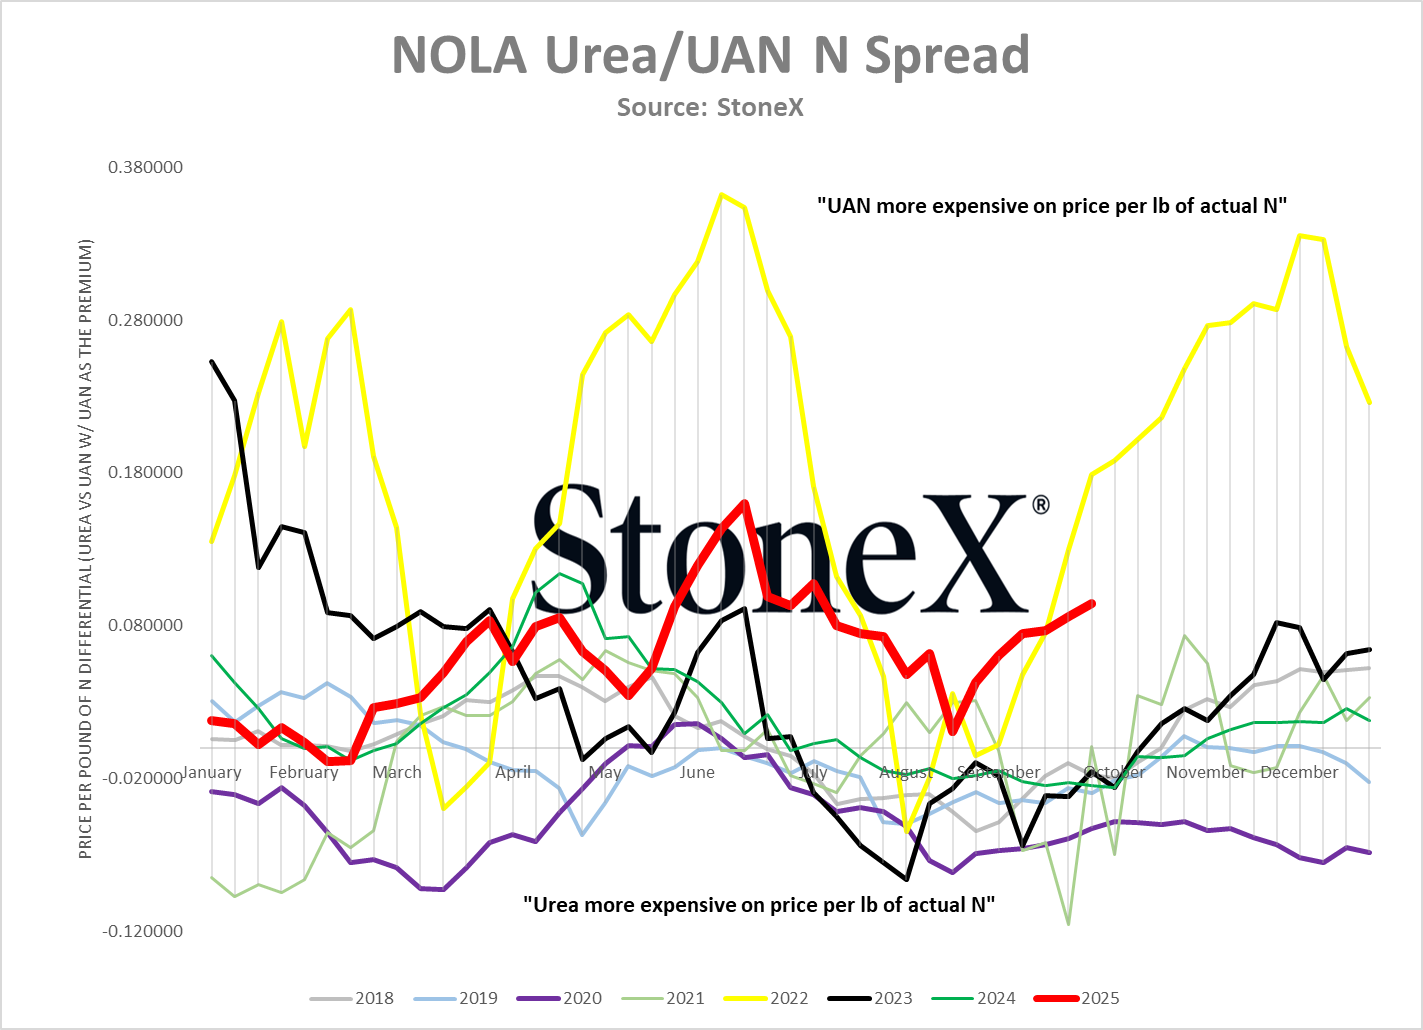
After the UAN market debacle of 2022 and early 2023, the expectation going forward was that NOLA UAN and urea values would be nearly equal on a price per pound of N basis. To an extent, it did that. While it still ebbed and flowed based on seasonality, the price difference between the products was much more in line with normal.
However, there is nothing normal about the current UAN marketplace. That means we can no longer expect the spread to be normal.
With urea values having fallen in the last month, the question for urea is now: what will demand look like? A common theme this month continues to focus on weak farmer finances for 2025 as well as forecasted 2026. Nitrogen demand will be looking to any route forward that is cheaper in an attempt to claw back to break even. When backing away, NH3 is still the best route forward for many, but capacity and capability are capped. However, switching from very expensive UAN to urea (where farmers/retailers already have dry storage and dry application capabilities in place) is easier in a lot of areas.
Basically, as long as the market looks the way it does, we need to consider the possibility that urea demand is going to be higher which may (or may not) present some issues down the road. Fortunately, it is still VERY early in the fertilizer year cycle and farmers/retailers are in no hurry to step forward for spring needs.
All this to point out that if you are considering your spring nitrogen needs and you have the ability to switch, this may be a discussion point worth having.
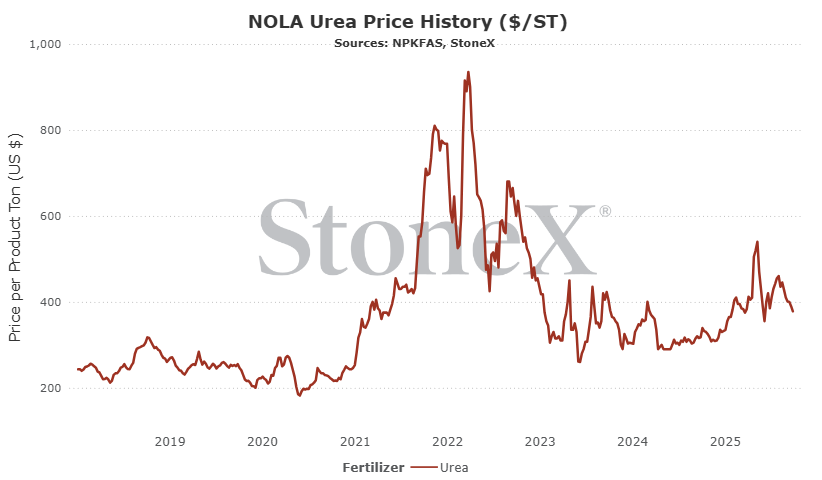
Where are current values in relation to the past
NOLA/New Orleans, Louisiana
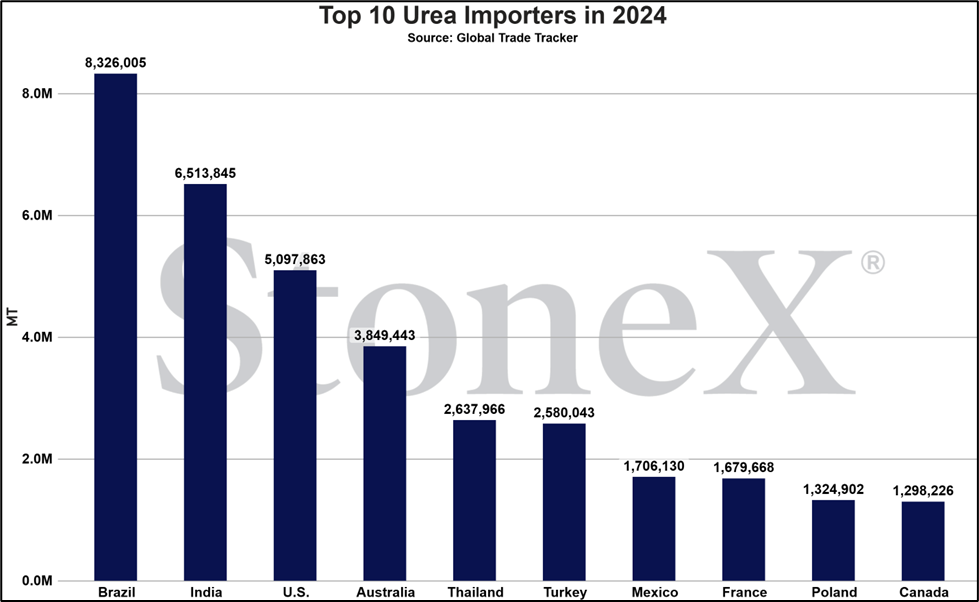
Number 3 global importer in 2024
Price comparisons
Vs 30 days ago - -8% or approximately $32 lower
Vs 90 days ago - -8% or approximately $32 lower
Vs 6 months ago - -8% or approximately $34 lower
Vs 1 year ago - 19% or approximately $61 higher
U.S. Midwest Average
Vs 30 days ago - -6% or approximately $30 lower
Vs 90 days ago - -8% or approximately $39 lower
Vs 6 months ago - -8% or approximately $37 lower
Vs 1 year ago - 22% or approximately $79 higher
U.S. Southern Plains Average
Vs 30 days ago - -12% or approximately $63 lower
Vs 90 days ago - -9% or approximately $43 lower
Vs 6 months ago - -9% or approximately $45 lower
Vs 1 year ago - 22% or approximately $83 higher
U.S. Northern Plains Average
Vs 30 days ago - -7% or approximately $34 lower
Vs 90 days ago - -14% or approximately $74 lower
Vs 6 months ago - -5% or approximately $21 lower
Vs 1 year ago - 23% or approximately $84 higher
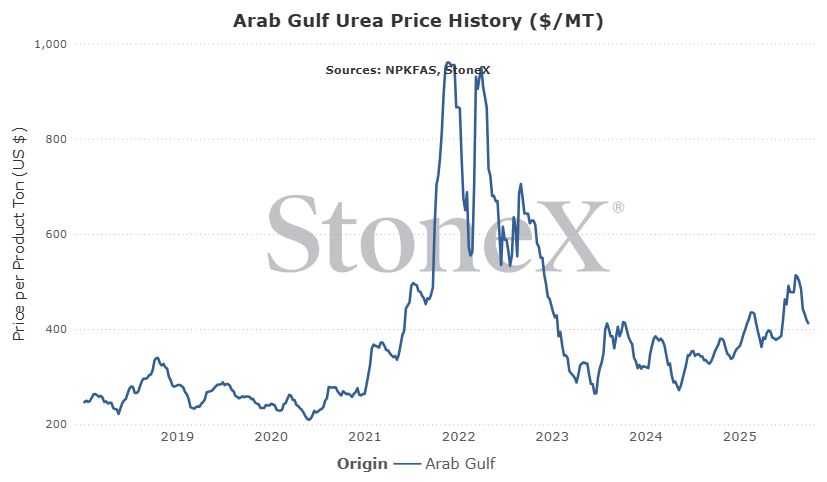
Middle East
Number 1 exporter (as a region, not as individual nations)
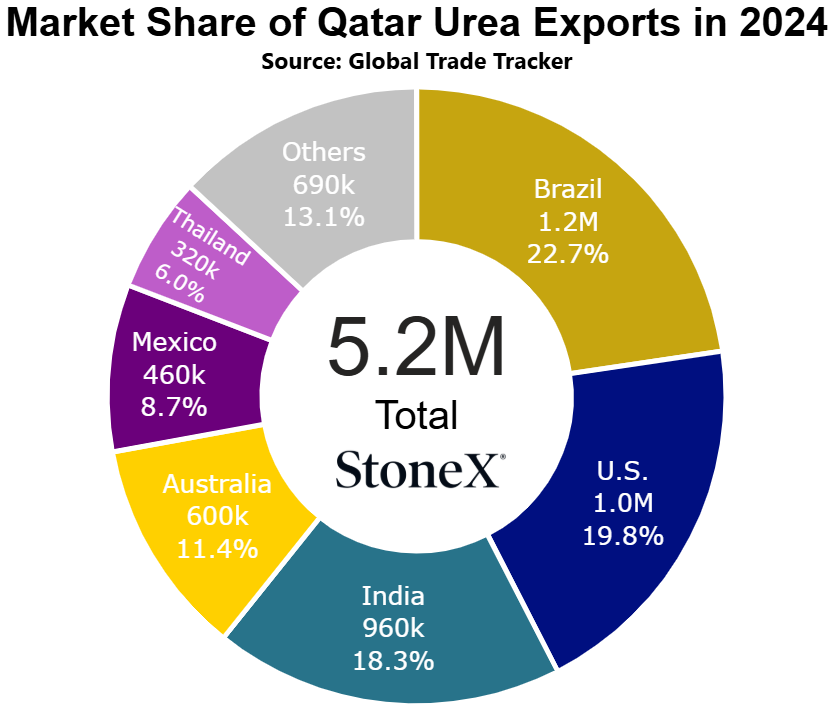
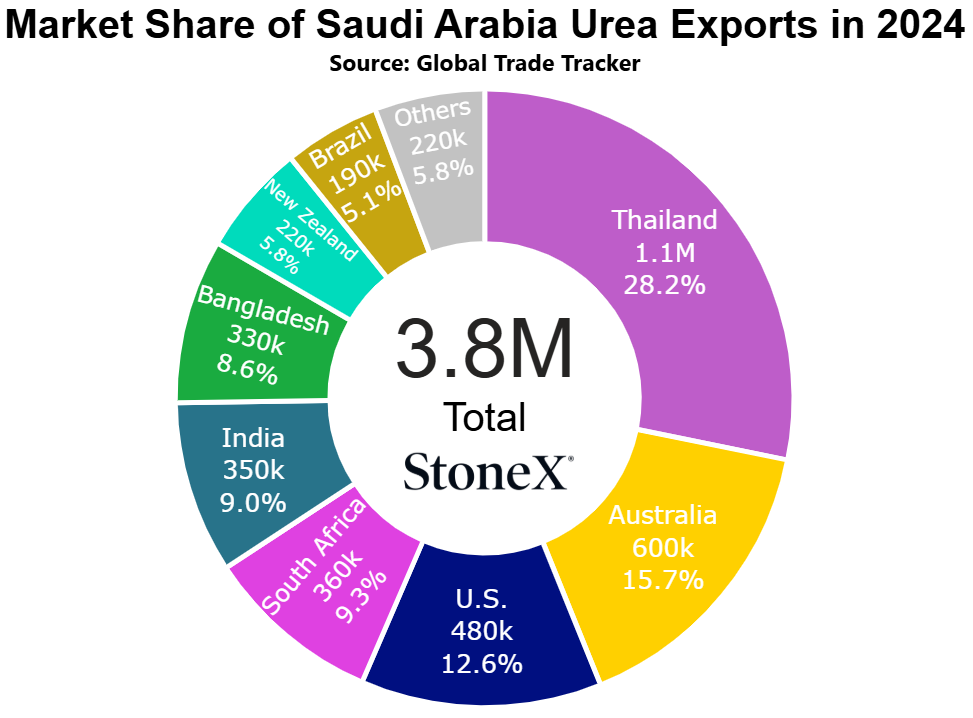
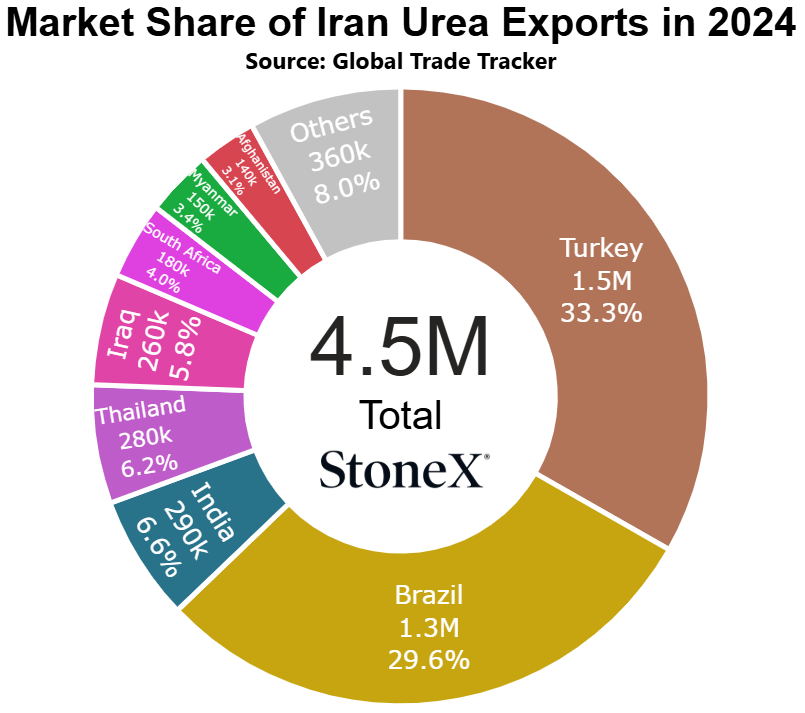
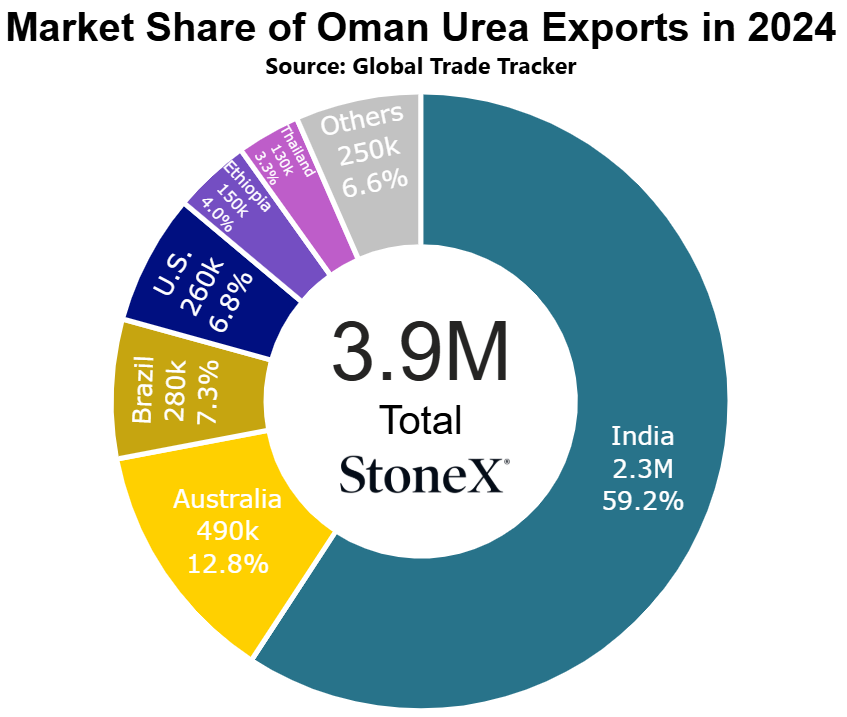
Vs 30 days ago - -15% or approximately $73 lower
Vs 90 days ago - -9% or approximately $40 lower
Vs 6 months ago - 8% or approximately $30 higher
Vs 1 year ago - 17% or approximately $60 higher
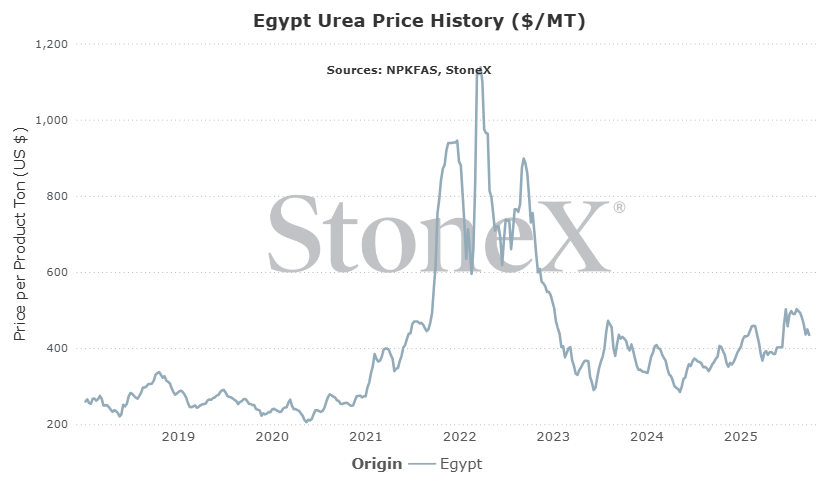
Egypt
Number 4 global exporter in 2024
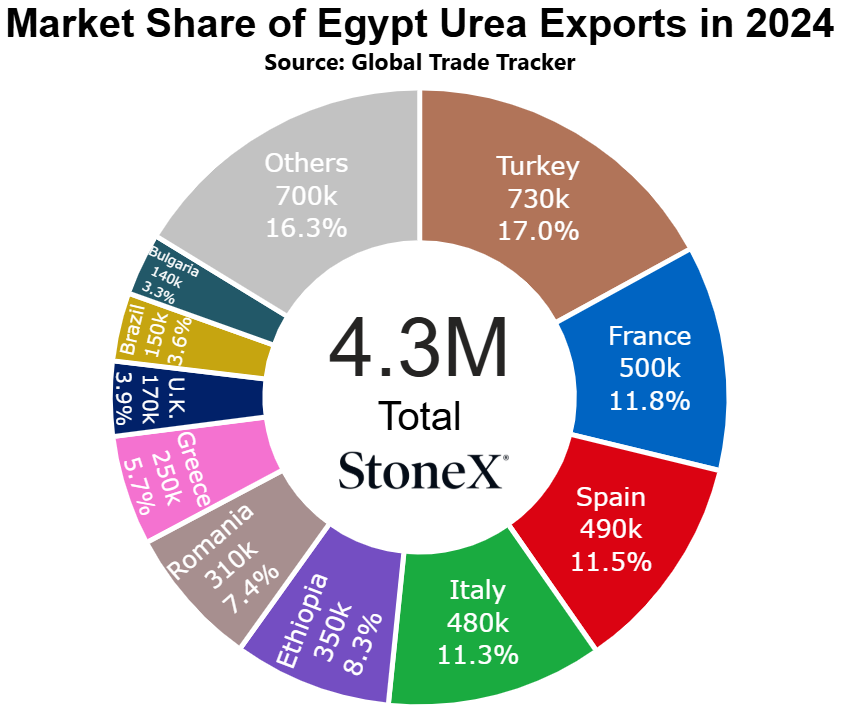
Price comparisons
Vs 30 days ago - -9% or approximately $45 lower
Vs 90 days ago - -5% or approximately $23 lower
Vs 6 months ago - 12% or approximately $48 higher
Vs 1 year ago - 17% or approximately $63 higher
Black Sea
Number 1 global exporter in 2024
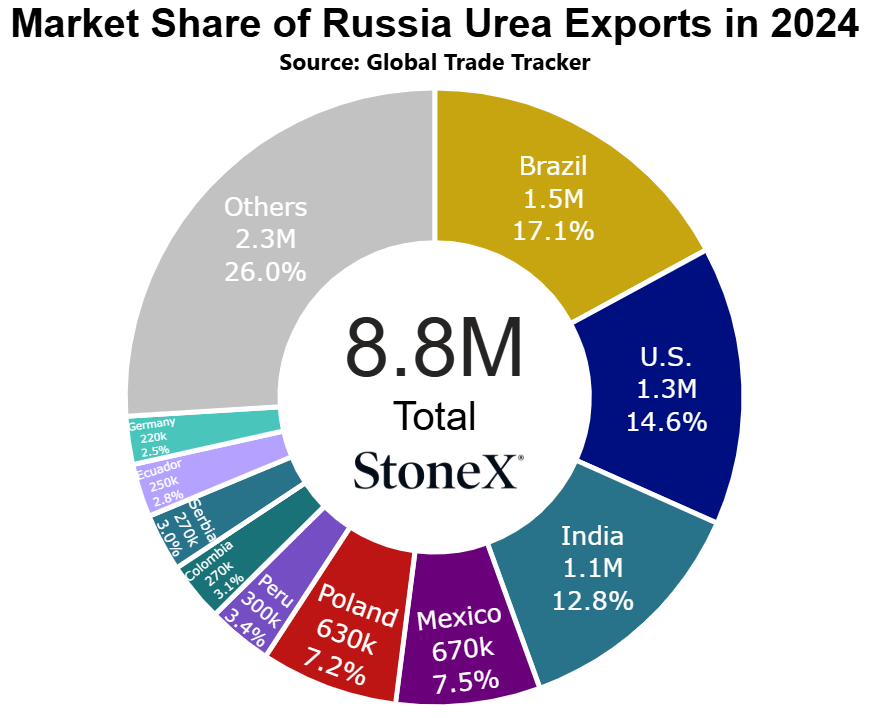
Price comparisons
Vs 30 days ago - -13% or approximately $55 lower
Vs 90 days ago - -4% or approximately $18 lower
Vs 6 months ago - 8% or approximately $30 higher
Vs 1 year ago - 18% or approximately $58 higher
China
Number 5 global exporter in 2023, did not make the top 10 in 2024
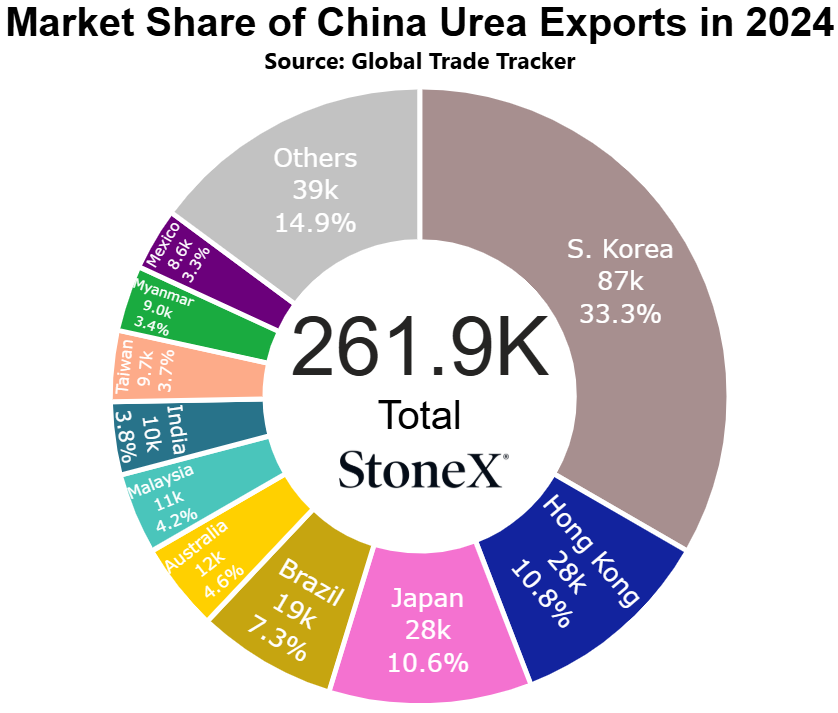
Price comparisons
Vs 30 days ago - -9% or approximately $43 lower
Vs 90 days ago - -4% or approximately $18 lower
Vs 6 months ago - 44% or approximately $123 higher
Vs 1 year ago - 48% or approximately $132 higher
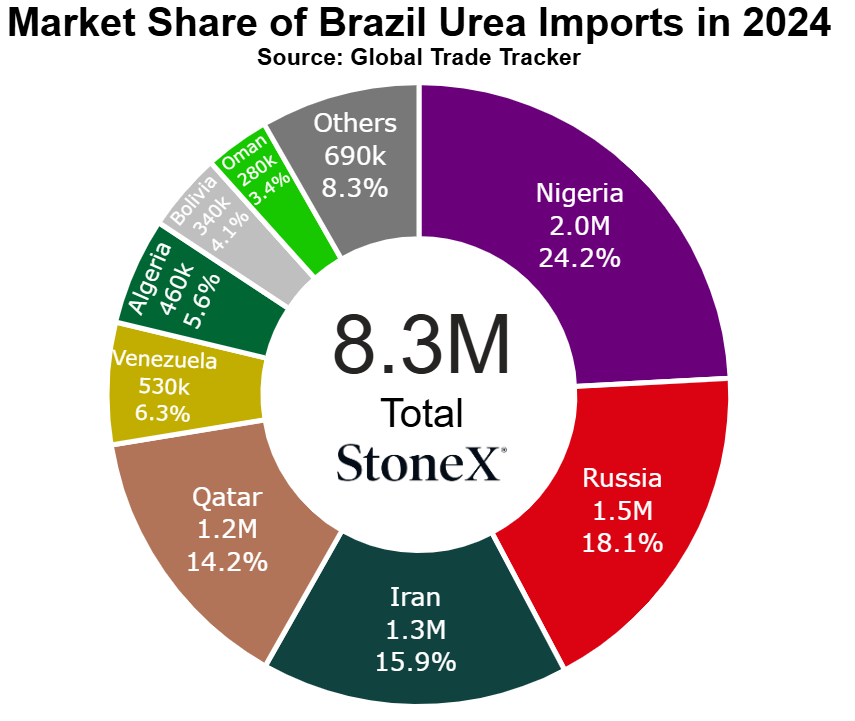
Brazil
Number 1 global importer in 2024
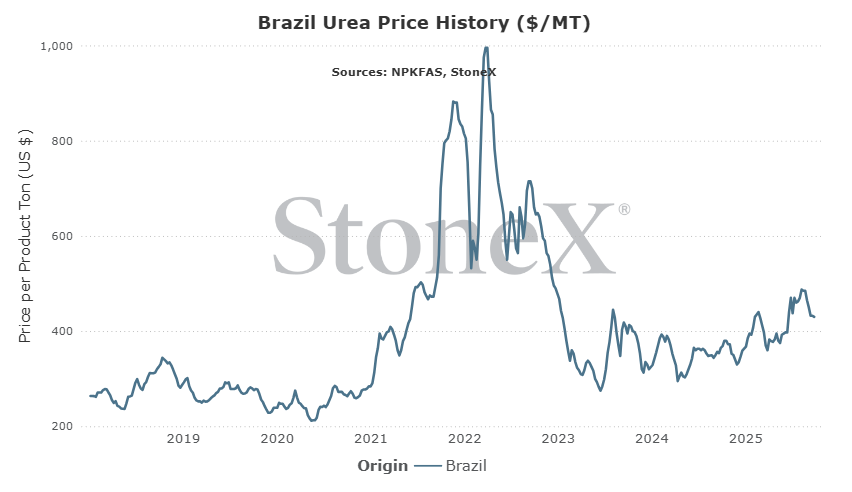
Price comparisons
Vs 30 days ago - -8% or approximately $35 lower
Vs 90 days ago - -2% or approximately $8 lower
Vs 6 months ago - 12% or approximately $48 higher
Vs 1 year ago - 48% or approximately $65 higher
Bull/Bear Factors
Because no market is ever guaranteed to go higher/lower, we try to consider the factors that can sway values so that we are able to act when they occur rather than react.
- Bullish Factors
- The world proceeds with sanctions against Russia, which lowers their export flows - yes, this is an incredibly low probability event. Russia has large urea demand allies/friends in India, Brazil, etc. These are countries that in the past have shown a willingness to skirt western sanctions to better their own positions. Unless the world push was severe, it is going to be very hard for this to happen...but not impossible, so I am including this. As you watch the news, keep an eye on any developments in this realm. If things start happening that starts to restrict Russia's export capacity, the world is going to hurt.
- China reverses course again, slowing/stopping their exports - FINALLY!!! Chinese urea exports are BACK...for now. WE continue to hear the expectation that exports will be limited to 4 to 4.25M tons for 2025. If they hit that number, it will be seen as a success by me. 4.25M is a huge jump over last years 262K ton total. However, 4.25M is far from guaranteed. We have seen the Chinese government change direction on a dime. If that happens with urea and they start to slow or stop their export flows, the global bulls are going to have a day.
- Sudden surge of N.A. demand due to government checks, Upper Miss River buying, wheat demand, etc. - while this doesn't seem likely, it is still possible. So far, feedback from the wheat country is indicating very little demand for fertilizer. The values just do not justify it so farmers are holding off. There are some that believe Upper Mississippi River areas must buy before winter closure or run the risk of fighting the market for rail. There is a chance that these markets that have been saying no suddenly come out of the woodwork and start buying. If that happened, the surge of demand would like press prices higher for at least a short time.
- Bearish Factors
- China continues with their much larger export flow - there is a part of the market that believes China could start to limit or stop their newfound urea export flows. On the flip side, there is a part of the market that believes China could extend the export window and allow even more tons to flow out. Domestic values are still solid for Chinese farmers. It appears that domestic supplies are still more than sufficient for demand. It is not outside the realm of possibilities to see them continue. If that happens, it adds a lot of much needed supply to the world.
- There is any semblance of peace between Russia and Ukraine - Russian exports of urea not only did not fall after the invasion, they have actually increased. From that POV, war or peace shouldn't matter because Russia is supplying more urea than before. However, there are still other issues that could come into play. Peace could remove any war-time premiums that might be put into place. Peace may return gas flows to Europe and allow their nitrogen production to restart. It may not be the immediate and direct healing that some would like to see, but there would be improvements.
- Crap farmer economics keep buyers out of the market for much longer than normal - the story of how poorly farmers are doing continues. Farming economics are not good today. I would use more descriptive terms but I do not want my compliance department telling me I shouldn't use that language for official StoneX publications!!!! There is a big chunk of the supply market that thinks urea demand will happen during normal times. That is not right. Not in today's environment. Farmers do not have money and so will likely drag their feet as long as they can before stepping in. It may not change overall demand but timing certainly matters.
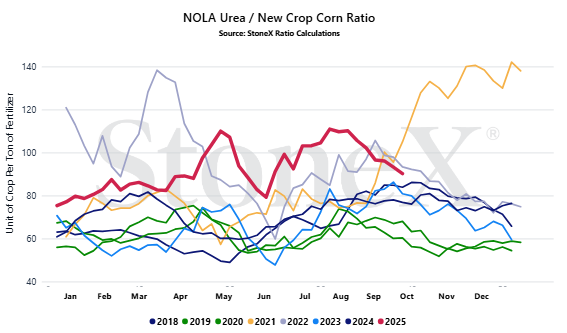
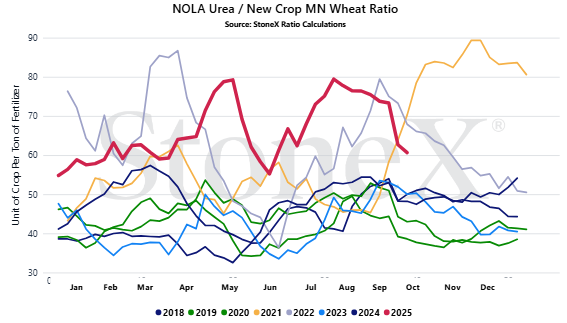
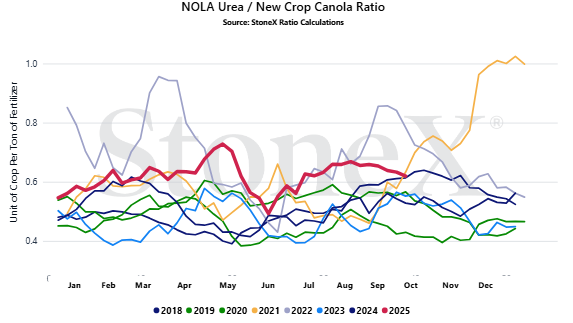
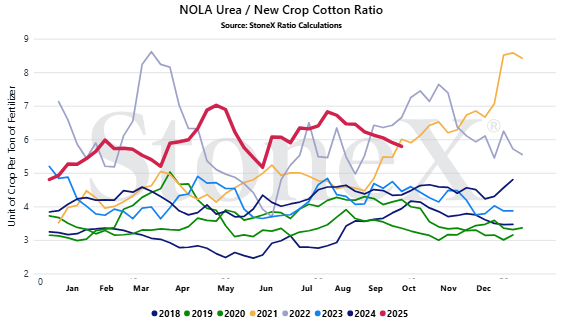
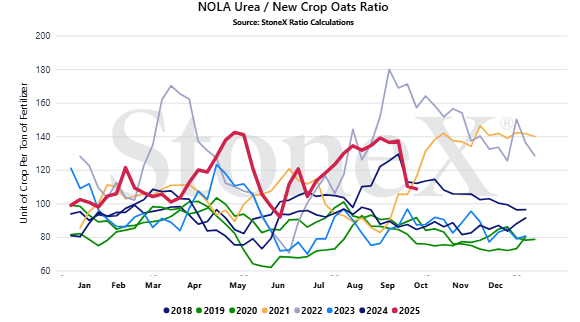
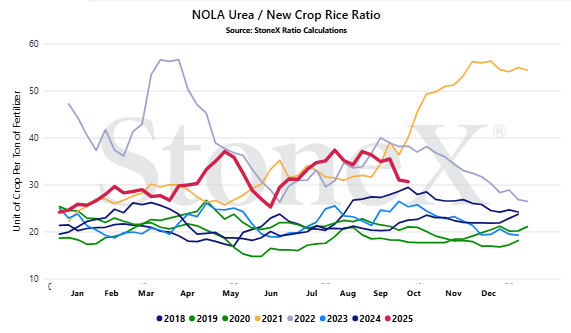
Where are the current urea/grain ratio values today
We believe that only looking at the flat price of either grains or fertilizer can be misleading:
- Only selling grain can hurt you if fertilizer prices rise substantially
- Only buying fertilizer can hurt you if grain prices fall
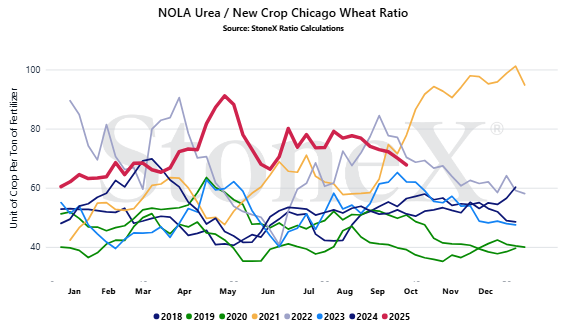
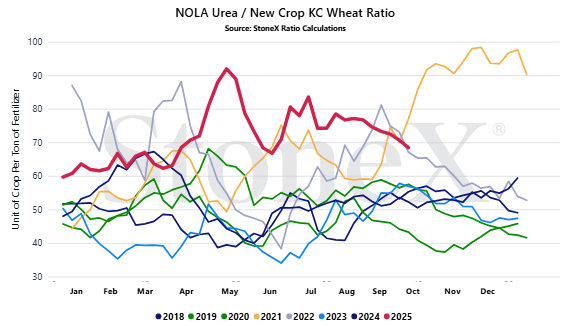
We look at the ratio "value" to get a better indication of where we are or how many bushels of X does it take to pay for 1 ton of fertilizer.
Would you rather:
- Spend 135 bushels to pay for 1 ton of urea
- Spend 55 bushels to pay for 1 ton of urea
When we compare the current ratio value against recent years, we start to see if we are high or low.
YOUR VALUES WILL LOOK DIFFERENT
This graph looks at the NOLA urea price vs the flat grain price. There are no logistics on either product. Your location will look different due to fertilizer logistical costs, grain basis, etc.
- Josh Linville’s Focal Points
- Global sanctions (or lack of) on Russia - this has become my new scary focal point. I will admit, I think the chances that the U.S. leads the way on sanctions against Russia are fairly low. We just seem almost unwilling to do so. However, it isn't even a question of if when it comes to urea. If just western countries adopt sanctions against Russia, I think their urea exports will be fine. We should see a shift in destinations, but they will find homes. The biggest fear is if western countries are successful in starting to slow and/or stop Russian urea exports. Very low likelihood, very high impact. This war between Russia and Ukraine has been going for 3.5 years and patience is wearing thing...
- China's continued export programs - the most fortunate story of the last couple months has been the return of Chinese urea exports. After being largely missing for all of 2024 and the 1st half of 2025, their exports are improving markedly. That is helping to put a lot more supply in the world than was previously expected. However, the questions remains of how much and for how long. Some believe exports will start being restricted within the next month which puts us back in the same cycle. Others believe these export programs will continue thru 2025 and perhaps into 2026. What they do or do not do will have a lot of impact on global urea markets.
- Any possibility of peace between Russia/Ukraine - back to Russia, but from a low probability peace perspective. In the low chance that peace can be found (weirder things have happened), this could be a hugely bearish event for global urea. It removes war-time premiums that are baked in. It returns normal/efficient global trade routes which helps lower price ideas. It could even go so far as to allow European production to get back to normal. It is a very low chance, but I'm tired of only talking negative. I need something positive to look forward to.
StoneX Ratio Calculation
The ratio calculation is derived from Bloomberg historical grains values as well as fertilizer values from StoneX, NPKFAS, and Argus.
The calculation is simply dividing the fertilizer price by each grain price.
All data was sourced from StoneX unless otherwise noted.
This material should be construed as the solicitation of an account, order, and/or services and represents the opinions and viewpoints of the individual authors or presenters. It does not constitute an individualized recommendation or take into account the particular trading objectives, financial situations, or needs of individual customers.
The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.
The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.
References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.
StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.
R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.
StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.
This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.
StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).
SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.
StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.
StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.
StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.
StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.
Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.
The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.
© 2026 StoneX Group Inc. All Rights Reserved.