StoneX logo

Perspective: Mid-Day Commentary for September 24

By: Mike Castle, Market Intelligence - Fertilizer Analyst

September 24 – Crude oil prices dropped and the major stock indexes jumped following Reuters reporting the U.S. and Iran exploring a phased path toward reopening the Strait of Hormuz in exchange for the U.S. easing its economic blockade on Iran. We warned coming into the week that it was likely to be a volatile, headline-driven one amid the various diplomatic pushes happening all at once in New York, and today’s trade is a perfect reminder of that. While the renewed signs of diplomacy between the U.S. and Iran are certainly a notable development, I would again emphasize caution regarding how much can realistically be accomplished this week, particularly with IRGC-linked figures continuing to issue renewed threats of escalation at the same time. Reuters' reporting suggests both sides are actively discussing potential frameworks, but significant obstacles remain and neither appears willing to relinquish leverage without corresponding concessions. Still, even progress toward a partial or phased reopening could improve market confidence that an eventual resolution may be coming into view. The VIX has fallen in response, now hovering around 15.5 after touching a fresh high since last Wednesday at 16.57 earlier in the session. The dollar remains in the green, holding near 101.22 at the time of writing as it remains near a two-month high. Treasury yields have had a volatile session as well, with 2-year yields now slightly lower into midday, trading at 4.88%, 10-year yields remain elevated as they trade near 5.13%, as do 30-year yields as they trade near 5.435%. The ags have lost steam into midday, with the grains and oilseeds now in the red across the board, save for soybean meal clinging to small gains, while the livestock sector is mixed with feeder cattle pushing higher.

August new home sales blew past expectations this morning, coming in at a seasonally adjusted annualized rate of 684k, marking the highest sales pace of any month in 2026 thus far. This was sharply above the average analyst estimate of 615k and above even the highest estimate of 660k—furthermore, July was revised sharply higher, now pegged at 643k versus the 607k previously reported. Regionally speaking, this impressive strength was driven by a massive 84.9% month-on-month uptick in the Midwest and 6.9% increase in the South more than offsetting the 15.2% decline seen in the West and 36.1% decline in the Northeast. This is a significantly stronger result than expected, but the bigger concern remains what happens moving forward as the steady rise in mortgage rates weighs on prospective demand. That makes the strength in these backward-looking sales figures somewhat less informative about the months ahead, although the sharp upward revision to July does establish a considerably stronger baseline than previously thought.

The outlook becomes less constructive when shifting from completed sales to the pipeline for future construction, with August building permits falling 2.1% month-on-month to 1.403M, signaling a slowdown in housing activity moving forward, though it’s worth noting that was still slightly above estimates. Surging treasury yields are weighing on that forward-looking sentiment as well, particularly the 10-year, which serves as the primary benchmark for 30-year mortgage rates and therefore has an outsized influence on housing affordability and prospective buyer demand. 10-year treasury yields have risen to another fresh high since 2007 today just below 5.17%, keeping this concern in focus.

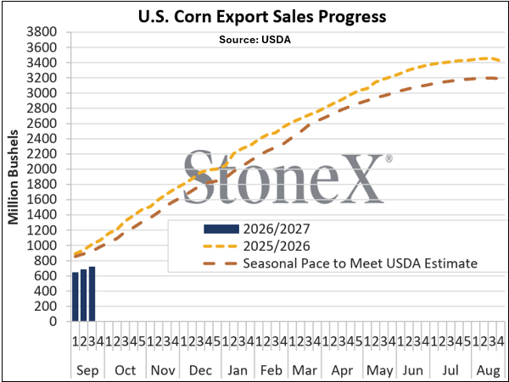
This morning’s weekly USDA Export Sales report was pretty ugly for the wider grains and oilseeds, taking a bit of wind out of the proverbial sails into midday, but the bigger focus remains on the results of today’s Trump/Xi meeting. Weekly corn sales for the week ended September 17 were reported at 33.0 million bushels, near the low-end of expectations, with the cumulative total of 718 million bushels slipping further behind last year’s pace as it now trails by 29.2%. Part of this may well continue to reflect prospective buyers staying on the sidelines amid the recent surge in prices, but it will be important to continue monitoring our realized sales pace in order to reach USDA’s current 3.275-billion-bushel export target. Weekly all wheat sales fell to 9.8 million bushels, below the bottom-end estimate by just over 3 million. Cumulative 2026/27 wheat sales now sit at 344 million bushels, now trailing last year by 31.3% and maintaining the slowest pace in three years. The question continues to be whether more export demand gets shifted to the U.S. in the year ahead given the ongoing disruptions in the Black Sea and reported quality issues on the Canadian Prairies, both clearly still risks today, but the market will eventually need to see more hard evidence of this coming to fruition.

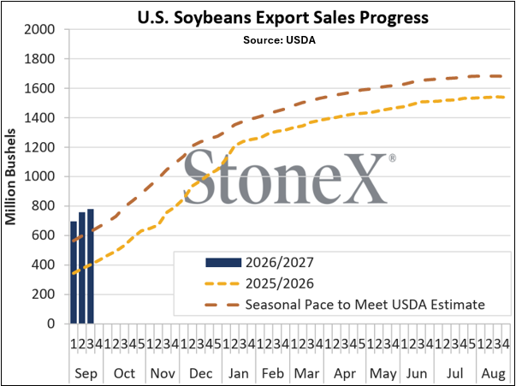
Weekly soybean export sales fell sharply to 21.4 million bushels in the week ended September 17, coming in less than half of the lowest estimate of 55.1 million and marking the weakest sales for the comparable week since 2022 and the third lowest for the week of the last 30 years. China was by far the featured destination again, accounting for over half of the total, but still representing their smallest week of purchases since early July. It’s worth noting that this was likely influenced by buyers shifting into wait-and-see mode ahead of this week’s summit but also puts additional emphasis on today’s meeting between Trump and Xi. Unlike corn and wheat, however, cumulative 2026/27 soybean export sales of 779 million bushels are very robust at this point, remaining nearly double last year and maintaining the strongest seasonal pace in four years.

image 138040

image 138041

  • Grains & Oilseeds

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for October 2

October 2 – The bad news is good news trade is back in full effect, with stock futures surging to point to a notably stronger open following a significantly worse than expected tranche of U.S. labor market data in this morning’s September Nonfarm Payrolls report which we’ll dive into in more depth below. The VIX has broken sharply lower in response, now hovering around 15.5, its lowest level since last Friday. The dollar is following suit as this softens Fed rate expectations, now down 0.2% on the day to trade near 101.86 at the time of writing. Treasury yields are joining in on the drop as well, with the 2-year at 4.74%, 10-year at 5.184%, and 30-year at 5.57%. Crude oil is notably lower to start the day, with nearby WTI down 3.9% to trade near $89.30 and nearby Brent down 3.1% to trade near $99.10. Meanwhile, the ags are largely mixed to start the session, with parts of the wheat complex narrowly in the green at the break while corn and soybeans hang in the red.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

El Nino's Timing, Not Its Strength, Decides Which Harvests Feel It

A super El Nino is drawing headlines for its strength, but its timing decides which harvests feel it. From Australian wheat to Brazilian soybeans and Northern European wheat quality, the same weather can help one crop and hurt another.

Editorial Team
Editorial Team
  • Grains & Oilseeds

Perspective: Mid-Day Commentary for October 1

October 1 – Stocks have fallen through the session to hang in the red at midday while the VIX pushes notably higher to sit above 17.5, now a two-week high. The dollar continues its surge higher as well, hovering at a nearly one-and-a-half-year high near the 101.9 level. Treasury yields are falling most sharply at the front-end of the curve, with 2-year yields back down to 4.815%, while long-term yields have fallen from their morning highs to now trade lower on the day, as 10-year yields sit just above 5.27% and 30-year yields sit just above 5.63% at the time of writing. Crude oil has had a volatile session but remains higher at midday, with nearby WTI up 2.4% to trade near $92.50 and nearby Brent up a sharper 3.7% to trade near $101.65. The ags are mostly lower at midday, led down by the soy complex, with soybeans down double digits at the time of writing.

Mike Castle
Mike Castle
  • Grains & Oilseeds
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.