StoneX logo

Perspective: Mid-Day Commentary for October 22

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

October 22 – The tech sector remains in an ugly selloff at midday, leading the Nasdaq to show a 2.1% loss at the time of writing, while the S&P 500 is down 1.0%, but the Dow Jones is actually slightly above unchanged. The VIX remains elevated as well amid the combined tech sector and Middle East geopolitical escalatory fears, up roughly 10% on the day to sit near 18.35. The dollar has traded both sides of unchanged today but sits just slightly below it at the time of writing, hovering near the 101.65 level. Treasury yields are sharply lower at midday, with 2-year yields off 14-basis points to trade at 4.684%, 10-year yields off near 16-basis points to break back below the 5% mark for the first time in a month, and 30-year yields are off 12-basis points to sit at 5.316%. Crude oil prices are off their highs but still in the green amid escalating rhetoric between the U.S./Israel and Iran, as well as the ongoing fighting between the Saudis and Houthis, with nearby WTI up 1.0% to trade near $98.70 and nearby Brent up 2.8% to trade near $111.90 at the time of writing. The ags are largely mixed at midday, with soybeans finding strength amid red-hot U.S. export demand amid huge Chinese purchases, while much of the remaining grains, oilseeds, and livestock sector hangs in the red.

The Kansas City Fed’s Manufacturing Survey showed cooling but still robust conditions for the sector, with the Composite Index falling to 11 in October from the 14 seen in September—that is obviously a month-on-month decline, but September’s print was the highest since July 2022. Similarly, the Manufacturing Production Index took a step back to 16 in October from 20 in September, but that was the highest seen since April 2022. Overall, the manufacturing sector in the Kansas City Fed district remains comfortably in expansionary territory, but from a Fed perspective, the bigger focus is likely on the ongoing cost pressures. The Prices Paid subindex rose to 70 in October, up another 2 points month-on-month and marking the highest level of input prices since June 2022. This is yet another sign of the ongoing build-up of inflationary pressures increasingly held at the producer level—watch for that pass-through to the consumer level in the months ahead.

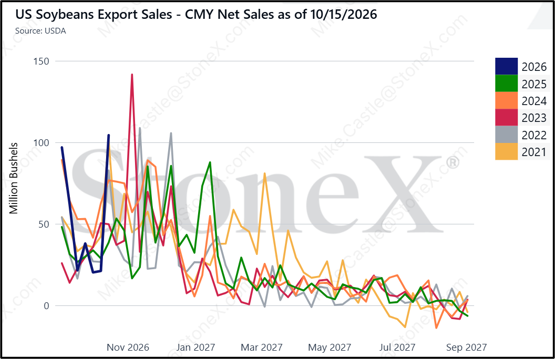
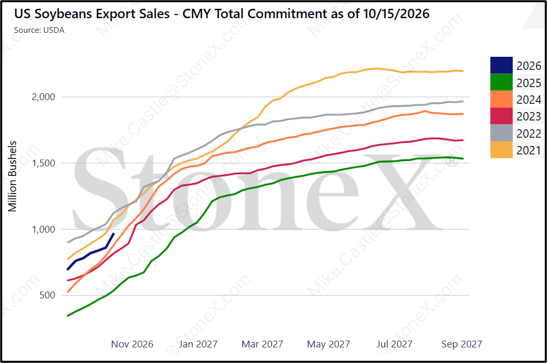
Weekly corn and soybean export sales both came in strong at 60.1 and 104.4 million bushels, respectively, as buyers stepped in to take advantage of the break lower in prices. Today’s data for the week ending October 15 was of particular interest given the timing, as it captured the demand response to the post-October WASDE drop in prices following its release on October 9. On the corn side, this was a six-week high, surpassing the top-end analyst estimate by 1 million bushels, with Mexico being the featured destination. 2026/27 corn sales have continued to fall further behind last year’s pace, with the cumulative 874 million bushels now 33.8% behind last year at this time and marking their slowest since 2023. This continues to raise concerns regarding the ability to reach USDA’s now higher 3.300-billion-bushel export target, but today’s print marks a step in the right direction; we’ll need to see how that progress continues in the weeks ahead. On the soybean side, however, export sales remain red hot relative to recent years amid the resurgence of Chinese buying. This week’s 104.4 million bushels represent the largest print for any week since November 2023, with another 202k MT (7.42 million bushels) of daily flash soybean sales to China announced this morning, the seventh consecutive day of reported flash sales from USDA. China accounted for the vast majority of the week’s sales, with the 80 million bushels also representing the biggest week since November 2023, highlighting the ongoing strength. Cumulative 2026/27 soybean sales have reached 963 million bushels, up 80.7% year-over-year and maintaining the hottest pace seen since 2022.

Weekly wheat export sales were disappointing at 8.8 million bushels, however, below the low-end analyst estimate and marking a six-week low. Cumulative wheat export sales in 2026/27 now total 392 million bushels, lagging last year’s pace by 32.5% and officially falling behind 2023/24 this week to now sit at the slowest pace seen in at least the last 14 years. The ongoing effective closure of the Black Sea to Russian/Ukrainian wheat shipments keeps present the question of if/when we see additional export demand shifted to the U.S., but the market needs to see actual progress on that side. In that vein, it’s worth noting that the Rosario Grains Exchange raised their estimate for 2026/27 Argentina wheat production to 23.8 million metric tons, up 2.8 million from their previous estimate on higher-than-expected initial yields. Argentina looks poised to be one of the primary origins stepping in to fill the gap, but keep an eye on the potential for quality issues amid their cold, wet stretch late in the season.  

image 139435

image 139436

  • Grains & Oilseeds

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.
Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for October 23

October 23 – The tech heavy Nasdaq saw its worst day since June yesterday, closing 2.9% lower, with concerns regarding the sustainability of the ongoing AI buildout in the backdrop of rising borrowing costs and increasing sovereign debt driving investors into safe havens, as evidenced by the surge in buying in the bond markets. Stock futures are pointing to a lower open again today, though Nasdaq futures are showing the smallest losses among the major indexes, a potential sign of an easing of selling pressure in the tech sector. The VIX is up 6% to start the day, trading just below 20.2 at the time of writing, hovering near its highest level since last Friday. The dollar is looking at a quiet start to the day after a largely quiet week, sitting just above unchanged near 101.68. Treasury yields are modestly higher this morning after falling notably this week, with 2-year yields at 4.66%, 10-year yields at 4.97%, and 30-year yields just above 5.29%. Crude oil prices are on the rise as the market rebuilds geopolitical risk premium amid escalatory rhetoric from the U.S. / Israel and Iran, raising fears of renewed and potentially even more intense back-and-forth strikes. Nearby WTI is up 2.5% to start the day, carving out a fresh five-week high of $101.60 at the time of writing, while nearby Brent is up another 1.35% on the day to trade near $114.70, nearing a six-month high. Meanwhile, the ags are looking at a quietly mixed open.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Grain & Oilseeds with Craig Turner - Premium Producer | Export Sales Bullish Soybeans, Bearish Corn

Export Sales Bullish Soybeans, Bearish Corn

Craig Turner
Craig Turner
  • Grains & Oilseeds

Perspective: Mid-Day Commentary for October 22

October 22 – The tech sector remains in an ugly selloff at midday, leading the Nasdaq to show a 2.1% loss at the time of writing, while the S&P 500 is down 1.0%, but the Dow Jones is actually slightly above unchanged. The VIX remains elevated as well amid the combined tech sector and Middle East geopolitical escalatory fears, up roughly 10% on the day to sit near 18.35. The dollar has traded both sides of unchanged today but sits just slightly below it at the time of writing, hovering near the 101.65 level. Treasury yields are sharply lower at midday, with 2-year yields off 14-basis points to trade at 4.684%, 10-year yields off near 16-basis points to break back below the 5% mark for the first time in a month, and 30-year yields are off 12-basis points to sit at 5.316%. Crude oil prices are off their highs but still in the green amid escalating rhetoric between the U.S./Israel and Iran, as well as the ongoing fighting between the Saudis and Houthis, with nearby WTI up 1.0% to trade near $98.70 and nearby Brent up 2.8% to trade near $111.90 at the time of writing. The ags are largely mixed at midday, with soybeans finding strength amid red-hot U.S. export demand amid huge Chinese purchases, while much of the remaining grains, oilseeds, and livestock sector hangs in the red.

Mike Castle
Mike Castle
  • Grains & Oilseeds
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bilateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and track record are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform to “boots-on-the-ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.