StoneX logo

Precious Metals StoneX Bullion weekly round-up 092126; fed hikes, private credit stress

By: Rhona O'Connell, Head of Market Analysis

Banner Precious Metals

Rhona O'Connell, Head of Market Analysis, EMEA & Asia

 Tel: +44 203 580 6115 / mobile +44 7384 833897

21st September 2026

The Fed hiked the fed funds target rate by 25 points, as expected; gold took it all in its stride; still seeking direction and caught between key moving averages


As we noted a couple of weeks ago, the World Gold Council has put central bank net buying at a record 289t in the second quarter, roughly five times that of the first, and the People's Bank of China had extended its run of consecutive monthly reported additions to nineteen months as of May. Meanwhile the news that the Netherlands has shifted 56t of gold from the States into London, reportedly on fears of asset freezing in the US (and following French selling US-located holdings and buying in Europe), has caught the headlines.  This was done via an effective location swap, selling New York and buying London, rather than physically shipping metal.

The key points of attention are still the Gulf and the Fed.  The latter is rather clearer than the former. 

The Fed hike was the first since July 2023, at the end of the tightening in the face of post-COVID inflation.  The vote was unanimous. Officials also signalled another hike likely this year and adopted a "higher for longer" message via the dot plot – to which Chair Warsh, as in the June meeting, did not contribute.

Gold; immediate support $4,285.  There is a body of support between $4,085 and $4,203
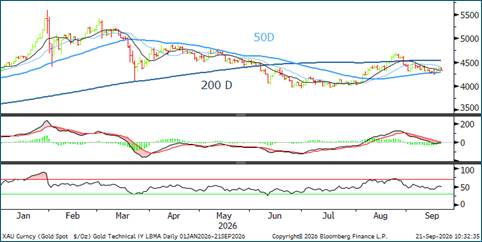
image-20260921125219-1 

Silver’s immediate support $62; medium-term body of support is between $54.80 and $60.15
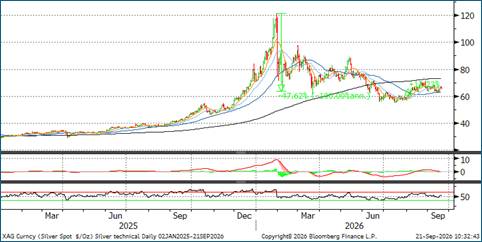
image-20260921125219-2

Source; Bloomberg, StoneX

Gold's reaction was muted, partly because the hike was already priced in, while bond yields eased slightly, which seems counter-intuitive, but essentially reflected the feeling that peak inflation fears were softening.

Meanwhile the Saudi Arabian pipeline had been closed on 11th September after a drone attack thought to come from  Iranian-backed militias, removing a route that takes crude to the Red Sea rather than through the Strait of Hormuz. This had boosted oil and, with it, inflation expectations that had been supporting gold. Restoration has been quicker than expected, with roughly half the capacity of its damaged East-West pipeline coming back within days, and full operations are now expected to be up and running in six weeks. Brent crude fell for a third consecutive session and this outweighed fears of a broader escalation in the Middle East.  This, combined with the suggestion that peak inflation fears were abating, helped to give gold a boost on Friday as Brent slipped towards $100, but we are still in a holding pattern, with President Trump to meet Chinese Premier Xi this week and there is also the possibility of high level talks between US and Iranian officials this week, set against the backdrop of the UN General Assembly in New York.

Note the continued correlation between Brent and the ten-year yield as they both respond to Gulf developments
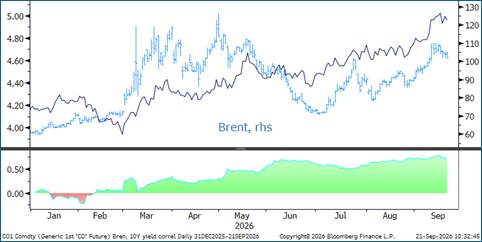
image-20260921125219-3

Source: Bloomberg, StoneX

Silver activity was similar to that of gold, although the volatility was higher.- but not by much.  Ordinarily silver’s volatility is between 2.0 and 2.5 times that of gold; this time gold traded a 3% range and silver, 5% so on that historical basis its action was relatively contained.  The key difference was the slippage in the face of the Fed’s hike, suggesting that silver was looking at its industrial characteristics (remember 70% of pre-investment fabrication activity is industrial) as it fell from $64.5 to $62.3; the rebound on Friday took silver up to $67.1 before some profit taking set in.

Key long bond yields, long-term and the 5Y-30Y spread; yield curve continues to ease
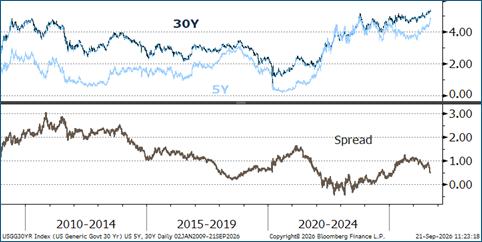
image-20260921125219-4

Source: Bloomberg, StoneX

The Private Credit sector

We noted a fortnight ago that “we continue to keep an eye on the private credit sector, which is catching increasing interest from the press.  The FT has noted that after the global financial crisis, authorities clamped down on “duration mismatch” (banks borrowing short term and lending long.  This, incidentally, is effectively what the US Treasury is doing in its expanded buyback programmes that got underway on 9th September for eight weeks).  The FT points out that some of that activity shifted into the private banking sector and the way that this has evolved has brought some life assurance companies onto the scene and suggests that the continued geopolitical issues and persistent inflation mean that a rise in credit defaults may result. The most recent development is the emergency funding of A$3.4Bn (US$2.5Bn) for the insolvent Australian builder Bathla, which has put pressure on Australian real estate and private credit markets”. 

Since then the fed funds rate hike has increased the pressure on some stressed elements in the sector, as most private credit is floating rate and so, while reaping the rewards in terms of interest earnings, borrowing costs also rise, and many of these companies are leveraged, which adds to the risk.  Fitch has now raised its Private Credit Default Rate to a record 6.3% for the twelve months ended August, while several large funds are capping redemptions at 5%, against redemption requests ranging from 11% to 16%.

Inventories, ETFs

Gold COMEX registered and eligible stocks together edged up by 1.1t, or 0.13% over the week, to 851.7t as at 18th September, while the ETPs did rather more of the running, adding 11.5t over the same seven days to close at 3,122.5t, a gain of 0.37%. That is a quietly constructive picture, although it sits a little awkwardly against the positioning data, where managed money trimmed its net long by 5.8t to 414.0t in the week to 15th September; the reduction was not a fresh bearish bet, though, since the gross short was cut by 4.8t to 28.9t at the same time as the gross long came down by 10.6t, which reads as lightening rather than turning.

Silver told a busier story. COMEX stocks fell by 222.7t, or 2.12%, to 10,266.7t, with the drawdown running steadily through the week rather than arriving in a single day, and the ETPs lost 126.8t, or 0.51%, to 24,850.2t. Managed money was the sharpest mover of the three, cutting its net long by 201.2t, some 8.6%, to 2,146.8t as at 15th September, and here the gross figures are less benign than in gold, the long shedding 151.6t while the short was built up by 49.6t.  Bear in mind that these numbers date from last Tuesday and thus precede the FOMC meeting conclusion.

Gold COMEX positioning, Money Managers (t)
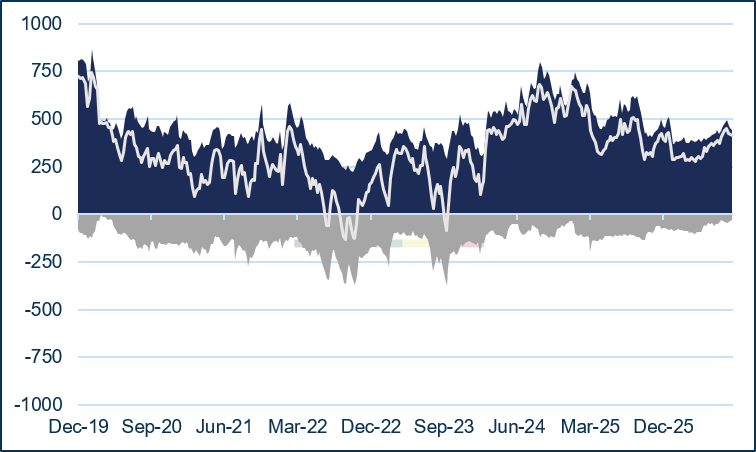
image 137754


Source: CFTC/Bloomberg, StoneX                                                          

Declining open interest in both gold and silver on COMEX

COMEX Managed Money Gold Longs as % of 1st continuation Open Interest
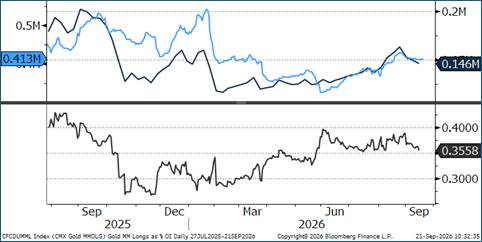
image-20260921125219-6 

Source: Bloomberg, StoneX

COMEX Managed Money Silver Positioning (t)
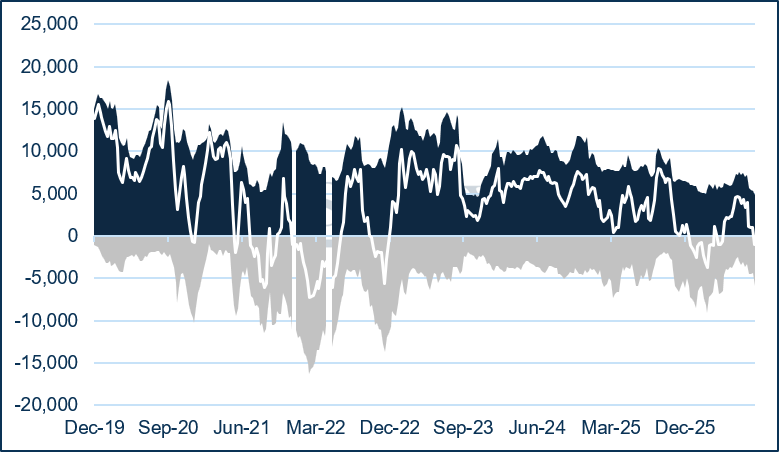
image 137755

Source: CFTC/Bloomberg, StoneX


COMEX Managed Money Silver Longs as % of 1st continuation Open Interest
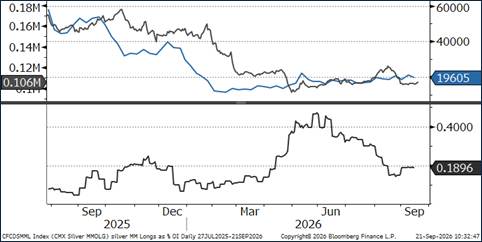
image-20260921125219-8 

        Source: Bloomberg, StoneX                                                                

The S&P, gold and copper; S&P/gold correlation steady at 0.26 while S&P:Cu correlation is easing; latest at 0.50
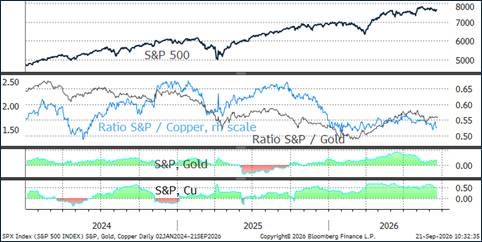
image-20260921125219-9

Gold, silver and copper correlations; silver-gold 0.81 (lower); silver-copper, 0.43 (easier)
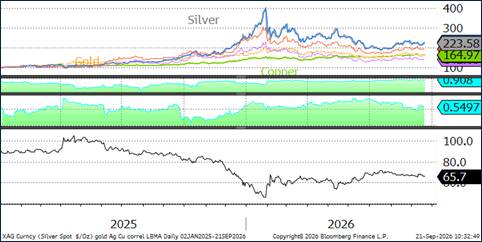
image-20260921125219-10

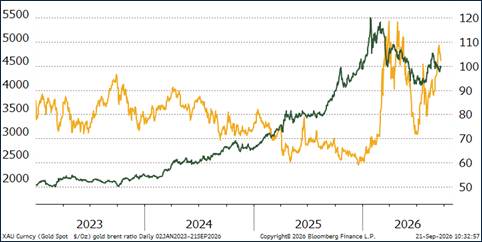
Gold:Brent ratio

image-20260921125219-11


Gold in key local currencies. Year-to-date, up 6.8% in Rupee terms, up 1.4 in US$
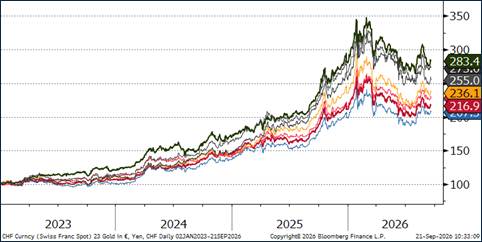
image-20260921125219-12

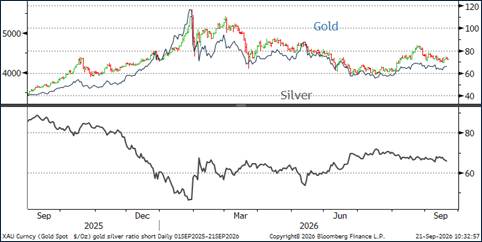
Gold:silver ratio

image-20260921125219-13 

Source for above charts: Bloomberg, StoneX

 21 September 2026Previous week% changeYear-to-dateRange Jan 2024 onwards Range as %
     MinMax 
Gold (pm LBMA price)4,365.244,299.641.53%0.76%3,976.505,417.2136.23%
Silver (LBMA price)58.6662.05-5.47%-23.41%57.42116.70103.25%
Platinum (pm LBMA price)1,629.941,632.90-0.18%-28.41%1,552.522,054.1232.31%
Palladium (pm LBMA price)1,271.771,271.280.04%-25.94%1,171.572,054.1275.33%
S&P 5007,650.507,656.98-0.08%11.76%4,688.687,798.9966.34%
$:€1.14861.1599-0.97%-1.99%1.02441.204117.54%

Source: Bloomberg, StoneX


  • Precious Metals

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bilateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and track record are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform to “boots-on-the-ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.