Precious Metals StoneX Bullion weekly round-up 101926; US Inflation higher-for-longer?
Renewed Gulf issues boosting yields, precious on the slippage, technicals deteriorating
Rhona O'Connell
- Precious Metals
Head of Market Analysis
Weekly round-up for StoneX Bullion
Rhona O'Connell, Head of Market Analysis, EMEA & Asia
Tel: +44 203 580 6115 / mobile +44 7384 833897
19th October 2026
Opinion is largely unchanged
There is still a body of support for gold stemming from continued press comments about official sector net purchases (which in our view is more significant for the message that it sends to the markets about risk-management than the actual tonnage) and this is helping to put a floor under the price.
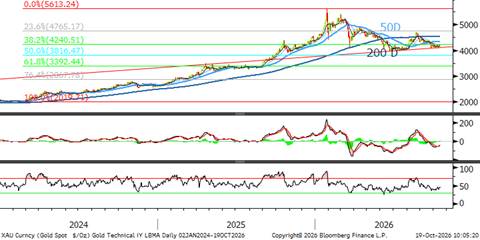
The negative reaction to the US’ aggressive inflation numbers last week, along with higher import prices for September, suggest that some of the positive sentiment may become eroded. The technical construction is also largely negative. The spot price tested and bounced off its upward trend line at $4,114 and the key moving averages are all above the spot price, ranging from $4,151 (10D) to $4,522 (200D). There is a body of congestion between $3,959 and $4,117 then the next technical line of support comes from the Fibonacci 50% retracement of the run from February 2024 to the 29th January peak of $5,613; i.e. at $3,816.
Meanwhile as we noted last week, the array of professional fund managers who are calling gold higher suggests that much of their investment may have been done already – after all, most shrewd investors would establish their positions in any asset before publicly expressing clear opinions. The banks. of course, are a different matter as their role in the market is not the same as long-term investment managers. So absent a Black Swan (and any more Black Swans would be unwelcome), we still believe that the medium-term risk lies to the downside.
That said, Festival buying is picking up in India with local prices posting premia to London. Diwali starts on 8th November.
Gold; immediate support $4,114. Resistance $4,151 - $4,522
Source; Bloomberg, StoneX
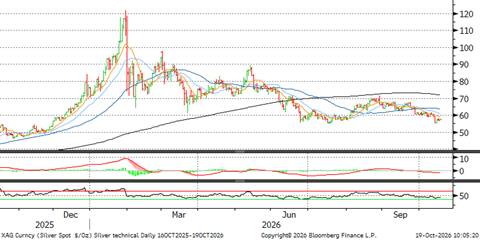
Silver remains on the defensive, substantially underperforming gold towards the end of last week, as the market continues to fret over potential threats to industrial offtake – not just the much-mentioned (temporary) over supply of solar cells, but also the pressure on the high-tech stocks in the US at least, and ahead of the earnings season, which starts this week with Meta reporting on the 21st; Microsoft and Alphabet report on the 28th and Amazon on the 29th.
We are expecting silver to throw off a surplus equivalent to roughly seven weeks’ global fabrication demand this year. If liquidation from ETPs is taken into account then that excess rises to roughly eleven weeks’ demand.
Silver resistance from $58.5 to $63.4 and then at $72.0
Source; Bloomberg, StoneX
Précis of last week’s note on US inflation numbers
As noted in the Fed’s Beige Book Survey, commercial firms have, until now at least, been reluctant to pass price increases through to the consumer given the latter’s resistance and lack of confidence. But if PPI continues to run substantially higher than CPI, there may come a point where commercial entities are forced to pass it through or else absorb much reduced margins. Where is the tipping point?
For the full analysis, please follow this link
Recent background
The Federal Open Market Committee is now in blackout ahead of the meeting scheduled for next Tuesday and Wednesday 27-28th October. This gave added emphasis to the fireside chat last week between Kevin Warsh the Managing Director of the IMF at the IMF-World Bank annual meetings. The essence was that the US economy looks resilient, inflation still needs to be brought under control, while, as is to be expected, he would give no hint about the Fed’s next rate move. He was positive about US momentum, pointing to a widening investment surge, including spending beyond AI, as a source of economic tailwinds. He also considered that the global economy had held up better than he would have expected amid geopolitical shocks and tighter monetary policy.
He reiterated that the Fed would deliver price stability and said it had “removed a dose of accommodation” with September’s rate increase. He described rising prices as a shared challenge among central banks, and their coordinated tightening as leaving “no free riders.” But he declined to say whether the Fed would raise rates again in October or December: “I don’t prejudge meetings.” Meanwhile as far as recent data were concerned, US inflation weas higher than expected (see below) and payroll growth has eased; this is broadly in line with Fed expectations.
He called AI’s arrival probably the most consequential change to the US and global economy in his lifetime. His distinction was that AI investment is boosting demand now, before its productivity gains lift supply; that can add to inflation in the short run. Over time, he expects AI to raise productivity and wealth, though he warned the transition will be “very bumpy,” with employment effects over the next 12–18 months uncertain. The Fed’s productivity and jobs task force is due to hold a field hearing in the San Francisco Bay Area on 16 November to examine AI’s effects on productivity and employment.
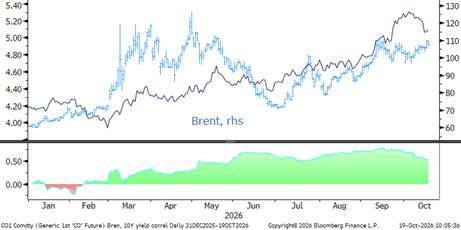
The correlation between Brent and the 10Y yield is still high, but easing
Source; Bloomberg, StoneX
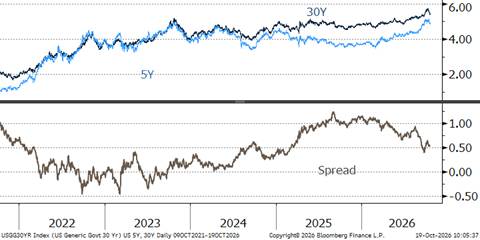
Key long bond yields, long-term and the 5Y-30Y spread; yield curve continues to flatten
Source for both charts: Bloomberg, StoneX
Inventories, ETFs
COMEX gold stocks fell for a seventh consecutive session, easing by 1.6t, or 0.2%, in the week to 16th October to 729t, their lowest since 29th September; both dates lie after the closure of the Gold Enhanced Delivery Contract, so the comparison is like-for-like.
The ETFs added 2.1t, or 0.1%, to 3,147t.
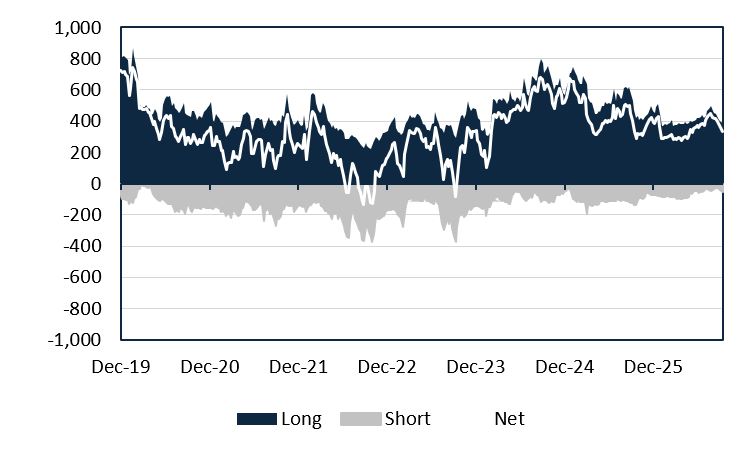
Managed money cut its net long for a seventh consecutive week, by 12.1t, or 3.5%, to 333t as of 13th October, the lowest since 9th June, taking the reduction since the 450t peak on 25th August to 117t. Long liquidation of 7.3t was accompanied by 4.8t of fresh shorts, which lifted the gross short to 54.9t, its highest since 7th July.
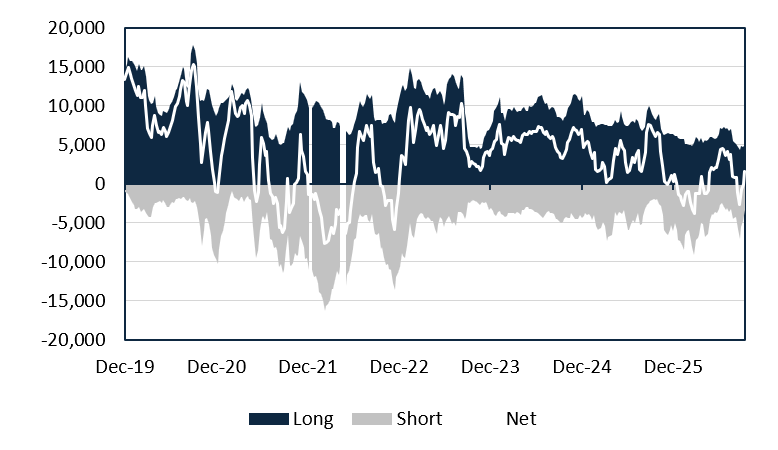
Silver positioning deteriorated sharply again: the net long fell for a third week, by 297t, or 25%, to 874t, the lowest since 10th February, as 195t of new shorts took the gross short to 1,584t, the highest since 27th January, alongside 102t of long liquidation. The physical market moved the other way.
COMEX stocks recovered from 10,260t on 12th October to end the week 60t, or 0.6%, higher at 10,381t, and the ETFs gained 113t, or 0.5%, to 25,057t, their highest since 25th March, with 159t added on 16th October alone, the largest daily inflow since 22nd September.
Gold COMEX positioning, Money Managers (t)

Source: CFTC/Bloomberg, StoneX
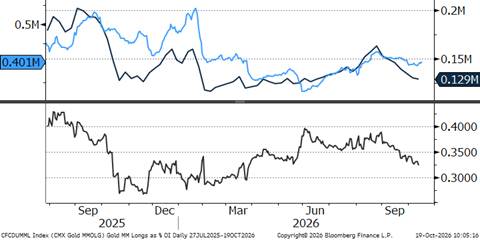
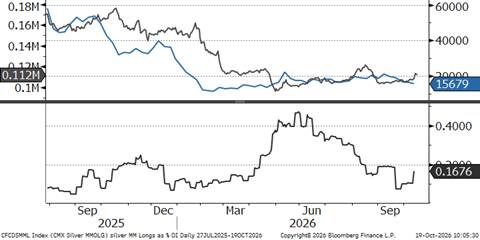
Declining open interest in both gold and silver on COMEX
COMEX Managed Money Gold Longs as % of 1st continuation Open Interest
Source: Bloomberg, StoneX
COMEX Managed Money Silver Positioning (t)

Source: CFTC/Bloomberg, StoneX
COMEX Managed Money Silver Longs as % of 1st continuation Open Interest
Source: Bloomberg, StoneX
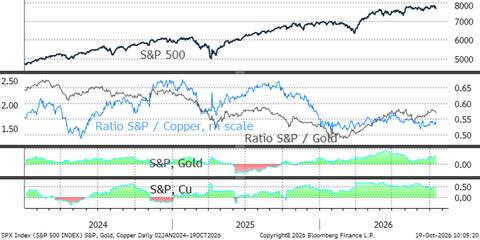
The S&P, gold and copper; S&P/gold correlation steady at 0.51 while S&P:Cu correlation is also steady; latest at 0.41
Source: Bloomberg, StoneX
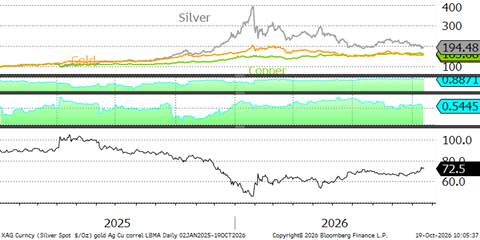
Gold, silver and copper correlations; silver-gold a lot easier at 0.73 silver-copper, down to 0.31 as silver comes under pressure
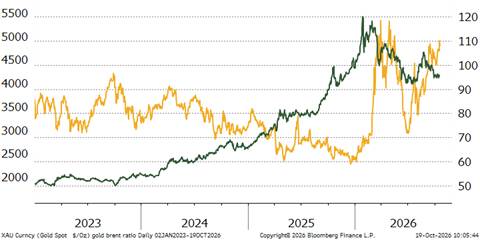
Gold:Brent ratio
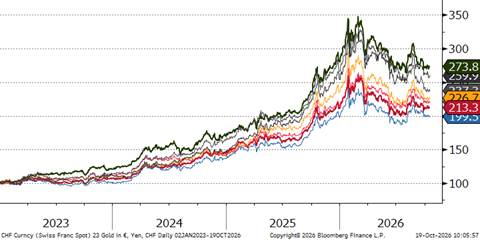
Gold in key local currencies. Year-to-date, up 1.8% in Rupee terms, down 4.0% in US$
Source for above charts; Bloomberg, StoneX
Gold:silver ratio
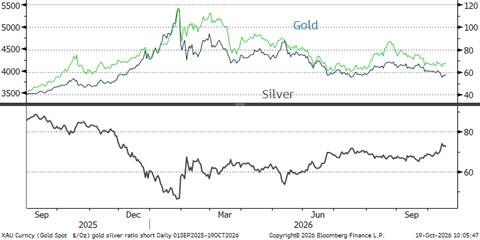
Source: Bloomberg, StoneX
| 19 October 2026 | Previous week | % change | Jan 2025 onwards | Range as % | |||
| Min | Max | ||||||
| Gold (pm LBMA price) | 4,163.22 | 4,172.23 | -0.22% | 57.32% | 1,992.33 | 5,417.21 | 171.90% |
| Silver (LBMA price) | 57.63 | 60.26 | -4.35% | 95.97% | 22.10 | 116.70 | 428.14% |
| Platinum (pm LBMA price) | 1,652.76 | 1,692.09 | -2.32% | 79.45% | 1,552.52 | 2,778.60 | 78.97% |
| Palladium (pm LBMA price) | 1,133.10 | 1,142.63 | -0.83% | 23.03% | 852.13 | 2,054.12 | 141.06% |
| S&P 500 | 7,659.44 | 7,811.54 | -1.95% | 29.67% | 4,688.68 | 7,818.93 | 66.76% |
| $:€ | 1.1239 | 1.1200 | 0.35% | 7.98% | 1.0244 | 1.2041 | 17.54% |
This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.
The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.
The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.
References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.
StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.
R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.
StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.
This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.
StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.
StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).
SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.
StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.
StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.
StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.
StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.
Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.
The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.
© 2026 StoneX Group Inc. All Rights Reserved.
Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.
Renewed Gulf issues boosting yields, precious on the slippage, technicals deteriorating
How gold compares with other assets plus a review of gold liquidity in its own right; and a nod to the Official Sector
A pullback in the U.S. dollar index from an eight-month resistance line is giving gold and silver a firmer macro footing. Bearish momentum signals on the dollar and lower U.S. Treasury yields are reinforcing the precious metals rebound from the July lows.
Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.
Reach
With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bilateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.
Transparency
As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and track record are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.
Expertise
From our proprietary Market Intelligence platform to “boots-on-the-ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.