Commodity Markets: Balancing Act in a World of Extremes
Key Takeaways:
- U.S. crop abundance contrasts with tightening global wheat stocks, creating a complex market dynamic
- Inflation trends and geopolitical tensions introduce significant uncertainty into commodity price forecasts
- Weather patterns, particularly La Niña developments, pose potential risks to global agricultural production
As 2024 comes to an end, U.S. silos are full – even overfull – of corn, soybeans, and wheat, while global wheat stocks available for export have tightened. Meanwhile, on the inflation front, headline CPI dropped recently to 2.4%, while core inflation held stubbornly high at 3.3%. These mixed trends – where abundance meets scarcity and economic resilience faces rising risks – highlight an important convergence for commodity markets according to Arlan Suderman, Chief Commodities Economist for StoneX.
According to the market outlook provided by Suderman, several key factors are reshaping the commodity landscape as we enter the final quarter:
Watch Now
Fed's Balancing Act
The Federal Reserve's evolving approach to their declared 2% inflation target spotlights a complex economic situation. While headline inflation has indeed decreased, core inflation remains stubbornly high. This creates challenges for the Fed and affects commodity markets, notoriously sensitive to changes in inflation. The key question is whether the current inflation is just a pause or a sign of a bigger change in the economy. The answer could have profound implications on how investors and money managers view commodities in the coming years.
Climate Shifts Threaten Crops
Recent climate data shows a developing La Niña system in the Pacific, raising concerns for global agricultural producers. Meanwhile, the U.S. Midwest has just experienced one of the driest 40-day periods on record, threatening crop yields in one of the world's major farming regions. As harvest season approaches in North America, attention will turn to planting efforts in Brazil and Argentina. These countries are key to global soybean production and face uncertain weather that could impact worldwide supply over the coming months.
Global Conflicts Inject Volatility
Ongoing tensions in Ukraine and the Middle East are also exerting an ongoing influence on commodity markets. The prolonged conflict in Ukraine has disrupted grain exports from the Black Sea region, a key source of global wheat and corn supplies. Meanwhile, instability in the Middle East raises concerns about potential disruptions to oil production and shipping routes, contributing to price volatility in both grain and energy markets. Adding to this complex picture, China's economic slowdown and increasingly assertive military posture, particularly in the South China Sea, continue to raise concerns. Any escalation in these conflicts, especially in the Middle East, could lead to severe disruptions in energy and fertilizer supply chains, further complicating the global commodity landscape.
Farmers Face Storage Dilemma
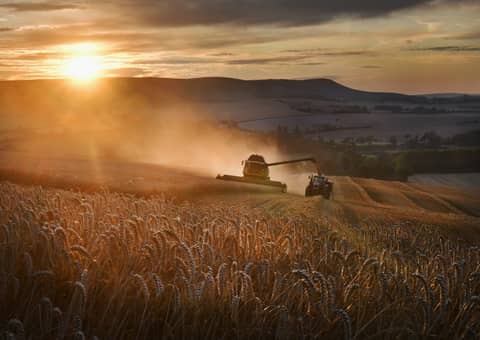
The United States is dealing with an unusual agricultural problem: too many crops, especially corn and soybeans. Usually something to be applauded, the overabundance has created logistical challenges for farmers and grain handlers. Storage facilities across the Midwest are full to overflowing. The situation follows on several years now of strong yields. This storage crunch is putting downward pressure on cash basis prices – the difference between local cash prices and futures market prices. Farmers now are caught between tough choices about whether to sell at lower prices or invest in more storage. Ironically, global wheat market stocks continue to tighten. This contrast between domestic abundance and international scarcity shows the complex and often conflicting nature of global agricultural markets.
Market Outlook Remains Clouded
Looking ahead to 2025, Suderman says commodity markets appear ready for potential reinflation. The European Union's deforestation rule, now delayed to January 2025, adds more complexity to an already intricate global trade situation. In this environment, staying alert is crucial. The current abundance of U.S. stocks provides a cushion, but that could quickly disappear with bad weather or escalating geopolitical tensions. The commodity markets of 2024-25 will likely be shaped not by any single factor but by the interaction of these different forces. Success will depend on navigating this complex mix of supply, demand, policy, and global events. As an old market saying goes, "The trend is your friend until it ends." For commodity traders, finding that trend among today’s mixed signals may be the biggest challenge of all.
Dive Deeper:
Register today and receive advance notification before the next Market Outlook live webinar.
Register Here
StoneX TV content is created, produced, and distributed solely by StoneX Media Ltd (“StoneX TV”) and is provided for informational and educational purposes only. StoneX TV does not provide investment, financial, legal, or tax advice and does not make any recommendation or endorsement of any investment strategy, transaction, or financial instrument. Nothing in this content constitutes, or should be construed as, investment advice or a recommendation to buy, sell, or hold any financial instrument, including securities, futures, derivatives, digital assets, foreign exchange products, or CFDs. This content does not constitute an offer, invitation, or solicitation to engage in any investment activity. The information presented is general in nature and is not tailored to the financial situation, investment objectives, or risk tolerance of any specific person. You should not rely on this content as a substitute for independent professional advice. Investing and trading in financial instruments involves significant risk of loss and is not suitable for all investors. Past performance is not indicative of future results. Any views or opinions expressed are those of the presenter at the time of publication and are subject to change without notice. Such views may not necessarily reflect those of StoneX Media Ltd or its affiliates. StoneX Media Ltd and its affiliates, including StoneX Group Inc., may from time to time have positions in, or engage in transactions involving, the financial instruments referenced. This content may include general market commentary and opinion. It does not constitute independent investment research and has not been prepared in accordance with legal requirements designed to promote the independence of investment research. StoneX Media Ltd is not authorised or regulated to provide investment services and does not act in a fiduciary capacity. StoneX Media Ltd is incorporated in Ireland and operates in accordance with applicable Irish law. It is a wholly owned subsidiary of StoneX Group Inc. and is a separate legal entity from other subsidiaries within the StoneX Group, which may be regulated in various jurisdictions. StoneX Media Ltd does not act on behalf of, or provide services for, any regulated affiliate. This content is not directed at, and may not be distributed to, any person in any jurisdiction where such distribution would be contrary to local laws or regulations. Supporting documentation for any claims, comparisons, statistics, or technical data may be made available upon reasonable request, where applicable.