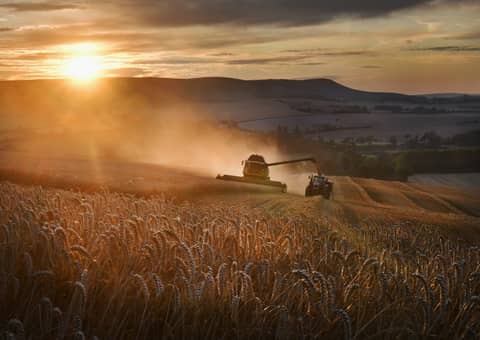
Midwest diesel is trading at one of its weakest differentials to New York Harbor in years at the exact moment local inventories are tight. Farm diesel inventories are sitting low across the Midwest heading into harvest, and that gap between soft regional pricing and thin physical coverage is the setup buyers are walking into. Refineries in the region are moving into their fall maintenance window, which historically pulls supply out of the market just as field demand accelerates. Global conditions are doing the rest of the work, with constrained refining capacity, the closure of the Strait of Hormuz and attacks on Russian refineries all removing distillate barrels from world trade at once.
Alex Hodes is Director of Energy Market Strategy at StoneX, where he advises commercial energy clients on price risk management across crude oil and refined products and tracks supply flows, inventory balances, refinery run rates and crack spread dynamics. Distillate pricing into the U.S. harvest sits inside that coverage, where refinery maintenance schedules, regional basis and farm level fuel demand all meet.
Key Themes from the Discussion
Farm fuel inventories are low across the Midwest just as harvest demand begins to accelerate.
Fall refinery maintenance historically strengthens Group 3 diesel basis through September and October.
The United States exports diesel heavily, making price, not availability, the domestic constraint.
Farm Diesel Inventories Sit Low Ahead of Midwest Harvest Demand
"This is honestly just from some of our clients, word on the street, that people are sitting pretty low with regards to their fuel inventories", says Alex Hodes, describing physical coverage across the Midwest going into the season. Farm diesel inventories entering harvest are thinner than normal, which concentrates buying into a narrow window rather than spreading it across the fall. Hodes expects that to produce a larger demand impulse than the calendar alone would suggest, because operators who deferred filling tanks arrive in the market together. For a grain producer, that means competing for the same barrels as every neighboring operation once machinery starts running.
Refinery Maintenance Season Tightens Midwest Diesel Supply
Fall is when refineries take units down for planned work, and the Midwest is no exception. According to Hodes, several refineries are scheduled to undergo maintenance in the same period that field demand builds, removing regional production precisely when it is most needed. He describes the mechanism plainly, noting that "the Group 3 basis, which is the price differential between Midwest diesel prices and New York Harbor diesel prices, tends to start strengthening into September and October" as refineries go offline and demand picks up. Group 3 basis is currently deeply negative, which is the opposite of what tight local inventories would normally produce. Consequently, buyers are looking at a differential that has historically moved sharply in the other direction once maintenance and harvest overlap.
Diesel Exports Pull U.S. Barrels Away From Domestic Buyers
The United States is a net exporter of diesel, and Gulf Coast export volumes have been running at record highs, which reframes the domestic problem entirely. Hodes draws the same distinction agricultural buyers already know from nitrogen fertilizer, where the market has an affordability problem rather than an availability problem. The resolution is a price mechanism rather than a supply emergency, and as he puts it, "what's going to need to happen is that prices move higher to keep that diesel at home". Persistent risk to Russian supply reinforces that, with Ukraine extending attacks toward tankers and export terminals, leaving the United States as the marginal global supplier. For the physical buyer, the practical read is that domestic prices have to compete with export demand, and headlines about running out are usually a sign the market is near a top rather than a warning about empty terminals.
Frequently Asked Questions
Why is Midwest diesel priced below New York Harbor diesel?
Midwest diesel prices relative to New York Harbor are close to historical seasonal lows even though Midwest inventories are tight. Hodes points to global dynamics setting the overall level of diesel prices while regional pricing has not yet caught up with local physical conditions. He describes the situation as a mismatch, with tight fundamentals sitting underneath a looser regional pricing environment.
Is the United States going to run out of diesel before harvest?
No. The United States overproduces diesel domestically and exports a significant share of what it refines, so the constraint is where barrels go and what they cost rather than whether they exist. Hodes is direct that the country is not going to run out of diesel, and that headlines claiming otherwise usually appear near the top of a price move.
Why are diesel prices rising faster than gasoline prices?
Global refining capacity has been constrained for several years, and no meaningful new capacity is expected in the near term because refineries take years to build. The closure of the Strait of Hormuz removed distillate rich crude from Asian refineries, while attacks on Russian refineries and an export ban pulled another major diesel supplier out of global trade. Gasoline captures attention because consumers watch pump prices daily, while distillate costs climb in the background and pass through freight and food supply chains more slowly.
Make Energy Insights Your Competitive Advantage
Access live prices, supply and demand data and actionable market commentary across commodities, equities, currencies and more. Sign up for StoneX Market Intelligence today and receive a 14-day trial.
--- Written by Frédéric Guétin, StoneX Media Producer
--- Expert: Alex Hodes, StoneX Director Energy Market Strategy
Energy
StoneX TV content is created, produced, and distributed solely by StoneX Media Ltd (“StoneX TV”) and is provided for informational and educational purposes only. StoneX TV does not provide investment, financial, legal, or tax advice and does not make any recommendation or endorsement of any investment strategy, transaction, or financial instrument. Nothing in this content constitutes, or should be construed as, investment advice or a recommendation to buy, sell, or hold any financial instrument, including securities, futures, derivatives, digital assets, foreign exchange products, or CFDs. This content does not constitute an offer, invitation, or solicitation to engage in any investment activity. The information presented is general in nature and is not tailored to the financial situation, investment objectives, or risk tolerance of any specific person. You should not rely on this content as a substitute for independent professional advice. Investing and trading in financial instruments involves significant risk of loss and is not suitable for all investors. Past performance is not indicative of future results. Any views or opinions expressed are those of the presenter at the time of publication and are subject to change without notice. Such views may not necessarily reflect those of StoneX Media Ltd or its affiliates. StoneX Media Ltd and its affiliates, including StoneX Group Inc., may from time to time have positions in, or engage in transactions involving, the financial instruments referenced. This content may include general market commentary and opinion. It does not constitute independent investment research and has not been prepared in accordance with legal requirements designed to promote the independence of investment research. StoneX Media Ltd is not authorised or regulated to provide investment services and does not act in a fiduciary capacity. StoneX Media Ltd is incorporated in Ireland and operates in accordance with applicable Irish law. It is a wholly owned subsidiary of StoneX Group Inc. and is a separate legal entity from other subsidiaries within the StoneX Group, which may be regulated in various jurisdictions. StoneX Media Ltd does not act on behalf of, or provide services for, any regulated affiliate. This content is not directed at, and may not be distributed to, any person in any jurisdiction where such distribution would be contrary to local laws or regulations. Supporting documentation for any claims, comparisons, statistics, or technical data may be made available upon reasonable request, where applicable.
Discover more insights
Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.
Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.
Reach
With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.
Transparency
As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.
Expertise
From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.