
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside - read on for the full Q4 outlook!

David Scutt
- Global Macro
By: Fiona Cincotta, Senior Market Analyst
GBP/USD has fallen just 0.5% across the third quarter. While the pair booked solid gains in July and August, those were unwound in September with the pair falling over 2%. The sharp decline in GBP/USD in September came as the U.S. dollar staged a powerful recovery, but the pound also weakened against major peers, including the Japanese yen, Australian dollar and Canadian dollar. The pound rose modestly against the euro, New Zealand dollar and Swiss franc.
The balance of risks points to a downside bias for the pound against the U.S. dollar across the final quarter of the year, as widening Fed-BoE policy divergence continues to support the USD.
Inflation
Headline UK inflation rose to 3.1% annually in August, its highest level since March. The increase comes amid the direct effect of higher energy prices from the Middle East conflict. Brent crude prices have fluctuated from lows of around $70 to well over $110 per barrel during the quarter, while natural gas prices have also risen sharply.
As a result, fuel prices have increased significantly, while the Ofgem energy price cap will rise by almost 4% in October.
The Bank of England's latest near-term inflation forecast points to CPI inflation rising to around 3.7% in Q4 2026 and 4.2% in Q1 2027.
Meanwhile, core inflation, which excludes more volatile components, remained at 2.6% in August, while services inflation also remained unchanged at 3.4%. So far, there has been little evidence that firms are passing higher energy costs through into broader prices, meaning second-round effects have yet to become a major concern.
However, food-price inflation is expected to rise in the coming months, adding another potential source of pressure after droughts in the UK over the summer and as Super El Nino hits.
GDP and Labour Market
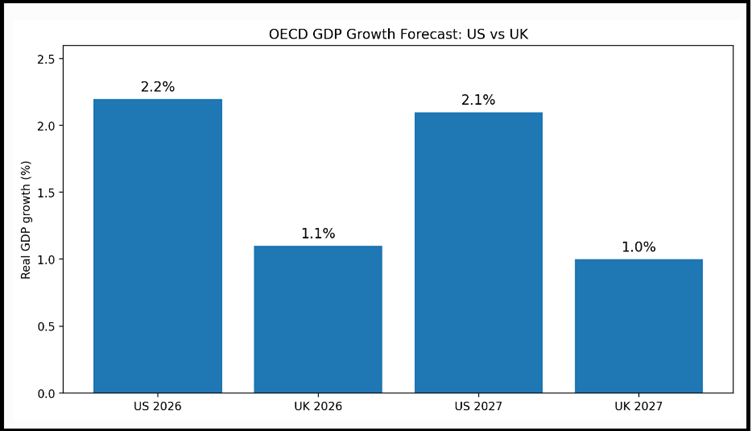
UK GDP grew by a stronger-than-expected 0.4% month on month in July, following growth of 0.4% in Q2. The OECD forecast growth of 1.1% in 2026 and 1% in 2027. Notably weaker than the growth expected in the US,
The labour market, however, has shown signs of slowing. Vacancies have fallen to their lowest level in five years, while wage growth has also moderated.
Weak UK labour demand, combined with sluggish economic growth momentum, could weigh on GBP and highlight the policy challenges the BoE faces.
Bank of England Outlook
Markets are pricing significant tightening from the Bank of England between now and July 2027. However, higher energy prices create a difficult policy mix. While inflation risks are rising, growth momentum faces a challenging outlook, leaving the pound vulnerable as the policy trade-offs become more acute.
The Bank of England left interest rates unchanged at 3.75% for a sixth straight meeting in September, with the vote split remaining 6-3. Governor Andrew Bailey warned that inflation risks remained to the upside, while stressing that there was still limited evidence of second-round inflation effects. The Bank has made clear that a prolonged period of elevated energy prices could eventually require higher rates.
According to the OECD, the Bank of England does not need to raise rates further because policy is already restrictive enough to bring inflation back towards target.
This contrasts with market expectations and raises the possibility that rate-hike expectations have become too aggressive. If so, the pound could come under further pressure as markets unwind some of those hawkish bets.
Political Uncertainty
With Prime Minister Andy Burnham now in power, attention is turning to Chancellor John Healey's Budget on October 28.
The Budget comes against a backdrop of surging gilt yields, with the 10-year yield around 5.38%, putting further pressure on public finances and narrowing fiscal headroom.
The rise in yields reflects persistent global inflation concerns, but the UK debt profile remains particularly vulnerable to higher borrowing costs. Recent borrowing data showed the fiscal year deficit running £8.1 billion above the OBR's forecast, while higher debt-servicing costs have reduced the government's room for manoeuvre.
Without significant tax rises or spending restraint, the Chancellor faces a difficult fiscal balancing act, which could add another source of uncertainty for sterling.
The U.S. economy has remained remarkably resilient despite the ongoing conflict in the Middle East, rising energy prices, tariffs and inflationary pressures.
September U.S. PMI data showed private economic activity expanding at its fastest pace in five years.
Meanwhile, labour-market conditions remain relatively healthy, with 162,000 jobs added in August and expectations for another 100,000 in September.
The concern is not about a weaker jobs market but that the labour market could be too strong, adding to demand and potentially keeping inflation elevated.
Inflation is also proving sticky. CPI came in at 3.4% in August, while core inflation was hotter than expected. The Fed's preferred inflation gauge, core PCE, is also expected to remain at 3.4%, well above the 3% target level.
Federal Reserve Rate Hikes
The Fed raised rates by 25 basis points in September to 3.75%-4.00%, while markets are pricing in around a 70% chance of another hike in October. Fed officials have also continued to stress the need for further hikes to keep inflation under control.
The possibility of further rate hikes has helped drive the U.S. dollar to a two-month high.
The U.S. Federal Reserve is therefore looking increasingly hawkish, while the Bank of England is still questioning whether further tightening is necessary.
The widening Fed-BoE policy divergence remains the strongest argument for further GBP/USD weakness in Q4.
However, there is a potential reversal to this trade. Should the war in the Middle East end, a sharp fall in oil prices could ease U.S. inflationary pressures. If this feeds through to core PCE and weaker rate expectations, markets could begin scaling back Fed tightening bets.
That would remove one of the dollar's largest sources of support and could allow GBP/USD to recover.
GBP/USD Scenarios
The balance of risks points towards a weaker pound and a stronger U.S. dollar over the coming quarter.
Despite rising UK headline inflation, core inflation and services inflation are not yet showing significant second-round effects, while the UK labour market is deteriorating. Political uncertainty and weaker domestic growth could also limit the scope for an aggressive BoE hiking cycle.
The U.S. economy, by contrast, continues to show resilience, while inflation remains elevated and markets are increasingly pricing further Fed tightening.
For GBP/USD, the key variable may ultimately be oil. A sustained rise in energy prices would reinforce inflation pressures, support higher U.S. yields and strengthen the dollar. A significant decline in oil prices could do the opposite, pulling USD lower and provide a tailwind to GBP/USD.
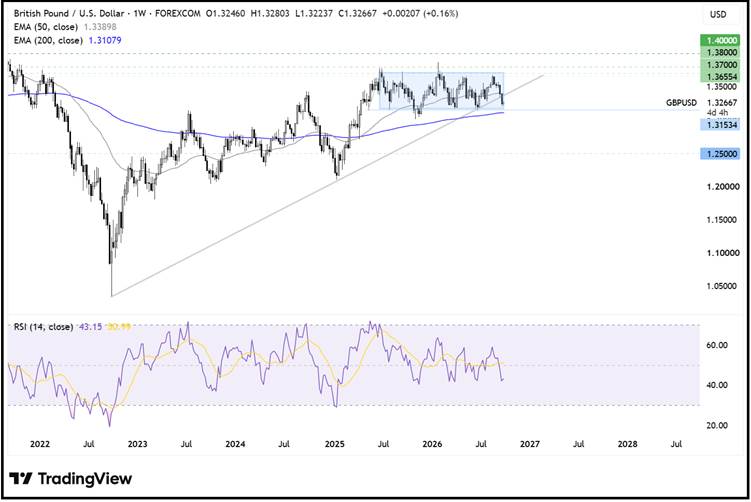
GBP/USD continues to trade in a broad consolidation range, capped on the upside around 1.37 and supported around 1.3150.
The price has broken below the 50 EMA and the multi-year rising trend line. Combined with an RSI below 50, this keeps sellers hopeful of further downside.
Sellers would need to break below 1.3150 and the 200 EMA around 1.31 for downside momentum to accelerate towards 1.30. Below here, 1.25 comes into focus.
On the upside, 1.34 is a key level, where the rising trend line and 50 EMA now converge. A rise above 1.37 would create a higher high and break the pair out of the range in which it has traded since June 2025.
-- Prepared by Fiona Cincotta
StoneX TV content is created, produced, and distributed solely by StoneX Media Ltd (“StoneX TV”) and is provided for informational and educational purposes only. StoneX TV does not provide investment, financial, legal, or tax advice and does not make any recommendation or endorsement of any investment strategy, transaction, or financial instrument. Nothing in this content constitutes, or should be construed as, investment advice or a recommendation to buy, sell, or hold any financial instrument, including securities, futures, derivatives, digital assets, foreign exchange products, or CFDs. This content does not constitute an offer, invitation, or solicitation to engage in any investment activity. The information presented is general in nature and is not tailored to the financial situation, investment objectives, or risk tolerance of any specific person. You should not rely on this content as a substitute for independent professional advice. Investing and trading in financial instruments involves significant risk of loss and is not suitable for all investors. Past performance is not indicative of future results. Any views or opinions expressed are those of the presenter at the time of publication and are subject to change without notice. Such views may not necessarily reflect those of StoneX Media Ltd or its affiliates. StoneX Media Ltd and its affiliates, including StoneX Group Inc., may from time to time have positions in, or engage in transactions involving, the financial instruments referenced. This content may include general market commentary and opinion. It does not constitute independent investment research and has not been prepared in accordance with legal requirements designed to promote the independence of investment research. StoneX Media Ltd is not authorised or regulated to provide investment services and does not act in a fiduciary capacity. StoneX Media Ltd is incorporated in Ireland and operates in accordance with applicable Irish law. It is a wholly owned subsidiary of StoneX Group Inc. and is a separate legal entity from other subsidiaries within the StoneX Group, which may be regulated in various jurisdictions. StoneX Media Ltd does not act on behalf of, or provide services for, any regulated affiliate. This content is not directed at, and may not be distributed to, any person in any jurisdiction where such distribution would be contrary to local laws or regulations. Supporting documentation for any claims, comparisons, statistics, or technical data may be made available upon reasonable request, where applicable.
Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside - read on for the full Q4 outlook!

GBP/USD has fallen just 0.5% across the third quarter. While the pair booked solid gains in July and August, those were unwound in September with the pair falling over 2% - read on for the full Q4 outlook!

The historically-reliable 4-year halving cycle suggests that Bitcoin’s bear market may soon be coming to an end, if it hasn’t already - read on for the full Q4 forecast!

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.
Reach
With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.
Transparency
As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.
Expertise
From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.