Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for November 10

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

November 10 – October CPI inflation data came in slightly hotter than expected this morning, with headline CPI rising 0.4% month-on-month and core CPI rising 0.3% month-on-month, both of which were 0.1% above the average analyst estimate. Year-on-year figures were not published due to last October’s government shutdown, but we can interpolate using the CPI index itself. If we take the average of last September and November’s CPI index of 324.461, it would imply a headline CPI increase of 4.0% year-over-year, which would be an acceleration from the 3.7% seen in September and the hottest reading since May. Given the major build-up of inflationary pressures already seen at the producer level, it’s no surprise to see the pass-through to the consumer taking place, as we’ve been pointing to for months.   

Stock futures are pointing to a lower open in classic turnaround Tuesday fashion as they look to take back some of yesterday’s sharp gains. The VIX is up 5.7% from yesterday’s close, currently sitting just above 21, though well below the recent highs above 28 seen last week. The dollar is looking at a turnaround Tuesday as well, up 0.3% to trade near 102 at the time of writing. Treasury yields are sharply higher to start the session, with 2-year yields up near 15-basis points to trade near 4.70%, 10-year yields up 9-basis points to trade near 4.955%, and 30-year yields up 6-basis points to trade just below 5.32%. Crude oil prices are continuing lower amid de-escalatory rhetoric coming from the Trump administration, with nearby WTI down 2.2% on the day to trade below $84.50 while nearby Brent is down 3.4% to trade near $89.40. Meanwhile, the ags are quietly lower at the break.

Trilateral talks between Russia, Ukraine, and the U.S. have begun in Abu Dhabi today, marking the first direct negotiations among the parties since February. While the meeting has fueled optimism in some corners of the market that progress toward a ceasefire could eventually improve Black Sea trade flows and reduce geopolitical risk premiums, expectations for a near-term breakthrough remain low. Officials from both the Ukrainian and Russian delegations continue to signal significant differences over territorial issues, security guarantees and the broader European security framework. As a result, grain markets may remain vulnerable to headline-driven volatility, but any assumption that the talks will quickly lead to increased Black Sea exports or a lasting resolution to the conflict appears premature at this stage.

Russian officials are clearly trying to curry favor with the U.S. ahead of said talks, with Russian Foreign Minister Sergei Lavrov writing a piece on Tuesday for Russia’s prominent newspaper Kommersant touting the effectiveness of last month’s diesel diplomacy. He was quoted as saying: “an important contribution to energy security was the agreement between the Russian and U.S. leaders to suspend restrictions on the export of Russian diesel. We have already started implementing it, which immediately brought prices down.” There is still no confirmed unloading of Russian diesel in the U.S. that I can find, with the vessels originally loaded for the U.S. diverting to other markets as domestic buyers shun the barrels due to the associated legal risks. When this deal was originally announced on October 9, U.S. national average diesel prices per GasBuddy were at $6.258/gallon. Today, they stand at $6.164/gallon—i.e. $0.09/gallon lower. Total U.S. distillate stocks as of last week’s D.O.E. report are currently at their tightest level for this point in the year on record and their lowest for any point in the year since May 2003. The reason I point this out is because it’s a prime example of the divergence between headlines and reality on the ground, an important distinction to level-set reality ahead of these talks. Headlines will likely drive volatility as they have through all of 2026, but physical commodity markets ultimately need to see changes on the ground, which have proven much more elusive as this war nears the five-year mark.

U.S. corn and soybean harvest both moved a little slower than expected on yesterday afternoon’s Crop Progress report from USDA, with corn harvest advancing 7% week-on-week to reach 81% complete and soybeans advancing 4% week-on-week to reach 92% complete, both 1% below their respective average analyst estimates. Both are behind schedule, but corn is now relatively further behind given the focus on getting soybeans out seen over the last month, with the current pace of corn harvest the slowest since 2019 and soybeans the slowest since 2021. The biggest delay for the corn crop remains in top producer Iowa, with South Dakota now tying them—both 17% behind their reported previous five-year average paces. With a sharp break lower in prices and direct payments from the Harvest Fuel Relief program coming, farmers will likely not be in a hurry to sell. Couple this with the delayed harvest, and we may continue to see additional strength in the affected cash markets.

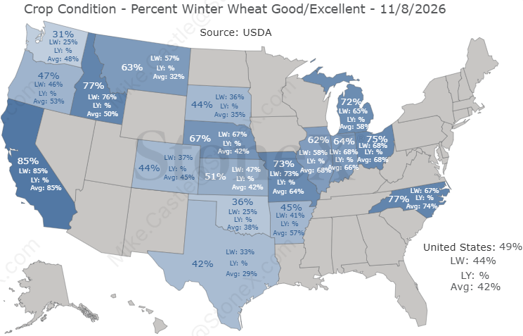
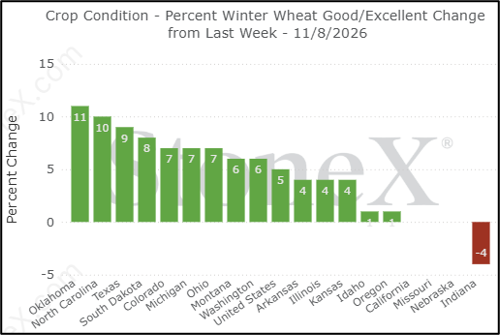
U.S. winter wheat conditions surged 5% higher week-on-week to now sit at 49% good/excellent, handily topping optimistic trade estimates for a more modest improvement to 47%. That big uptick now puts national winter wheat ratings at their highest for the comparable week in six years. Oklahoma led the way higher, jumping 11% week-on-week to now sit at 36% good/excellent as this fall’s abundant moisture helps get the crop off to a great start, though this week’s break from the rain and some sunshine will certainly be welcome. On that note, this week’s weather should also help the state, and broader Central/Southern Plains region, push through tail-end of planting season. Oklahoma remains the furthest behind schedule on winter wheat planting, advancing another 15% week-on-week to reach 77% complete, still trailing their previous five-year average pace by 9% but playing notable catch-up from recent weeks. At the national level, winter wheat planting advanced another 6% week-on-week to reach 89% complete, in line with the average analyst estimate and bringing planting progress closer to historical averages after seeing the slowest pace on record for much of the fall. While we don’t have comparable numbers from last year due to the government shutdown, this year’s pace is now only tied for the 3rd slowest pace since 2000. Winter wheat crop insurance prices being at four-year highs, corn/soybean prices tanking through the fall, and major improvements to soil moisture profiles are all driving incentive for heavier U.S. winter wheat planting.

image 140421

image 140422

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for November 10

November 10 – October CPI inflation data came in slightly hotter than expected this morning, with headline CPI rising 0.4% month-on-month and core CPI rising 0.3% month-on-month, both of which were 0.1% above the average analyst estimate. Year-on-year figures were not published due to last October’s government shutdown, but we can interpolate using the CPI index itself. If we take the average of last September and November’s CPI index of 324.461, it would imply a headline CPI increase of 4.0% year-over-year, which would be an acceleration from the 3.7% seen in September and the hottest reading since May. Given the major build-up of inflationary pressures already seen at the producer level, it’s no surprise to see the pass-through to the consumer taking place, as we’ve been pointing to for months. Stock futures are pointing to a lower open in classic turnaround Tuesday fashion as they look to take back some of yesterday’s sharp gains. The VIX is up 5.7% from yesterday’s close, currently sitting just above 21, though well below the recent highs above 28 seen last week. The dollar is looking at a turnaround Tuesday as well, up 0.3% to trade near 102 at the time of writing. Treasury yields are sharply higher to start the session, with 2-year yields up near 15-basis points to trade near 4.70%, 10-year yields up 9-basis points to trade near 4.955%, and 30-year yields up 6-basis points to trade just below 5.32%. Crude oil prices are continuing lower amid de-escalatory rhetoric coming from the Trump administration, with nearby WTI down 2.2% on the day to trade below $84.50 while nearby Brent is down 3.4% to trade near $89.40. Meanwhile, the ags are quietly lower at the break.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for November 9

November 9 – Stock futures built on Friday’s consolidation, as value buyers slowly re-entered the market overnight. We’ll get key inflation data this week, with the consumer price index for October scheduled for release tomorrow, followed by the producer price index on Friday. Scheduled negotiations regarding both major wars on commodity logistics will also take place over the next few days. The VIX slid lower to trade near 23, while the dollar index slipped lower to trade near 101.8. Yields on 10-year Treasuries are trading near 4.83% this morning, while yields on 2-year Treasuries are trading near 4.52%. WTI crude oil prices are near $87, while Brent trades near $94 per barrel. The grain and oilseed complex traded mixed to weaker overnight, with traders now focused on tomorrow’s big USDA WASDE crop report.

Arlan Suderman
Arlan Suderman
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for November 6

November 6 – Volatility remains high on Wall Street this morning, as we add the monthly jobs report to the post-election market correction. The Nasdaq dropped sharply on Thursday amid a fear that the Democrats taking over Congress would create major challenges for tech companies – especially those involved with AI. It’s trying to bounce this morning, but the headlines over AI risks continue to flow. Today’s jobs report should help to redirect some of that focus momentarily, but the possibility of more volatility clearly remains with us. As such, the VIX – Wall Street’s “fear index” – is trading near 27 at this hour. My observation over the decades is that commodity assets struggle to sustain rallies when the VIX is above 30, unless that asset has a strong story of its own. The dollar index is trading near 102.3. Yields on 10-year Treasuries are trading near 4.86%, while yields on 2-year Treasuries are trading near 4.53%. WTI crude oil is trading near $91, while Brent trades near $98 per barrel. The grain and oilseed sector traded mixed overnight, with wheat posting double-digit losses, while corn and soybeans were either side of unchanged in early trade.

Arlan Suderman
Arlan Suderman
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.