Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for November 2

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

November 2 – Stocks are looking to bounce back after Friday’s ugly selloff, with the tech heavy Nasdaq showing the sharpest gains after posting the sharpest losses last week. The VIX touched a nearly seven-month high on Friday but has reversed course sharply since, down another 2% to start the day near the 19 level. The dollar touched a one-month low overnight but has recovered since, currently hovering near 101.61. Treasury yields are notably mixed to kick off the week, with 2-year yields up 2-basis points to sit at 4.60%, while 10-year yields are down over 2-basis points to sit at 4.905%, and 30-year yields are down nearly 4-basis points to trade at 5.272%. The ags are largely mixed at the break, with corn and wheat clinging to small gains while soybeans show small losses. It will be interesting to see if more strength will be seen at the open after a massive 1.730 million metric ton (68.1 million bushel) flash sale of U.S. corn to Mexico was just announced, as well as another 136k metric tons (5.0 million bushels) of soybeans to China. Amid the sharp break lower in prices, these are the kind of signals these markets need to see to stop the bleeding.

Crude oil prices are starting the week sharply lower amid the ongoing diplomatic push ahead of tomorrow’s U.S. midterm elections, balanced with reports continuing to circulate of a planned renewal of U.S. / Israeli strikes on Iran after the elections are over. Outside of a couple more ships reportedly being hit by mines near the Strait of Hormuz, we didn’t see any notable escalations during the weekend market closure, with the primary flashpoint remaining in Yemen. On that note, fighting on the ground within Yemen continues to rage, as the intense, Saudi-led air campaign continues, and Saudi officials report intercepting both drones and missiles launched at various targets, though no major damage was reported. Iranian Foreign Minister Abbas Araqchi said yesterday that talks with Qatari mediators continue, noting the country was prepared for “both defense and diplomacy,” with more focus in the market on the latter today. Headlines have hit the wire services this morning that Iran’s new Supreme Leader Mojtaba Khamenei has granted the government specific authorities to conduct negotiations, a potential signal of an easing from the hardline factions, though concrete progress remains elusive. We’ll continue to monitor the developments in both rhetoric and on the ground action in the days ahead.  

The tech sector is trying to find its footing to start the week after last week’s bloodbath that capped off a rough month for the space. October was the worst month of 2026 for the tech sector, with the Nasdaq losing 5.3%, while semiconductor shares were hit particularly hard as the Philadelphia Semiconductor Index (SOX) tumbled 15.4%, including a 7.2% rout last Friday. Last week’s big tech earnings ultimately drove the selloff as investors scrutinize the eye-popping cash burn of the ongoing AI buildout and increasing need to see corresponding revenue growth to justify, and more big names are on deck in the days ahead. Apple and Palantir are both due to report after today’s close, with the former likely to set the tone to start the week, followed by AMD tomorrow (11/3), Qualcomm on Wednesday (11/4), and Cloudflare on Thursday (11/5), among others. The slate continues into next week as well, with Sony, Cisco, and Applied Materials all due out between Tuesday (11/10) and Thursday (11/12), with Nvidia on 11/17 capping off the third quarter tech earnings season. Add in the U.S. midterm elections tomorrow, and the accompanying geopolitical questions surrounding their results, and investors clearly have a lot on their plates in the days/weeks ahead, likely keeping the volatile, headline-driven trade that we’ve become accustomed to in play.

The six-day ceasefire around the battered frontline Ukrainian city of Oleshky expired on Sunday, with both sides describing the operation as successful but failing to agree on an extension. Elsewhere in the conflict, escalations continued through the weekend with Russia striking power infrastructure across Ukraine, leaving hundreds of thousands of civilians without power again as winter approaches. At the same time, Ukraine has resumed large-scale strikes on Russian refineries, hitting several in recent days, though details regarding the extent of the damage remain uncertain at this point. In terms of Black Sea commodity movement, it’s worth noting the growing U.S. push, with Secretary of State Marco Rubio this weekend addressing the “growing interest” in partial deals to halt attacks on ships as proposals from both Turkey and India continue, though no deal has been reached to this point.

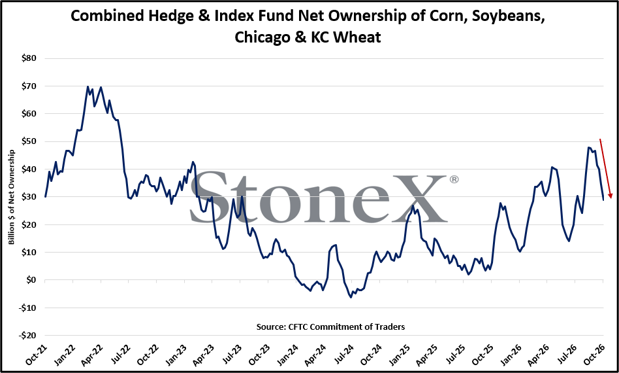
Managed money still appears to be looking for the exit from the grains and oilseeds, as Friday afternoon’s CFTC Commitment of Traders report showed another massive week of long liquidation across the complex. The heaviest selling pressure was seen in corn, with managed money shedding a net 83.3k contracts (or 90.3k including options) as the rush for the exit continues. After seeing managed money length in corn push to an all-time high, managed money has now shed over 333k contracts (futures only) in just the last six weeks, or 371k contracts including options. This is not exclusive to corn either, with Friday’s report showing net selling from managed money across corn, soybeans, soybean meal & oil, and all three U.S. wheat contracts. Taking a look at the chart below, combined hedge and index fund net ownership of corn, soybeans, Chicago, and KC wheat reached a four-year high in early September—that has been slashed by nearly 40% since.

image 139913

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for November 2

November 2 – Stocks are looking to bounce back after Friday’s ugly selloff, with the tech heavy Nasdaq showing the sharpest gains after posting the sharpest losses last week. The VIX touched a nearly seven-month high on Friday but has reversed course sharply since, down another 2% to start the day near the 19 level. The dollar touched a one-month low overnight but has recovered since, currently hovering near 101.61. Treasury yields are notably mixed to kick off the week, with 2-year yields up 2-basis points to sit at 4.60%, while 10-year yields are down over 2-basis points to sit at 4.905%, and 30-year yields are down nearly 4-basis points to trade at 5.272%. The ags are largely mixed at the break, with corn and wheat clinging to small gains while soybeans show small losses. It will be interesting to see if more strength will be seen at the open after a massive 1.730 million metric ton (68.1 million bushel) flash sale of U.S. corn to Mexico was just announced, as well as another 136k metric tons (5.0 million bushels) of soybeans to China. Amid the sharp break lower in prices, these are the kind of signals these markets need to see to stop the bleeding.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Mid-Day Commentary for October 30

October 30 – Intel is officially seeing its sharpest one-day drop on record, with its stock currently down nearly 29% as the selling pressure in the tech sector intensifies amid renewed fears of the surging costs associated with the ongoing AI buildout. That selling pressure has spread across global chip stocks, with the Philadelphia Semiconductor Index (SOX) down nearly 7% at the time of writing. A good share of this weakness is likely more of a rotation of money out of tech and into other sectors, however, with the tech heavy Nasdaq seeing the biggest weakness as it falls over 3% on the day to reach its lowest level since early August, though the S&P 500 is down a more modest 1.5% to trade at a roughly six-week low, while the Dow Jones is down only 0.7%, back to where it was trading early last week. The VIX is surging in turn, up over 14% on the day to carve out a new high for the week, currently hovering near 19.7 at midday. The dollar has had a volatile session but now sits up 0.1% on the day to trade at 101.95. Treasury yields remain lower at midday, perhaps reflecting some money leaving the equities space and looking for safe havens, with 2-year yields off 4-basis points to trade at 4.614%, 10-year yields off 3-basis points to trade at 4.956%, and 30-year yields just below unchanged to sit at 5.326%. Crude oil is looking to end the week on a strong note as we head into the weekend market closure with fears of Middle East escalation lingering as Tuesday’s midterm elections arrive, with nearby WTI posting another fresh six-week high today, currently sitting up 1.2% to trade near $104.15, while nearby Brent is up 2.5% to trade near $113.60, its highest level of the week.

Mike Castle
Mike Castle
  • Grains & Oilseeds

Perspective: Morning Commentary for October 30

October 30 – Nasdaq futures are pointing to a sharply lower open following yesterday’s third quarter earnings results from Amazon and Intel, acting as a drag on the broader equities sector to start the day. Despite solid earnings and growth, both companies are seeing widely negative response to their third quarter results as investors become much less tolerant of deteriorating cash flow and seemingly endlessly higher capex requirements amid the ongoing AI buildout. The strong results from AWS and Intel's data center business reinforce the underlying AI infrastructure boom, but the negative stock reactions suggest investors are demanding clearer evidence that hundreds of billions of dollars in AI spending will translate into sustainable returns, especially in the context of higher interest rates. Amazon shares are down close to 7% while Intel is down nearly 25% in pre-market trading, highlighting the resurgent jitters in the sector. Earnings season will continue for big tech next week as well, with Apple, Palantir, AMD, and Qualcomm all reporting between Monday (11/2) and Wednesday (11/4), giving traders a fresh look at AI capex and their subsequent impact on revenue and margin growth and keeping this conversation in focus on Wall Street.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.