Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Soybean Weekly Report

StoneX Intelligence Brazil

StoneX Intelligence Brazil

Concerns about weather impacts on US crop support prices in Chicago
 
Ana Luiza Lodi
 Market Intelligence Specialist
Pro Famer's Crop Tour sees crop below the USDA number, with great variability of samples collected
Bearish factors
  • World production in 2023/24 is expected to be far above consumption, according to the USDA;
  • Economic indicators still weak;
  • StoneX estimates a new record crop for Brazil in 2023/24;
  • Pressured margins of the hog sector in China;
  • Weak US exports.
 
Bullish factors
  • China's heated soybean imports;
  • Positive crush margins in China;
  • US crop productivity and production cut;
  • Positive prospects for the American crush;
  • Drier weather, with high temperatures in the US and lower production estimates by Pro Farmer.

The bullish trend prevailed for another week in Chicago, under the main influence of the progress of the North American crop. The November 2023 contract ended Friday's session (25) at 1387.75 cents per bushel, an increase of 2.5%.

As the weather in August is very important for the final result of North American productivity due to the grain-filling stage, the drier and warmer weather that has prevailed since the middle of the month brings concerns.

Good rainfall was recorded this past weekend in the central US Plains and the southwest Midwest. The most significant volumes occurred in southeastern Nebraska, southern Illinois, far southwestern Indiana, and Kentucky. For this week, forecasts indicate that rainfall is expected to be lower than expected across the entire Midwest but with milder temperatures. Already from next weekend, in addition to the forecasts continuing to indicate drier weather, temperatures should return to rise above usual.

Also, the traditional Pro Farmer Crop Tour was held last week regarding the North American crop, touring the country's main corn and soybean producers. The field surveys highlighted a great variability of the samples collected, and the daily results of the pod count moved the market.

The final result of the crop tour, which considers, in addition to the crops evaluated, the stage of development, area adjustments, and differences from the official USDA data, among other factors, brought an average national productivity of 3.34 tonnes per hectare, with 2023/24 soybean production estimated at 111.86 million tonnes, against 114.44 million in the last USDA report. Only Indiana and Ohio recorded yields above the latest official USDA data, considering the seven states assessed. It is also noteworthy that in the final disclosure, it was emphasized that there is still a need for moisture in several regions to confirm these estimates. That is why the US weather continues to be closely monitored until the final productivity of the crops is defined.
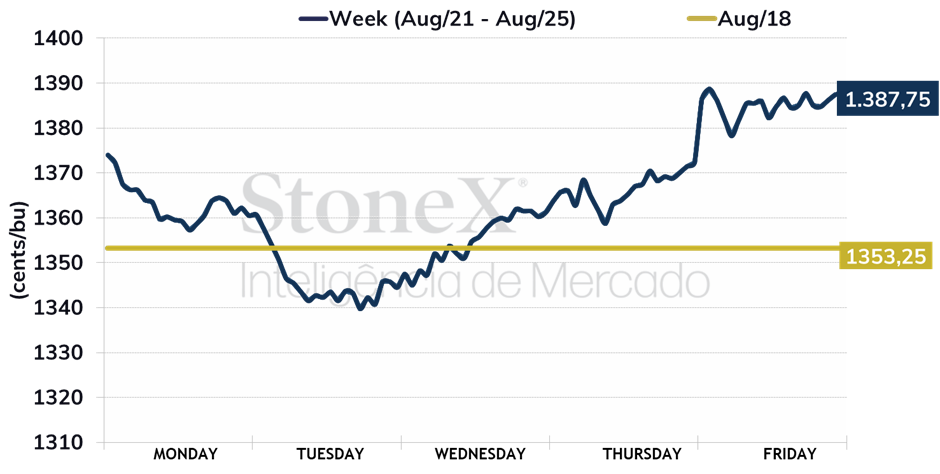
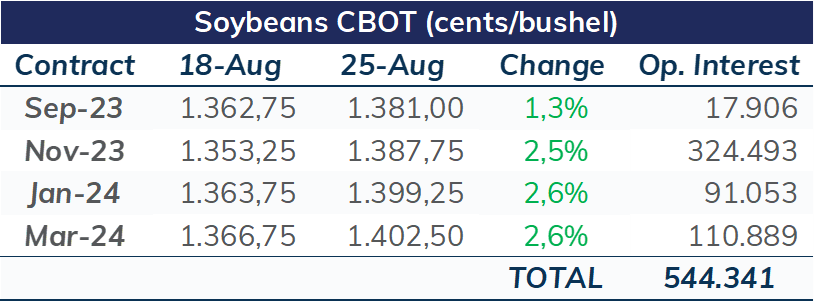
Weekly Intraday - November/23
image 78959
 
image 78960
Source: CME. Design: StoneX.

US soybean crop conditions for the week ended 08/20 were stable, with the good percentage excellent at 59%, the level closest to the five-year average at 61%. The market awaits the next update in the late afternoon of Monday (28) after last week's hotter and drier weather. The Pro Farmer tour was held under a strong mass of warm air in some of the states visited, such as Iowa.

On the demand side, US export sales in the week ended 08/17 reached 364.95 thousand tonnes for the 2022/23 crop, volume above the top of estimates, which ranged from 0 to 200 thousand tonnes. For the 2023/24 crop, trading stood at 1.22 million tonnes, within the range of market expectations.

Either way, the chances of the estimate of exports to the US in the 2022/23 crop not being reached are increasing more and more, with only two weeks to go until the end of the crop year at the end of August. As of August 17, 51.5 million tonnes of the oilseed had been inspected, and the weekly volumes are lower than last year.
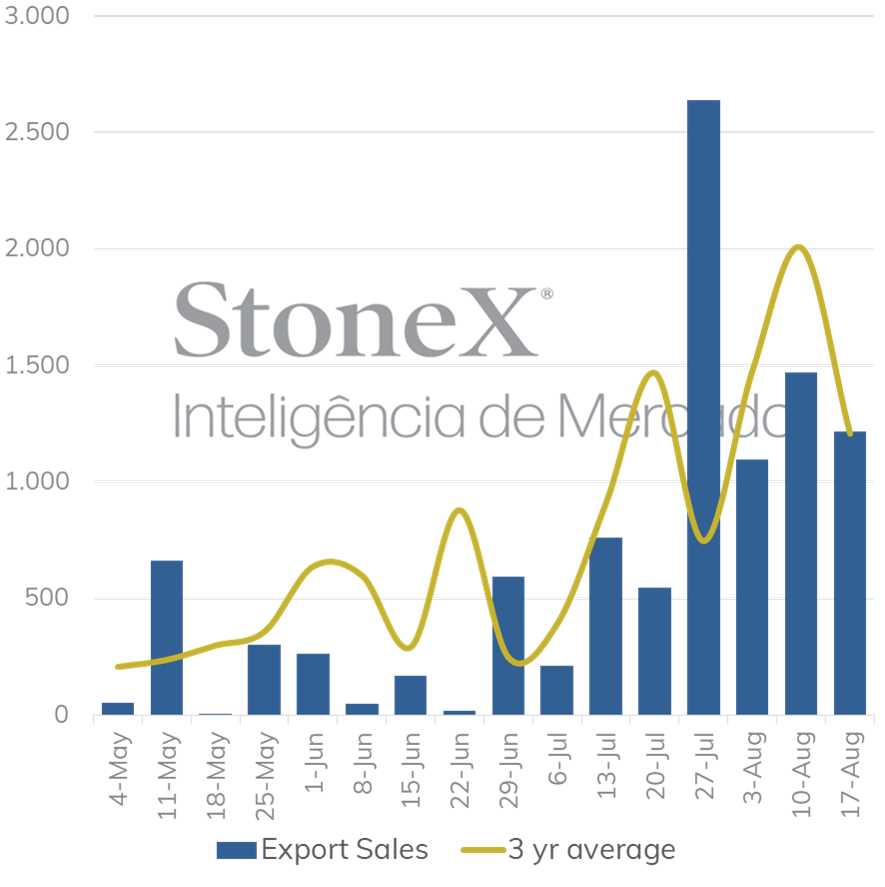
US export sales - 2023/24 crop (thousand tonnes)
image 78961
Source: USDA. Design: StoneX.


In China, crush margins remain positive, but concerns remain about the hog industry's margin. The country has recovered faster than expected from the large outbreak of African Swine Fever (ASF) between 20180 and 2019, which decimated almost half of its herd. Still, margins of activity remain under pressure, which could negatively impact the demand for soybean meal and, consequently, the crushing and import of the grain. It should be noted that the USDA estimates the country's soybean imports at 99 million tonnes in the 2023/24 cycle, below the potential result of the 2022/23 crop at 100 million.

In Brazil, the soybeans planting in 2023/24 is expected to begin in mid-September, after the end of the fallowing period in some states. The longer forecasts indicate rainfall within the normal range in southern Brazil, while in the central region, rainfall may be above normal in September.

This week, in addition to the usual data, the disclosure of Brazilian soybean exports in August to be released next Friday (01) stands out. 
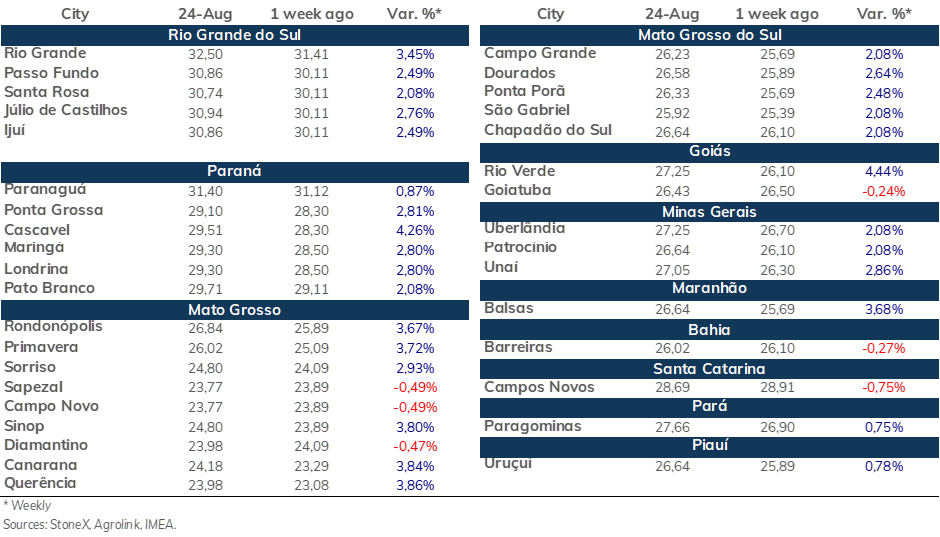
 

Spot prices (USD/60kg-bag)
image 78962


Indicators
  • Grains & Oilseeds

The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided. References to over-the-counter (“OTC”) products or swaps are made on behalf of StoneX Markets LLC (“SXM”), a member of the National Futures Association (“NFA”) and provisionally registered with the U.S. Commodity Futures Trading Commission (“CFTC”) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ (“ECP”) and who have been accepted as customers of SXM. StoneX Financial Inc. (“SFI”) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (“SEC”) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Adviser. References to securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to exchange-traded futures and options are made on behalf of the FCM Division of SFI . StoneX is a trading name of StoneX Financial Ltd (“SFL”). SFL is registered in England and Wales, Company No. 5616586. SFL is authorized and regulated by the Financial Conduct Authority [FRN 446717] to provide to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorised to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorised & regulated by the Financial Conduct Authority under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorised by the Financial Conduct Authority. StoneX Group Inc. acts as agent for SFL in New York with respect to its payments services business. StoneX APAC Pte. Ltd. acts as agent for SFL in Singapore with respect to its payments services business. ‘StoneX’ is the trade name used by StoneX Group Inc. and all its associated entities and subsidiaries.
 
Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.
 
© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for November 3

November 3 – It’s election day in the U.S., with the corresponding geopolitical uncertainty looking to drive a day of volatile, headline-driven trade. Stock futures are pointing to a mixed open, with the Nasdaq hoping to find some turnaround Tuesday action to stop the bleeding from the recent selloff that has battered the tech sector and drove the index to its lowest close since late July yesterday. The VIX is off its overnight highs but remains elevated, hovering near 20.8 at the time of writing. The dollar is effectively unchanged to start the day, trading at 101.82. Treasury yields are quietly higher after their recent slide that has coincided with the selloff in the equities, particularly tech, potentially signaling some investors fleeing to safe havens, with 2-year yields at 4.585%, 10-year yields at 4.919%, and 30-year yields at 5.294% this morning. Meanwhile, the ags are mostly lower at the break.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for November 2

November 2 – Stocks are looking to bounce back after Friday’s ugly selloff, with the tech heavy Nasdaq showing the sharpest gains after posting the sharpest losses last week. The VIX touched a nearly seven-month high on Friday but has reversed course sharply since, down another 2% to start the day near the 19 level. The dollar touched a one-month low overnight but has recovered since, currently hovering near 101.61. Treasury yields are notably mixed to kick off the week, with 2-year yields up 2-basis points to sit at 4.60%, while 10-year yields are down over 2-basis points to sit at 4.905%, and 30-year yields are down nearly 4-basis points to trade at 5.272%. The ags are largely mixed at the break, with corn and wheat clinging to small gains while soybeans show small losses. It will be interesting to see if more strength will be seen at the open after a massive 1.730 million metric ton (68.1 million bushel) flash sale of U.S. corn to Mexico was just announced, as well as another 136k metric tons (5.0 million bushels) of soybeans to China. Amid the sharp break lower in prices, these are the kind of signals these markets need to see to stop the bleeding.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Mid-Day Commentary for October 30

October 30 – Intel is officially seeing its sharpest one-day drop on record, with its stock currently down nearly 29% as the selling pressure in the tech sector intensifies amid renewed fears of the surging costs associated with the ongoing AI buildout. That selling pressure has spread across global chip stocks, with the Philadelphia Semiconductor Index (SOX) down nearly 7% at the time of writing. A good share of this weakness is likely more of a rotation of money out of tech and into other sectors, however, with the tech heavy Nasdaq seeing the biggest weakness as it falls over 3% on the day to reach its lowest level since early August, though the S&P 500 is down a more modest 1.5% to trade at a roughly six-week low, while the Dow Jones is down only 0.7%, back to where it was trading early last week. The VIX is surging in turn, up over 14% on the day to carve out a new high for the week, currently hovering near 19.7 at midday. The dollar has had a volatile session but now sits up 0.1% on the day to trade at 101.95. Treasury yields remain lower at midday, perhaps reflecting some money leaving the equities space and looking for safe havens, with 2-year yields off 4-basis points to trade at 4.614%, 10-year yields off 3-basis points to trade at 4.956%, and 30-year yields just below unchanged to sit at 5.326%. Crude oil is looking to end the week on a strong note as we head into the weekend market closure with fears of Middle East escalation lingering as Tuesday’s midterm elections arrive, with nearby WTI posting another fresh six-week high today, currently sitting up 1.2% to trade near $104.15, while nearby Brent is up 2.5% to trade near $113.60, its highest level of the week.

Mike Castle
Mike Castle
  • Grains & Oilseeds
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.