Brazil's sugar mix is shifting toward sugar because hydrous ethanol demand has weakened through the year, changing how much of a large cane crop actually becomes exportable sugar. The size of the Center-South crop is only half of the story, since every mill decides how to split its cane between sugar and ethanol, and that decision responds to relative demand rather than to tonnage alone. Strong rains between October and March built the foundation for a good 2026/27 cycle in the Center-South, while later rains in May, June and July complicated the harvest itself. For commercial buyers watching a tightening global balance, the mix is the mechanism that determines how much Brazilian supply offsets losses elsewhere.
Marcelo Bonifacio is a Market Intelligence analyst at StoneX in Campinas, Brazil, where he covers Latin American sugar and ethanol markets and monitors global sugar production and trade flows across Brazil, India and Asia. He tracks the relationship between energy prices and agricultural production, and he follows the Center-South production region whose sugar and ethanol split shapes the international sugar balance.
Key Themes
Heat waves across France, Germany and the United Kingdom have harmed sugar beet development for the 2026/27 crop
Brazil's Center-South cane crop follows strong rains, though wet weather during harvest slows cutting while lifting yields
Weak hydrous ethanol demand points toward a rising sugar mix as cane arrives through September and beyond
Brazil's Center-South Rains Slow the Harvest While Lifting Cane Yields
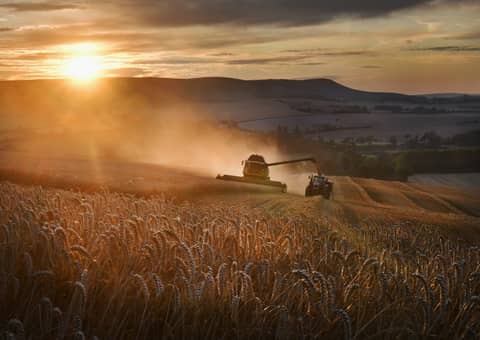
Brazil's Center-South cane crop enters the 2026/27 cycle in good condition, built on strong rains between October and March, yet the rains that continued into May, June and the end of July work against the pace of harvesting. Wet fields stop the machinery and force mills to pause, which pushes cane back rather than removing it, as Bonifacio describes when he explains that "if the machinery is not able to cut all the sugarcane, the mills needs to stop". The same rainfall that interrupts cutting simultaneously improves the cane itself, so the disruption is a timing problem more than a volume problem. Consequently, commercial buyers should read harvest delays in the Center-South as displaced supply rather than lost supply, with the tonnage arriving later in the season. The distinction matters because a delayed crush changes when Brazilian sugar reaches the export program rather than the total that eventually arrives.
Weak hydrous ethanol demand through the year is steering Brazil's Center-South mills toward a higher sugar mix, which increases the share of cane converted into exportable sugar. Cane arriving between July and September, combined with a crop that may extend into December, gives mills an extended window in which to apply that shifted mix. Set against the northern hemisphere picture, where European beet damage, dry weather in Thailand and an India monsoon that left accumulated rainfall near 11% below the normal average all point toward a 2026/27 global deficit of 1.7 million metric tons, Brazil is the region adding supply. That divergence is sharpened by export coverage, since mills that have not yet fixed their sales still have selling to do into the market. According to Bonifacio, "most of the mills in center south are still behind the track for their hedging and for their fixations on exports".
>Make Sugar and Ethanol Insights Your Competitive Advantage
Access live prices, supply and demand data, and actionable market commentary focused on the Sugar and Ethanol sector. Sign up for StoneX Market Intelligence today and see how our Sugar and Ethanol insights can elevate your strategy.
StoneX TV content is created, produced, and distributed solely by StoneX Media Ltd (“StoneX TV”) and is provided for informational and educational purposes only. StoneX TV does not provide investment, financial, legal, or tax advice and does not make any recommendation or endorsement of any investment strategy, transaction, or financial instrument. Nothing in this content constitutes, or should be construed as, investment advice or a recommendation to buy, sell, or hold any financial instrument, including securities, futures, derivatives, digital assets, foreign exchange products, or CFDs. This content does not constitute an offer, invitation, or solicitation to engage in any investment activity. The information presented is general in nature and is not tailored to the financial situation, investment objectives, or risk tolerance of any specific person. You should not rely on this content as a substitute for independent professional advice. Investing and trading in financial instruments involves significant risk of loss and is not suitable for all investors. Past performance is not indicative of future results. Any views or opinions expressed are those of the presenter at the time of publication and are subject to change without notice. Such views may not necessarily reflect those of StoneX Media Ltd or its affiliates. StoneX Media Ltd and its affiliates, including StoneX Group Inc., may from time to time have positions in, or engage in transactions involving, the financial instruments referenced. This content may include general market commentary and opinion. It does not constitute independent investment research and has not been prepared in accordance with legal requirements designed to promote the independence of investment research. StoneX Media Ltd is not authorised or regulated to provide investment services and does not act in a fiduciary capacity. StoneX Media Ltd is incorporated in Ireland and operates in accordance with applicable Irish law. It is a wholly owned subsidiary of StoneX Group Inc. and is a separate legal entity from other subsidiaries within the StoneX Group, which may be regulated in various jurisdictions. StoneX Media Ltd does not act on behalf of, or provide services for, any regulated affiliate. This content is not directed at, and may not be distributed to, any person in any jurisdiction where such distribution would be contrary to local laws or regulations. Supporting documentation for any claims, comparisons, statistics, or technical data may be made available upon reasonable request, where applicable.
Discover more insights
Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.
Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.
Reach
With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.
Transparency
As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.
Expertise
From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.