Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Mid-Day Commentary for October 21

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

October 21 – Stocks remain in the green at midday, still led by the tech heavy Nasdaq (+1.1%), then the S&P 500 (+0.35%), and Dow Jones (+0.2%). The VIX has cooled in turn, hanging near 16.65 at midday, its lowest level of the week. The dollar is trading just above unchanged, near 101.77 at the time of writing. Treasury yields are quietly mixed at midday, with 2-year yields sitting at 4.79%, 10-year yields at 5.11%, and 30-year yields at 5.418%. Crude oil remains in the red, with nearby WTI down 1.3% on the day to trade near $96.90, though nearby Brent is down only 0.1% to trade near $108.70. The ags are largely mixed, with notable gains seen in the cattle complex, particularly feeders, while the wheat complex is down double digits following reports of progress in U.S.-led negotiations between Russia and Ukraine.

Multiple headlines of progress in today’s talks in St. Petersburg are hitting the wires at midday, with Reuters reporting that Russia has accepted the U.S. proposal to resume trilateral talks with Ukraine next month—if this comes to fruition, it would be the first such meeting held since February, a notable step in the right direction. Kremlin aide Yury Ushakov emphasized Russia’s desired framework for peace negotiations focused on “building a security system for Russia and Ukraine after the end of the conflict,” continuing to highlight the implementation of U.S. / Russian economic cooperation. While this is obviously a notable improvement in diplomacy between the two countries after seeing nothing but increasing escalation for months, I would urge caution before concluding that the conflict is truly coming to an end. In referring to Witkoff’s comments to Putin, Ushakov noted “new points in the approaches of the Europeans and Kyiv, although they did not contain much useful in the context of resolving the Ukrainian crisis.” That final portion is what gives me pause, as we’ve yet to see much in the way of actual Russian concessions in the four-and-a-half-plus years of war. This leaves plenty of details to be worked out, though it is still encouraging to see diplomacy resuming—the big question is whether or not this easing of rhetoric translates to an easing of escalations on the ground.

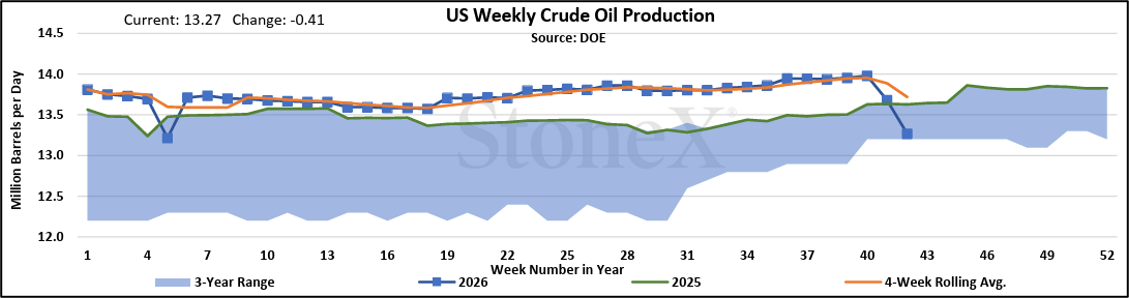
U.S. crude oil stocks excluding the SPR fell 3.06 million barrels week-on-week, much sharper than the average analyst estimate of 0.82 million, pushing total stocks excluding the SPR down to 412.52 million barrels, back to the lowest level seen since late July. The decline was driven primarily by the supply side, with weekly crude oil production falling another 410k barrels per day to 13.269 million barrels per day, the lowest weekly level since the last week of January due largely to the precautionary shutdowns in the U.S. Gulf amid the arrival of Hurricane Isaias. On the demand side, weekly exports fell sharply week-on-week to a four-week low, while refinery utilization fell 0.1% week-on-week to 93.4%. It’s also worth noting that only 300k barrels were pulled from the SPR. Total U.S. crude oil stocks in the SPR now sit at a 44-year low of 282.68 million barrels, but the rate of weekly withdrawal has slowed notably over the last six weeks.

On the refined products, U.S. gasoline stocks saw a weekly draw of 2.95 million barrels, much sharper than the average estimate of 0.443 million, bringing total U.S. gasoline stocks to 205.31 million barrels. Despite weekly production rebounding by over 500k barrels per day, a halving of imports and uptick in exports drove the draw. Conversely, U.S. distillate stocks saw a 1.68-million-barrel weekly build, reversing course from the expected 1.162-million-barrel draw. Interestingly, the build in distillate stocks was driven largely by a 585k barrel per day drop in implied demand, pushing weekly distillate demand to its lowest level in nearly four months.

USDA reported daily flash soybean sales for the sixth business day in a row this morning, the longest such streak in three years. Today’s total was 299k metric tons (11.0 million bushels) of 2026/27 soybeans, a solid amount, but the real surprise was the addition of a destination other than China. Of today’s total, Spain accounted for 165k metric tons (6.1 mbu) while China accounted for the remaining 134k metric tons (4.9 mbu). That’s the first time seeing a destination other than China or unknown in a daily soybean flash sale since Mexico’s appearance back in July. Total U.S. soybean flash sales since last Wednesday now sit at 3.163 million metric tons (116.2 mbu), the largest for any week since November 2023, with the vast majority of that total destined for China. Even with these massive purchase commitments, however, soybean prices continue to extend their decline amid an ideal start to Brazil’s growing season, improvement in U.S. harvest progress, and the weak start to 2026/27 domestic crush. Outside selling pressure is likely taking its toll as well, potentially a sign of managed money length heading for the exit, particularly with headlines of potential peace coming to fruition between Russia and Ukraine, though I would again exercise caution with believing the words before seeing change in the actions on the ground.  

image 139402

  • Grains & Oilseeds

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.
Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Mid-Day Commentary for October 23

October 23 – Stocks are mixed at midday amid a volatile session, with the Nasdaq (+0.3%) in the green but the S&P 500 (-0.2%) and Dow Jones (-1.0%) both in the red. The VIX has come well off its morning high of 20.66 but remains up on the day, hovering near 19.6 at the time of writing. The dollar is modestly higher, now trading near 101.82. Treasury yields are bouncing after yesterday’s sharp decline, with 2-year yields up 5-basis points on the day to sit at 4.686%, 10-year yields up just under 4-basis points to sit at 4.99%, and 30-year yields up 3-basis points to trade at 5.315%. Crude oil prices continue to work higher through the session on increasing rumblings of a potential resumption in U.S./Israeli strikes on Iran over the weekend with markets closed, with Israeli elections set for next Tuesday (10/27) and the U.S. midterm elections the following Tuesday (11/3). Nearby WTI is now up 3.9% on the day to trade at $102.90, a five-week high, while nearby Brent is up 2.8% on the day to trade at $116.30, now a seven-month high and not far from the previous highest levels seen early in the conflict. The ags remain largely mixed at midday, with the biggest headline being the announcement of a ceasefire in the Ukrainian city of Oleshky, a frontline city in the country’s south across the Dnipro River from Kherson that has become a humanitarian catastrophe with civilians effectively cut off from aid due to the ongoing fighting, set to begin next Thursday (10/29). The agreement is another indication that Washington, Moscow, and Kyiv are still capable of reaching narrow tactical agreements despite continued fighting elsewhere. That's incrementally positive for diplomacy and another welcomed sign of momentum in working towards peace, but by itself it doesn't materially alter the military situation, sanctions outlook, Black Sea shipping security environment, or expectations for a wider peace settlement.

Mike Castle
Mike Castle
  • Grains & Oilseeds

Perspective: Morning Commentary for October 23

October 23 – The tech heavy Nasdaq saw its worst day since June yesterday, closing 2.9% lower, with concerns regarding the sustainability of the ongoing AI buildout in the backdrop of rising borrowing costs and increasing sovereign debt driving investors into safe havens, as evidenced by the surge in buying in the bond markets. Stock futures are pointing to a lower open again today, though Nasdaq futures are showing the smallest losses among the major indexes, a potential sign of an easing of selling pressure in the tech sector. The VIX is up 6% to start the day, trading just below 20.2 at the time of writing, hovering near its highest level since last Friday. The dollar is looking at a quiet start to the day after a largely quiet week, sitting just above unchanged near 101.68. Treasury yields are modestly higher this morning after falling notably this week, with 2-year yields at 4.66%, 10-year yields at 4.97%, and 30-year yields just above 5.29%. Crude oil prices are on the rise as the market rebuilds geopolitical risk premium amid escalatory rhetoric from the U.S. / Israel and Iran, raising fears of renewed and potentially even more intense back-and-forth strikes. Nearby WTI is up 2.5% to start the day, carving out a fresh five-week high of $101.60 at the time of writing, while nearby Brent is up another 1.35% on the day to trade near $114.70, nearing a six-month high. Meanwhile, the ags are looking at a quietly mixed open.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Morning Grain Comments 10-23

Morning Grain Market Comments - Matt Zeller

Matt Zeller
Matt Zeller
  • Grains & Oilseeds
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.