Soft Commodities in Focus: Coffee, Sugar, Cocoa & Cotton Feel the Climate-and-Economy Squeeze in Q3 2025
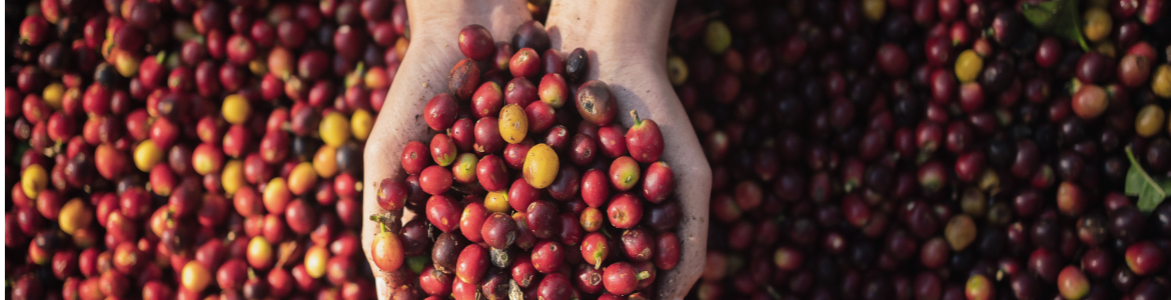
Although the balance between supply and demand in coffee is tight, Brazil’s advancing harvest, a larger robusta crop, and expectations for Vietnam’s output recovery should keep prices pressured through the third quarter. In raw sugar, the progress of Brazil’s Centre-South crush will be pivotal; futures are already hovering near four-year lows. Cocoa continues to trade at historic highs, reflecting a disappointing West African crop that is delaying any meaningful rebuilding of global stocks.
Below is a condensed version of our soft-commodity analysis—coffee, sugar, cocoa and cotton—drawn from the 32nd quarterly Commodities Outlook covering July-September 2025. Click below to download the full report, including StoneX Market Intelligence on agricultural, energy, metals and currency markets.
Read the full analysis
Sugar
- Raw-sugar prices hit four-year lows, slipping below US¢ 17 / lb.
- Elevated consumer-country inventories curb import demand.
- Asian production points to a global surplus in 2025/26.
- A rebound in imports and firmer white-sugar demand could lend support later.
Raw-sugar futures in New York fell to a four-year trough in May 2025, weighed down by sluggish physical demand and a benign medium-term supply outlook. While the 2024/25 international cycle still shows a supply-demand deficit, short-term structural factors are driving a bearish tone.
“Record-high Brazilian exports in 2024 left buyers such as China, Indonesia and the UAE sitting on ample stocks, sharply reducing import needs in H1 2025,” explains Marcelo Di Bonifácio Filho, Market Intelligence Analyst at StoneX.
Center-South Brazil is expected to crush close to 600 million t in 2025/26, and mills are likely to devote more than 50 % of cane to sugar. At the same time, early monsoons in India have lifted production estimates to 32.3 million tonnes—up over 6 million tonnes year-on-year. StoneX now sees a 3.7 million tonnes global surplus in 2025/26. Even so, the eventual return of import demand and tighter EU availability, together with stronger white-sugar offtake in West Africa, could stabilize prices in the months ahead.
Coffee
- Coffee futures eased in Q2 2025 as Brazil’s harvest gained pace.
- Robust robusta output offsets a smaller Arabica crop; harvest is past 88%.
- Global demand feels the squeeze from inflation.
- Weather risks and new US import tariffs add volatility.
After rallying into Q1, coffee futures retreated through Q2 2025, notably from May onwards, as Brazil’s harvest tempered immediate supply fears.
“Robusta harvesting surpassed 88 % by mid-July, offering the physical market a temporary cushion,” notes Fernando Maximiliano, Coffee Market Intelligence Manager at StoneX.
Despite a 13.5 % drop in arabica to 38.7 million bags, a nearly 22 % jump in robusta to 25.8 million bags softens the blow. Yet inflation and a near-16 % slide in Brazilian domestic consumption (ABIC data for April) remain red flags. Vietnam is also set for a larger 2025/26 crop, amplifying pressure on robusta later in the year, while ICE’s green-light for big-bag storage could alter certified-stock dynamics.
The USDA projects a hefty 9-million-bag world surplus, but StoneX’s own fieldwork points to a far tighter balance. Q3 data releases—especially our in-depth Brazil survey—will be critical in refining supply-demand estimates amid weather and trade-policy uncertainty.
Cocoa
- Cocoa prices stay near historic highs in 2025 after West African crop failures.
- Another global deficit looms for 2024/25.
- Output is rising in Ecuador, Indonesia and Nigeria; demand shows early signs of cooling.
- The 2025/26 outcome hinges on weather and the pace of forward sales from Ivory Coast and Ghana.
Front-month cocoa remains elevated in early-2025, a direct consequence of severe production shortfalls in Ghana and Ivory Coast. Hopes for a rebound in 2024/25 have faded as harvest pace slowed.
“Persistent high prices signal market concern over a possible fourth consecutive global deficit,” says Rafael Borges, StoneX Market Intelligence Analyst.
Growth in emerging producers and softer demand—partly a response to expensive beans—are capping the upside. StoneX currently anticipates a slight 2024/25 surplus, easing some of the tension, although grind data still surprise on the high side. All eyes now turn to the 2025/26 development window (April-September). Average rainfall in key zones supports cautious optimism, but slower export-license issuance by the Ivorian and Ghanaian boards has heightened price risk. US import tariffs on cocoa products add another layer of demand uncertainty.
Cotton
- Prices remain range-bound amid neutral fundamentals and elevated uncertainty.
- Heavy supplies and speculative shorts have kept futures near US¢ 65–70 / lb since April 2024.
- USDA pegs global stocks at 16.8 million t (+4.8 % y/y) for 2024/25.
- Brazil cements itself as top exporter; US exports face headwinds from the US-China trade rift.
- Macro outlook is pivotal—high US rates weigh on textile consumption.
Cotton prices spent most of 2025 trading sideways as abundant stocks, tempered global demand and geopolitical jitters formed a “perfect storm,” explains Raphael Bulascoschi, StoneX Market Intelligence Analyst.
US plantings are down 8.7 % for 2025/26, but average yields could keep output steady. Storm threats and abandonment rates, however, remain swing factors. China’s growing self-reliance and preference for Brazilian fiber—on track for another record 3.85 million t crop—challenge US export prospects, while political and currency turmoil in key importers (Bangladesh, Vietnam, Pakistan) clouds demand.
Ultimately, the trajectory of global growth will decide the market’s next move: the Federal Reserve’s cautious stance on rate cuts curbs textile spending, keeping a lid on cotton demand. Weather updates, trade policy shifts and macro data will guide price action through the remainder of 2025.
Download the full report
StoneX TV content is created, produced, and distributed solely by StoneX Media Ltd (“StoneX TV”) and is provided for informational and educational purposes only. StoneX TV does not provide investment, financial, legal, or tax advice and does not make any recommendation or endorsement of any investment strategy, transaction, or financial instrument. Nothing in this content constitutes, or should be construed as, investment advice or a recommendation to buy, sell, or hold any financial instrument, including securities, futures, derivatives, digital assets, foreign exchange products, or CFDs. This content does not constitute an offer, invitation, or solicitation to engage in any investment activity. The information presented is general in nature and is not tailored to the financial situation, investment objectives, or risk tolerance of any specific person. You should not rely on this content as a substitute for independent professional advice. Investing and trading in financial instruments involves significant risk of loss and is not suitable for all investors. Past performance is not indicative of future results. Any views or opinions expressed are those of the presenter at the time of publication and are subject to change without notice. Such views may not necessarily reflect those of StoneX Media Ltd or its affiliates. StoneX Media Ltd and its affiliates, including StoneX Group Inc., may from time to time have positions in, or engage in transactions involving, the financial instruments referenced. This content may include general market commentary and opinion. It does not constitute independent investment research and has not been prepared in accordance with legal requirements designed to promote the independence of investment research. StoneX Media Ltd is not authorised or regulated to provide investment services and does not act in a fiduciary capacity. StoneX Media Ltd is incorporated in Ireland and operates in accordance with applicable Irish law. It is a wholly owned subsidiary of StoneX Group Inc. and is a separate legal entity from other subsidiaries within the StoneX Group, which may be regulated in various jurisdictions. StoneX Media Ltd does not act on behalf of, or provide services for, any regulated affiliate. This content is not directed at, and may not be distributed to, any person in any jurisdiction where such distribution would be contrary to local laws or regulations. Supporting documentation for any claims, comparisons, statistics, or technical data may be made available upon reasonable request, where applicable.