Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for November 13

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

November 13 – Stock futures are pointing to a cautiously higher open as producer level inflation again accelerates to multi-year highs in October, albeit less than feared. The VIX is cooling to start the day, off roughly 3.7% to trade right at 18 at the time of writing. The dollar is quietly higher, touching another fresh 19-month high overnight and hovering near 103.21 at present. Treasury yields are just above unchanged at the front-end of the curve but more elevated at the long-end, with 2-year yields sitting at 4.865% while 10-year and 30-year yields are both up just above 4-basis points each to trade at 5.145% and 5.475%, respectively. Crude oil prices are also quietly higher, with nearby WTI up 0.5% on the day to trade near $89.10 and nearby Brent up 0.9% to trade near $96.70. The ags are mostly higher overnight amid a fresh reality check on the commodity fundamental impact of the Russian/Ukrainian war after headlines of ongoing negotiations dominated earlier in the week.

Russian strikes this week have taken two Ukrainian sunflower oil plants offline, bringing the conflict’s ties to the edible oil complex back into focus. One of the plants belongs to Kernel, the world’s largest sunflower oil producer and exporter, which has previously suspended operations due to Russian strikes earlier this year. The loss of sunflower oil movement via the Black Sea forces major buyers, namely the world’s top buyer, India, back into the market for alternative supply, mostly palm and soybean oil. What’s worth noting is that part of the issue here is the degradation of power infrastructure within Ukraine, which has been a major focus of Russia’s air campaign this fall and has the potential for broader downstream impact than simply strikes on individual facilities. Outside of the edible oil space, Ukraine’s Agriculture Ministry reported their cumulative grain exports in the 2026/27 marketing year reaching 7.125 million metric tons, down 32.9% year-over-year, with wheat exports of 4.111 million metric tons down 38.7%, highlighting the ongoing disruptions to commodity flow from the region.

On the Russian side, cumulative seaborne grain exports for the 2026/27 marketing year have reached 8.96 million metric tons through October, down 53.5% year-over-year. Shipments via the Black Sea have become almost nonexistent, with these volumes being maintained entirely by increases from alternate routes, with the Baltic Sea being the largest. The reason I point that out is Ukraine has demonstrated their ability to threaten Russia’s Baltic Sea fleet this week, carrying out a successful strike on a Russian warship in the Gulf of Finland. We also saw a Ukrainian strike on energy export infrastructure in the Russian Baltic Sea port of Ust-Luga, not targeting grain infrastructure but again demonstrating their ability to do so. Elsewhere, Ukraine reported striking one of Russia’s largest oil refineries in the Volgograd region overnight. While headlines regarding this week’s ongoing diplomatic push and multiple rounds of negotiations have driven commodities lower, we’re clearly still not seeing a de-escalation on the ground.

Speaking of those negotiations, U.S. envoys Jared Kushner and Steve Witkoff met with Ukrainian President Zelenskyy yesterday, wrapping up a week that started with trilateral talks in the U.A.E., then a direct meeting with President Putin in Moscow. The most notable takeaway from this meeting was the announcement that both Russia and Ukraine had agreed to expand negotiations to include European representatives. The potential inclusion of European governments is noteworthy because it creates a more comprehensive negotiating framework for post-war security—however, it also introduces additional parties with differing security priorities, potentially complicating negotiations. Zelenskyy welcomed the development, although Russian officials have offered more skepticism regarding Europe's involvement, while their signaled unwillingness to compromise on their territorial demands make it hard for me to see a meaningful resolution being imminent. From a commodity market perspective, one of the most notable quotes that caught my eye was Kushner’s comments suggesting the talks are increasingly focused on securing a comprehensive peace agreement rather than pursuing narrower, standalone arrangements like the previous Black Sea Grain Initiative or target-specific ceasefires, stating: “apart from humanitarian measures, nothing will be finalized until a comprehensive agreement is reached.” While I remain skeptical that a meaningful improvement to commodity flow is imminent, this week’s resumption of diplomacy is still a major improvement from what has been seen through the vast majority of 2026, with both sides agreeing to continue broader talks moving forward.

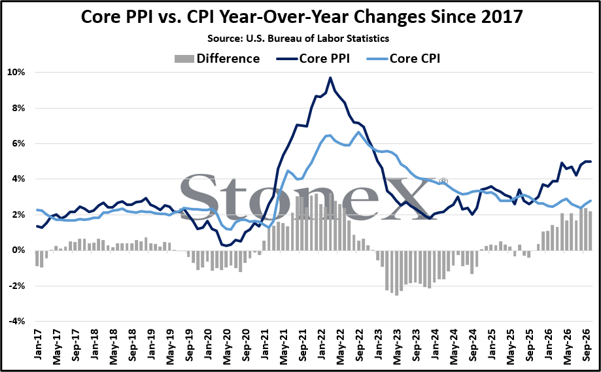
Headline PPI inflation accelerated to a 6.5% year-over-year increase in October, up from the 6.3% seen in September and marking the sharpest rate of increase since November 2022; in month-on-month terms, this was a 0.3% uptick. On a positive note, however, these both came in 0.1% below their average analyst estimates. Removing the more volatile energy and food sectors, core PPI accelerated 0.3% month-on-month and 5.0% year-over-year in October, both matching expectations. That year-over-year figure matched September as the hottest rise in core inflation since January 2023. It goes without saying, no matter how you look at this, we are still sharply above the Fed’s 2.0% mandate with no indication of working lower. However, it’s worth noting one other positive takeaway here which was the narrowing of the spread between core PPI and CPI, cooling back to 2.2%, its lowest level since July. We’ve been following closely the ongoing buildup of inflationary pressures held increasingly at the producer level, with the biggest question being how much of this is ultimately passed through to the consumer. Without official year-over-year CPI figures for October published due to last year’s government shutdown, the implied 4.0% headline and 2.8% core year-over-year increases would both represent meaningful accelerations and five-month highs, indicating this pass-through, but the lack of further acceleration at the producer level could be an early indication of some of the worst pressures easing. Obviously, that remains to be seen in the months ahead and there is still a significant amount of inflation already in the pipeline, but coming in below expectations is certainly a welcomed development for a market already on edge about increasingly hawkish Fed expectations.

image 140545

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for November 13

November 13 – Stock futures are pointing to a cautiously higher open as producer level inflation again accelerates to multi-year highs in October, albeit less than feared. The VIX is cooling to start the day, off roughly 3.7% to trade right at 18 at the time of writing. The dollar is quietly higher, touching another fresh 19-month high overnight and hovering near 103.21 at present. Treasury yields are just above unchanged at the front-end of the curve but more elevated at the long-end, with 2-year yields sitting at 4.865% while 10-year and 30-year yields are both up just above 4-basis points each to trade at 5.145% and 5.475%, respectively. Crude oil prices are also quietly higher, with nearby WTI up 0.5% on the day to trade near $89.10 and nearby Brent up 0.9% to trade near $96.70. The ags are mostly higher overnight amid a fresh reality check on the commodity fundamental impact of the Russian/Ukrainian war after headlines of ongoing negotiations dominated earlier in the week.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Farm Policy Moves to Democrats and Farm Aid Eligibility Takes Focus

Democratic control of Congress moves farm policy into committees that can reconsider how farm aid eligibility is defined. Beneath the food stamp dispute holding up the farm bill, provisions on biofuels and animal welfare already draw support from both parties.

Editorial Team
Editorial Team
  • Grains & Oilseeds

WASDE Corn Yield Falls as Argentina and Brazil Largely Fill the Gap

The WASDE cut to the U.S. corn yield sparked a grain rally, yet larger crops in Argentina and Brazil absorbed most of the loss. The full report also lifted global corn stocks and trimmed EU import estimates that the market treated with doubt.

Editorial Team
Editorial Team
  • Grains & Oilseeds
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve, our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.