Higher for longer: How energy costs are rippling through grain and dairy
Key Takeaways:
- Diesel prices may stay elevated for some time, with forward prices sitting near the top of their four-year range
- Biofuel policy at home and abroad is turning soybeans and corn into energy crops, creating a rare source of demand growth
- Higher energy costs are squeezing dairy margins, but natural gas could be the bigger exposure for businesses in 2027
Diesel looks set to stay higher for longer
StoneX relaunched its Commodity Insights webinar series on October 7 with a fireside chat on a question that matters to almost every business that makes or moves something: how far do energy prices reach into food and agriculture? Dan Conrath, Senior Market Analyst for energy, opened the discussion with a reminder of how quickly the picture has changed.
Wholesale diesel in New York Harbor started the year at roughly $2 a gallon before spiking to $5, a move that topped even the 2022 peak. Conrath pointed to two conflicts as the cause. The Russia-Ukraine war is now in its fifth year, and while crude flows from the Middle East are recovering, refined products are not. Shipping costs tell part of the story. Moving a tanker through the Strait of Hormuz cost around $60,000 a day a year ago. It now costs about $1.3 million.
Forward prices for the next six months sit between $4.20 and $4.50, which Conrath placed around the 90th decile of the past four years. For context, the midpoint over that period has been roughly $2.80 to $3. He expects some easing in the first half of 2027 as higher prices dampen demand, but the need to refill strategic petroleum reserves around the world could add 2 to 3 million barrels a day of demand once the conflict ends. “The idea that we’re going to go back to the old days” looks unlikely, he said.
He also offered a word of caution for procurement teams. Locking in fuel surcharges at the 80th or 90th decile protects against further spikes, but if a geopolitical resolution pulls prices lower, that hedge can leave a business at a cost disadvantage to its competitors.
Supply losses from two wars have pushed diesel into the 'fear' phase of its commodity cycle.
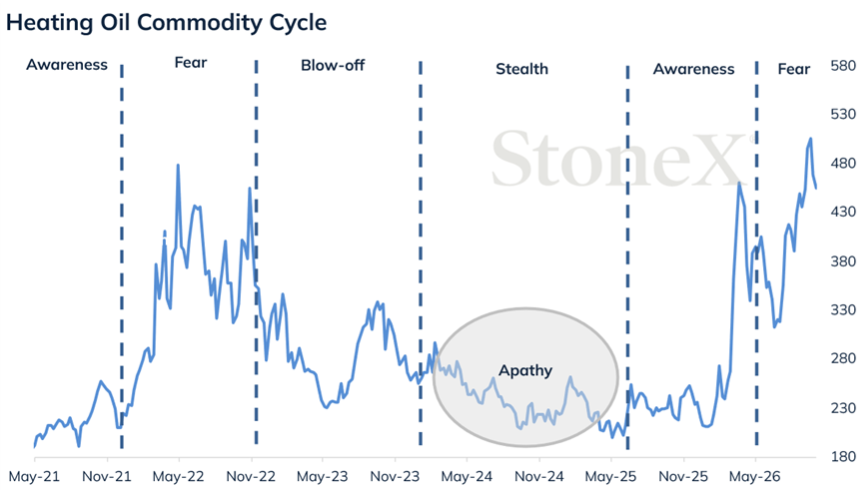
Source: Dan Conrath, StoneX Market Intelligence
Farmers are absorbing the cost
Mike Castle, Senior Commodities Analyst, explained why the grain sector feels this pain more directly than most. Diesel demand on the farm is almost completely inelastic. With harvest already running late, “farmers aren’t just going to let their crops rot in the field because diesel prices are too high.”
The backdrop is tight. Distillate inventories are the lowest they have ever been for this point in the year, and Castle described the situation as largely a refining capacity story. A planned 50 million barrel release of diesel reserves is a meaningful step, but those barrels take time to reach the pump. An outage at the Joliet refinery during harvest pushed Midwest diesel prices to record highs.
The result is that it now takes far more bushels of corn to buy a gallon of diesel than at any point in the past decade, at levels last seen around 20 years ago. Most of that cost is being absorbed by producers. The panel stressed that this is a margin story for farmers, not a signal that food prices will automatically follow. Since farmers will use the same amount of diesel whether it costs $2 or $6 a gallon, they have little ability to pass the cost on.
It now takes more bushels of corn to buy a gallon of Midwest diesel than at any point in the past decade.
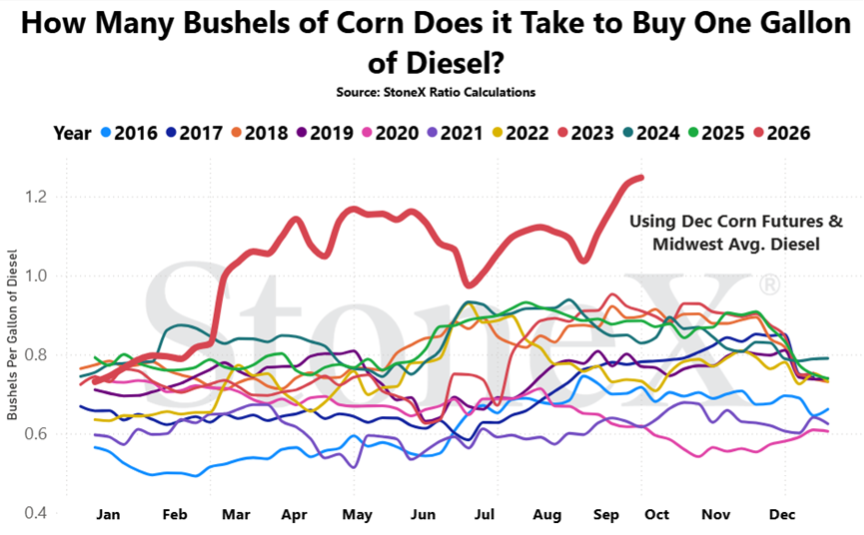
Source: Mike Castle, StoneX ratio calculations
Biofuels are turning grains into energy crops
While high energy prices hurt producers in the short term, Castle sees a much bigger long-term effect on demand. “Soybeans are becoming more and more an energy crop,” he said. The 2026/27 marketing year will be the first in history in which biofuel is the largest use of U.S. soybean oil, ahead of food. Soybean crush is on track for another record, and more than 60% of U.S. soybean demand is now processed domestically rather than exported.
That support extends across the edible oils complex, from palm to sunflower oil. Russia’s delayed sunflower oil shipments to India, announced on the day of the webinar, are pushing buyers toward alternatives.
Corn is following a similar path, led by Brazil. Over the past five years, the share of Brazil’s corn crop used for ethanol has grown from roughly 10% to more than 25%. Brazil moved to E30 in 2025, raised that to E32 after the Middle East conflict began, and is already testing E35. As Brazil keeps more corn at home, U.S. exporters stand to pick up demand from their largest competitor. India and Southeast Asia are moving in the same direction.
Weather adds another layer. Castle noted that a record El Niño for this time of year could affect production in India, Southeast Asia and Brazil into 2027. Brazil’s soybean crop looks healthy so far, but its 2027 corn crop is a risk to watch from early next year. With a stronger demand base in place, any supply shortfall matters that much more.
On the question of biofuel policy risk, Castle said he would not give it much weight today. The panel pointed to growing bipartisan support, including unanimous votes for year-round E15 in both California and Nebraska.
Brazil now uses more than a quarter of its corn crop for ethanol, up from about 10% five years ago.
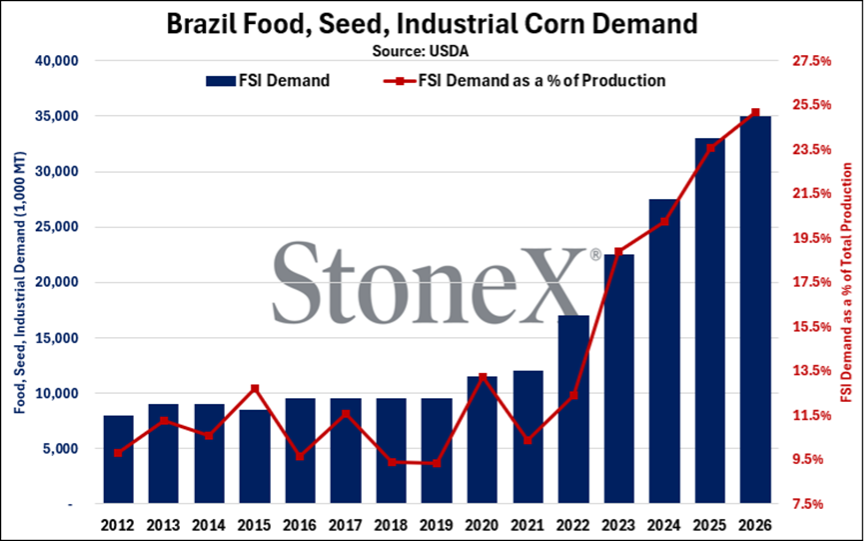
Source: Mike Castle, StoneX, USDA
Dairy feels the squeeze, but supply is holding up
Nate Donnay, Director of Dairy Market Insight, drew a clear line between sentiment and economics. Dairy farmers are seeing fuel surcharges on milk hauling, feed deliveries and even fuel deliveries. Yet energy accounts for only about 3% to 4% of the total cost of producing milk.
By Donnay’s estimates, higher electricity, hauling and feed surcharge costs add roughly 45 to 60 cents per hundredweight this year. With farm-level milk prices running around $21 to $25 per hundredweight, that is a 2% to 3% increase. “It’s noticeable,” he said, but not enough to shift overall supply.
The bigger forces in dairy are elsewhere. Cheese and butter prices are near their lowest levels in a couple of years. Butter production has grown about 8% across the U.S. and Europe, and record investment in cheese plants has pushed more product into export markets. At the same time, rising demand for protein, driven by GLP-1 medications, an aging population and social media trends, is supporting prices for whey protein and other protein-rich ingredients.
The U.S. dairy herd has grown by 388,000 cows over the past two years, the largest two-year expansion on record. Revenue from selling beef-cross calves and cull cows has grown from about 5% of dairy farm revenue to 20% to 25%, helping keep operations profitable. Despite tighter margins, Donnay expects the herd to keep growing, though at a slower pace.
Natural gas could be next year’s bigger risk
Responding to audience questions, Conrath turned to natural gas, which has stayed below $3 even as diesel climbed 80% to 100%. For many businesses, that stability has kept overall energy budgets on track this year. He doesn’t expect that to last.
Production is rising, but demand may rise faster. Gas demand from data centers is expected to grow by as much as 15 Bcf a day through 2035, and the U.S. accounts for nearly half of the LNG export capacity being built worldwide over the next three to five years. Forecasts point to a warmer winter, but Conrath cautioned that strong El Niño years have a way of upending expectations. Taken together, he sees upside risk for natural gas prices in 2027.
The common thread across all three markets is how connected they are. Energy shapes grain demand through biofuels, grain shapes dairy through feed, and beef markets are changing how dairy farms operate. For buyers and investors planning for 2027, the panel’s message was to prepare for a higher-for-longer price environment, with risks that don’t always show up where you would expect.
Watch the full webinar
Hear the complete discussion, including the panel’s answers to audience questions, in the full Commodity Insights webinar recording.
Watch the Recording
—- Experts: Dan Conrath, StoneX Senior Market Analyst, Mike Castle, StoneX Senior Commodities Economist, Nate Donnay, StoneX Director of Dairy Market Insight
The trading of derivatives such as futures, options, and over-the-counter (OTC) products or “swaps” may not be suitable for all investors. Derivatives trading involves substantial risk of loss. Past results are not necessarily indicative of future results. Futures and Options on Futures trading services are provided by the FCM Division of StoneX Financial Inc (“SFI”) (NFA ID: 0476094). Over-the-counter (“OTC”) products or swaps trading services are available through StoneX Markets LLC (“SXM”) (NFA ID: 0449652). SXM products are intended to be traded only by individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ (“ECP”) and who have been accepted as customers of SXM. SFI and SXM are wholly owned subsidiaries of StoneX Group Inc.
Reproduction or use in any format without authorization is forbidden. © Copyright 2026. All rights reserved.