Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for October 28

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

October 28 – Stock futures are pointing to a mostly higher open, led by the tech heavy Nasdaq as it attempts to add to impressive early week gains, with big earnings reports on deck after today’s close from both Microsoft and Google parent Alphabet, followed by Amazon tomorrow, and Apple next Monday (11/2). The VIX is starting the day slightly below yesterday’s close, hovering near 17.4 at the time of writing. The dollar is losing some steam after back-to-back days of sharp gains to start the week, trading just below the 102.34 mark after touching a fresh two-week high near 102.5 overnight. Treasury yields are off to a quietly mixed start, with 2-year yields up slightly to 4.743%, 10-year yields unchanged at 4.993%, and 30-year yields slightly lower to sit at 5.30%. The ags are mostly looking at a quietly higher open, looking to find their footing after an ugly selloff to start the week.

Crude oil prices are pushing higher this morning amid continued rumblings of renewed U.S. / Israeli military action after next week’s midterm elections, with nearby WTI up 1.6% to trade near $101.80 and nearby Brent up 1.7% to trade near $111.25 at the time of writing. The push for diplomacy has continued this week with officials from Saudi Arabia, Turkey, and Pakistan all in Tehran this week, while Qatari mediators have reportedly presented fresh proposals to bring gradual de-escalation to the conflict. However, Iranian officials have cast doubt on hopes for meaningful progress, stating Qatar had presented “unacceptable ideas and not an offer.” Meanwhile, Israel's election appears unlikely to produce an immediate shift in regional policy, as preliminary results point to political deadlock and potentially lengthy coalition negotiations. While the final government composition remains unclear, both major camps broadly support a hard security posture toward Iran and its allied militant groups, suggesting limited near-term changes to Israel's regional strategy. The election therefore does little to reduce current geopolitical risk premiums in energy markets, with investors likely to remain focused on developments involving Iran, the Houthis, Gulf energy infrastructure, and ongoing military operations rather than on Israeli domestic politics. To that end, the Houthis today called for an immediate evacuation of the Aden airport today as the fighting within Yemen continues to intensify, keeping that flashpoint squarely in focus. Attention now turns to next Tuesday’s U.S. midterm elections and whether the current threats of renewed military action in the days following come to fruition, or prove to be more positioning for ongoing negotiations.

The tech sector got a fresh boost of optimism from yesterday’s blowout earnings results from South Korea’s SK Hynix, whose operating profit rose an eye-popping 632% year-over-year, sending their own stock and the broader South Korean KOSPI index sharply higher and leading Nasdaq futures into the green to start the day. Apart from the blowout earnings figures themselves, the company noted that both their DRAM and HBM capacity is completely sold out through 2029, highlighting the red hot demand in the sector amid the ongoing AI buildout. They predicted that global memory shortages driven by AI data center expansions will persist until at least 2030, reinforcing the view that AI-related semiconductor demand remains supply constrained rather than demand constrained. Against that backdrop, today's earnings from Microsoft and Alphabet take on added importance, as investors look for confirmation that hyperscaler cloud growth and AI monetization are accelerating fast enough to justify the continued massive spending on data centers, GPUs, and memory. While SK Hynix’s results are clearly supportive of the broader AI trade and suggest demand for AI infrastructure remains robust, the key question for the market has shifted from whether companies are spending on AI to whether that spending is generating measurable revenue and profit growth, making cloud demand, AI-related revenue commentary, and 2027 capital expenditure guidance the critical metrics to watch from today’s reports.

Average 30-year mortgage rates in the U.S. fell to 7.37% in the week ending October 23, the second consecutive weekly decline after seeing an eight-week stretch of weekly increases that added nearly 75-basis points to push mortgage rates to a three-year high. This led to the first rise in mortgage applications in eight weeks, up 3.4% week-on-week, the largest weekly rise since early August. Rebounds were seen in both new purchase applications, up 3.8% week-on-week, and refinancing applications, up 2.7% week-on-week. Both remain near multi-year lows, but the housing market will happily take any reprieve it can get at this point.

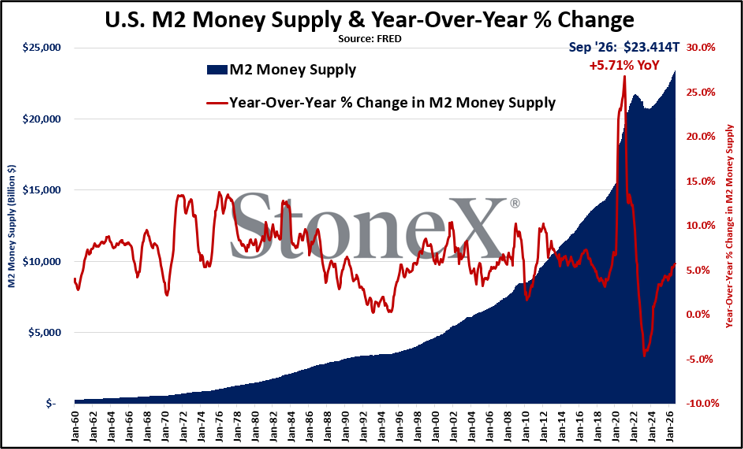
U.S. M2 money supply rose 0.48% month-on-month to another fresh all-time high of $23.414T in September, marking the 17th consecutive month of new record highs, an underappreciated macro development. After serving as a significant headwind to liquidity conditions during the Fed's tightening cycle, broad money is once again expanding on a year-over-year basis, with September’s 5.71% year-over-year rise marking the fastest pace of acceleration since May 2022. A sustained recovery in broad money growth is not an immediate inflation catalyst but historically has been associated with firmer nominal demand and upward pressure on prices over time—look no further than our recent post-pandemic bout. While this reacceleration does not guarantee a return of inflation, it does suggest the powerful monetary drag that helped cool price pressures over the last few years is gradually fading. Add this into an already loaded inflation pipeline at the producer level, and the combination of rising input costs and expanding liquidity raises the risk that today's producer-price pressures ultimately find their way into broader consumer prices.

image 139762

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.
Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for October 28

October 28 – Stock futures are pointing to a mostly higher open, led by the tech heavy Nasdaq as it attempts to add to impressive early week gains, with big earnings reports on deck after today’s close from both Microsoft and Google parent Alphabet, followed by Amazon tomorrow, and Apple next Monday (11/2). The VIX is starting the day slightly below yesterday’s close, hovering near 17.4 at the time of writing. The dollar is losing some steam after back-to-back days of sharp gains to start the week, trading just below the 102.34 mark after touching a fresh two-week high near 102.5 overnight. Treasury yields are off to a quietly mixed start, with 2-year yields up slightly to 4.743%, 10-year yields unchanged at 4.993%, and 30-year yields slightly lower to sit at 5.30%. The ags are mostly looking at a quietly higher open, looking to find their footing after an ugly selloff to start the week.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

USDA's Corn Calculation Error Deepens Doubts Over Crop Report Data

A minor USDA correction to its corn yield math barely moved futures, but it landed on a market already wary of the agency's numbers. Extreme yield swings, conflicting crop signals and talk of budget cuts are reshaping how grain producers and traders read federal crop reports.

Editorial Team
Editorial Team
  • Grains & Oilseeds

Perspective: Morning Commentary for October 27

October 27 – The Fed’s October meeting kicks off today, though CME’s FedWatch currently shows 90%+ odds of the FOMC holding rates steady this week, with the next 25-basis point hike seen at the December meeting. With that said, the bigger intrigue will likely come from Fed Chair Kevin Warsh’s press conference tomorrow afternoon as traders parse through his comments to shape expectations for the Fed’s path forward. Meanwhile, stock futures are pointing to a positive open, looking to add to yesterday’s gains. The VIX is falling again, off roughly 3% on the day to hang near 17.8 at the time of writing. The dollar is looking to add to yesterday’s gains as well, up just over 0.1% to trade at a nearly two-week high around the 102.15 level. Treasury yields are quietly mixed to start the day, with 2-year yields slightly higher to trade at 4.714%, while long-term yields are slightly lower, with 10-year yields at 4.98% and 30-year yields at 5.292%. Crude oil prices are quietly lower, with nearby WTI down 0.4% on the day, trading near $100.80 and nearby Brent down 0.6%, trading near $110.10. The ags are mixed to start the day, with soybeans looking to rebound after yesterday’s knee-jerk selloff in response to the unexpected re-election of Brazilian President Lula and subsequent selloff in the Brazilian Real, which is also looking to rebound this morning.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.