
FX Weekly Overview (Brazil Issue)
Dollar to reflect Brazilian electoral scenario, Copom minutes, RPM, IPCA-15, and expectations of higher interest rates in the US
Leonel Mattos
- Currencies
By: Leonel Mattos, Market Intelligence Analyst • BRAZIL PRS
USDBRL and Dollar Index (points)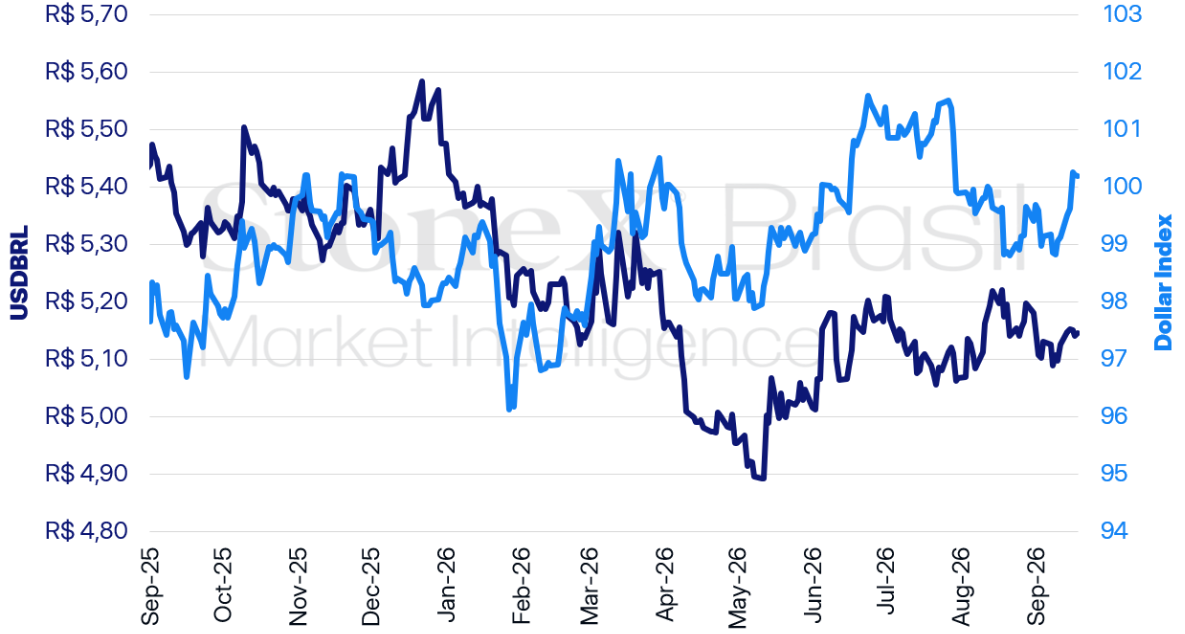
USDBRL variations | Daily: -0.18% | Weekly: +0.32% | Monthly: -0.77% | Yearly: -6.12% | In 12 months: -3.02%
Dollar index variations | Daily: -0.05% | Weekly: +1.08% | Monthly: +0.79% | Yearly: +1.91% | In 12 months: +3.35%
Investors should react to the presidential election intention polls, calibrating their expectations for the election results and economic policy management over the next four years.
Why this matters: A tight electoral race could reduce predictability regarding Brazilian economic policies for the next four years, increasing the perception of risks for domestic assets, amplifying volatility, and harming the performance of the Brazilian real.
Recent polls: Last Thursday (17), Datafolha revealed that intentions to vote for president in a potential second round remained stable, with 46% of the intentions for Lula and 44% for Flavio Bolsonaro.
Tight elections: Despite the divergence in trends indicated by the polls, the results suggest a highly competitive race, with no statistically significant advantage for either candidate.
US: History and expectation for interest rates – updated on September 18, 2026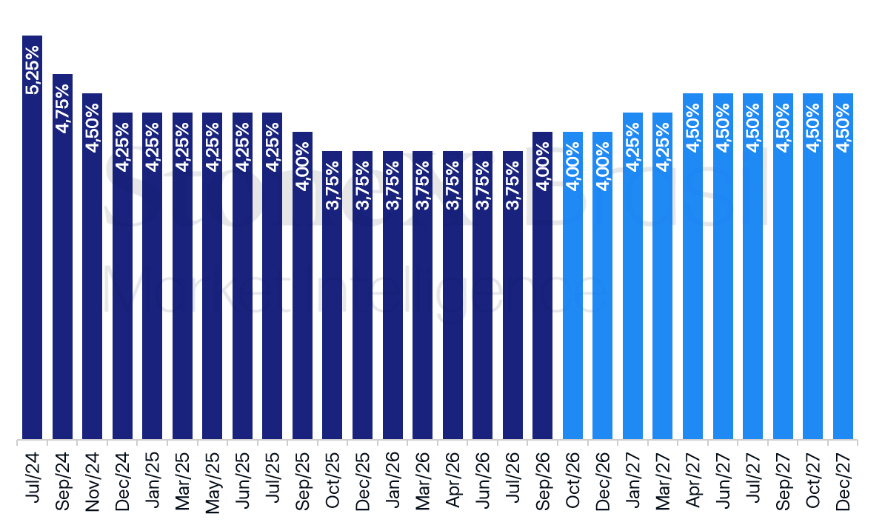
Expectation for the US interest rate at the end of 2026 (% p.a.)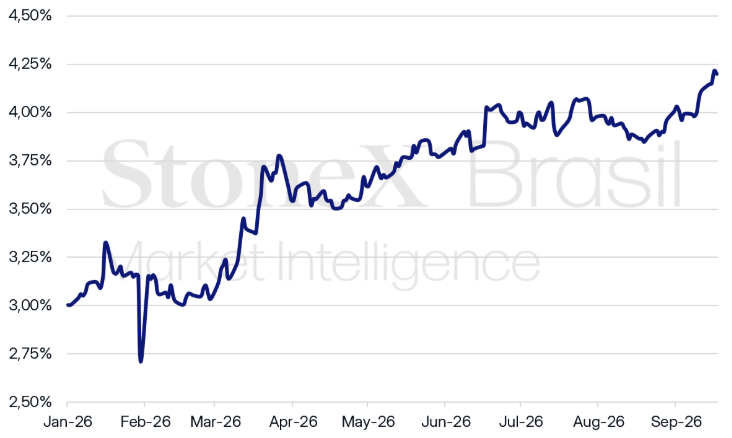
Investors should also react to the expectation of higher interest rates for longer in the United States, after the Federal Reserve (Fed) suggested last week a firmer monetary tightening process.
Why this matters: The expectation of higher interest rates for longer in the US should increase yields on US Treasuries and favor the attraction of foreign capital to the country, strengthening the dollar globally.
FOMC raises rates: Last week, the Federal Reserve's Federal Open Market Committee (FOMC) raised US interest rates to the range between 3.75% and 4.00% p.a. to “support a quicker return [of inflation] to the 2% [annual] target.”
Firm stance against inflation: The following factors contributed to this perception of firmness:
Median of FOMC members' projections for US interest rates at the end of each year (% p.a.)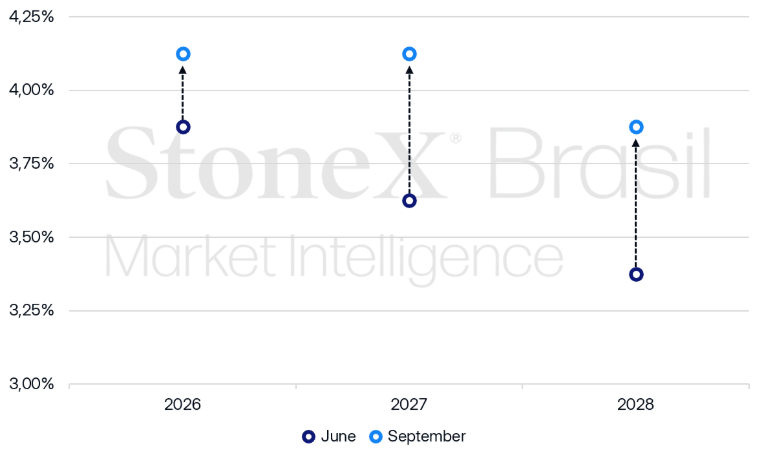
Less transparent Fed: The speeches of other FOMC members gain importance due to Kevin Warsh's cryptic communication style, as they provide analyses and discussions about the economic outlook that the Fed Chairman refuses to address.
Brazil: History and expectation for interest rates – Focus bulletin of September 11, 2026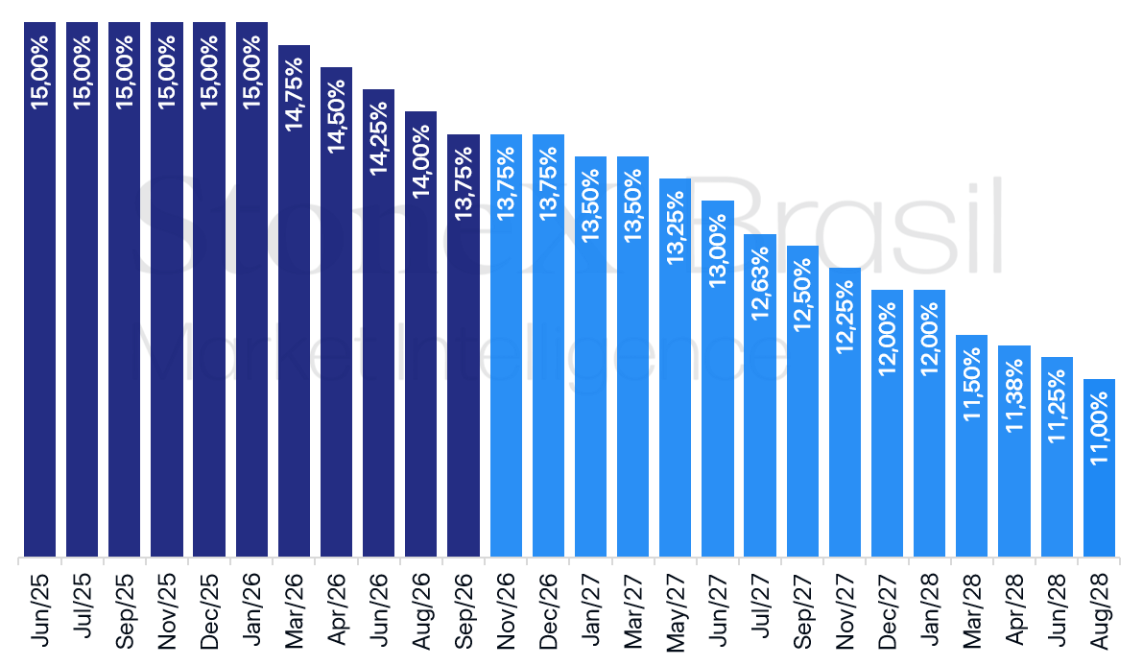
Additionally, investors should react to the release of documents and indicators that could influence expectations for the management of monetary policy in Brazil.
Why this matters: The reports should indicate higher inflationary risks, which may reduce bets on new Selic rate cuts, favor domestic bond yields, and strengthen the BRL.
Neutral tone: Copom maintained its neutral tone in the statement issued after its rate decision, emphasizing serenity and caution in monetary policy management while monitoring the inflationary trajectory in the country.
Risk balance: Copom acknowledged a slowdown in inflation and economic activity, although the latter remains resilient while the labor market remains strong.
IPCA-15: In the economic indicator agenda, investors should monitor the September IPCA-15 reading, which may reflect the reversal of some elements that favored the deflation recorded in the previous month.
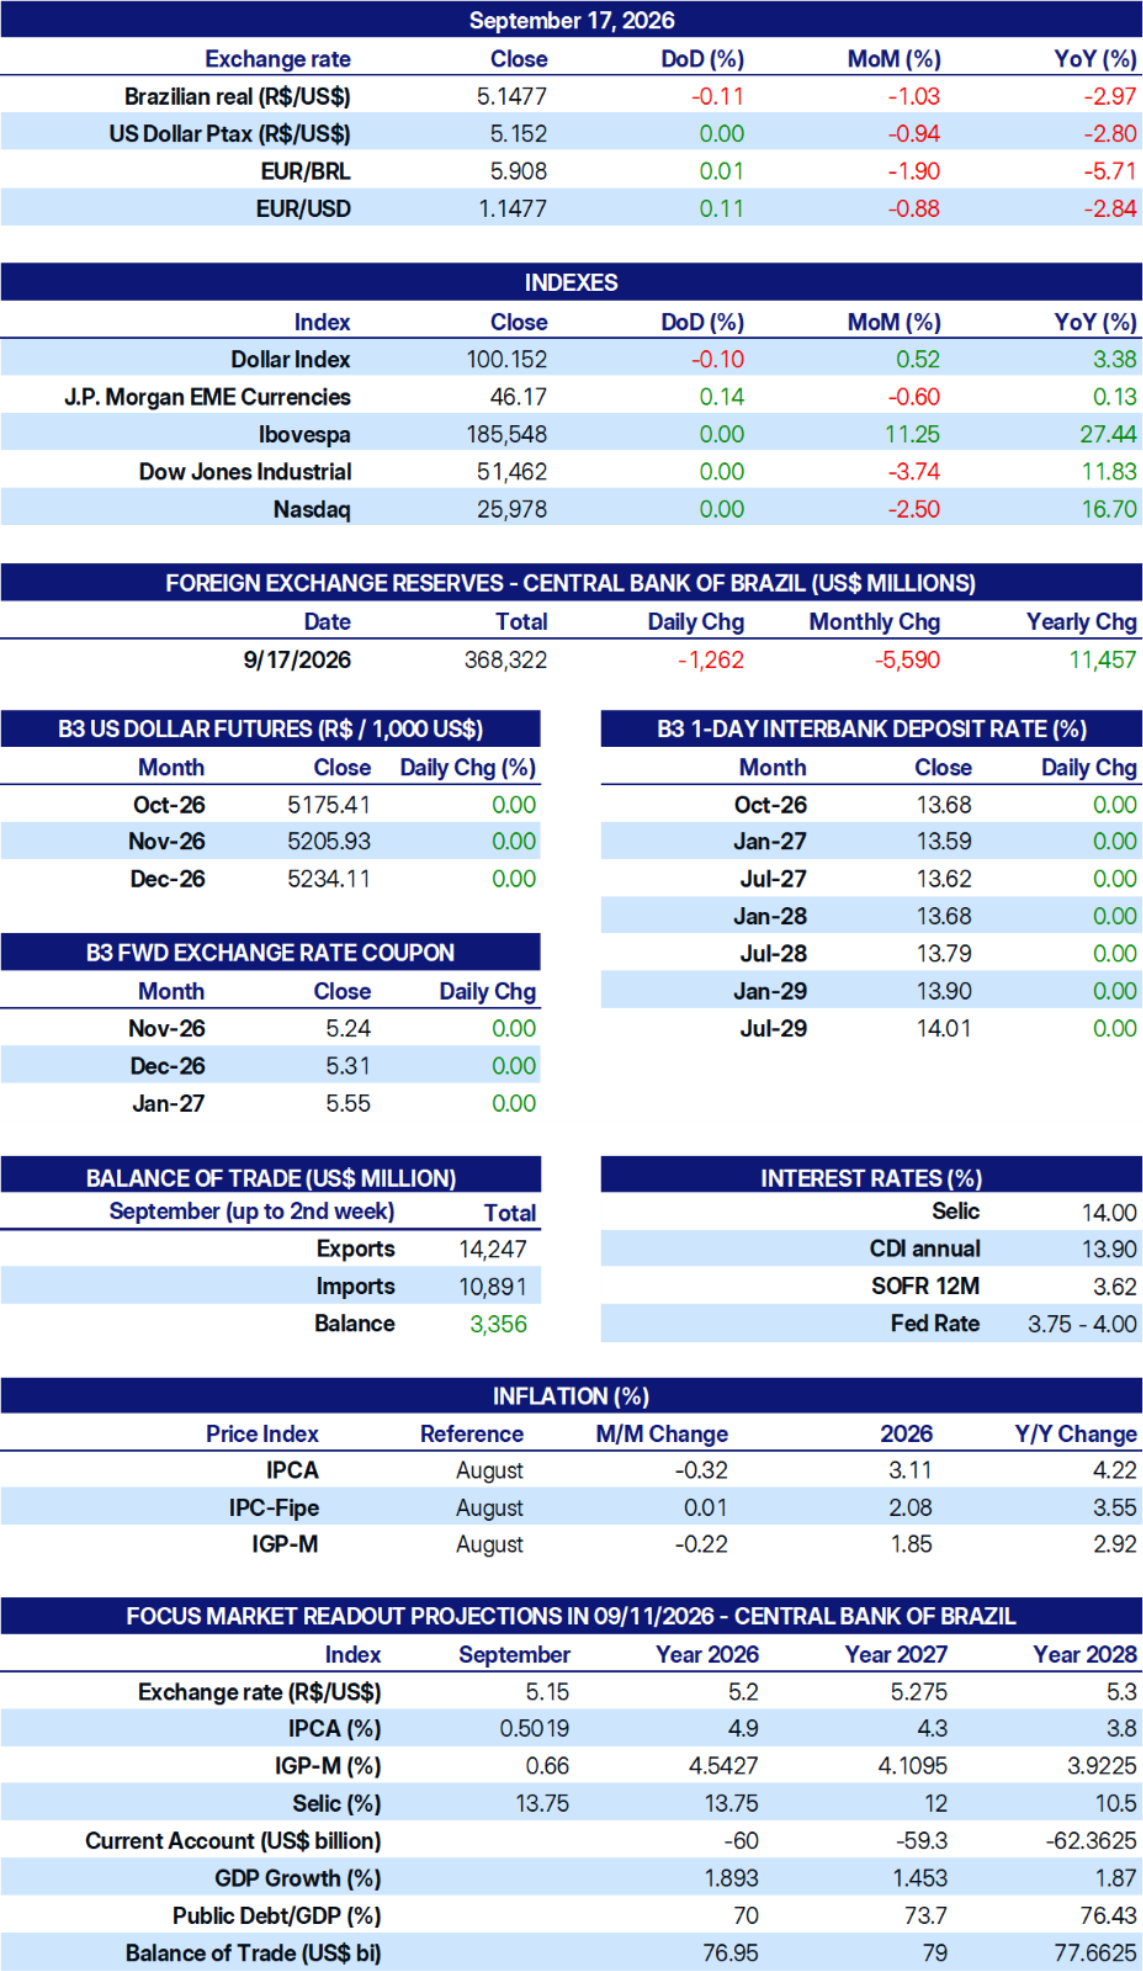
INDICATORS
The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided. References to over-the-counter (“OTC”) products or swaps are made on behalf of StoneX Markets LLC (“SXM”), a member of the National Futures Association (“NFA”) and provisionally registered with the U.S. Commodity Futures Trading Commission (“CFTC”) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ (“ECP”) and who have been accepted as customers of SXM. StoneX Financial Inc. (“SFI”) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (“SEC”) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Adviser. References to securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to exchange-traded futures and options are made on behalf of the FCM Division of SFI . StoneX is a trading name of StoneX Financial Ltd (“SFL”). SFL is registered in England and Wales, Company No. 5616586. SFL is authorized and regulated by the Financial Conduct Authority [FRN 446717] to provide to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorised to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorised & regulated by the Financial Conduct Authority under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorised by the Financial Conduct Authority. StoneX Group Inc. acts as agent for SFL in New York with respect to its payments services business. StoneX APAC Pte. Ltd. acts as agent for SFL in Singapore with respect to its payments services business. ‘StoneX’ is the trade name used by StoneX Group Inc. and all its associated entities and subsidiaries.
Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.
© 2026 StoneX Group Inc. All Rights Reserved.
Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.
Dollar to reflect Brazilian electoral scenario, Copom minutes, RPM, IPCA-15, and expectations of higher interest rates in the US
A currency can clear a major level and still fail, which is why momentum confirmation decides whether an advance holds. Michael Boutros works through what separated the current Dollar Swiss move from two earlier rallies that stalled within days.

Dollar seasonality since the year 2000 gives the U.S. dollar only a narrow September edge before turning sharply against it in December. That seasonal weak spot lands in the same stretch of the calendar as two more Federal Reserve meetings and a fresh set of forecasts.

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.
Reach
With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.
Transparency
As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.
Expertise
From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.