
FX Weekly Overview (Brazil Issue)
Dollar expected to reflect electoral race, bets on US interest rates, IPCA-15, and AI concerns
Leonel Mattos
- Currencies
Quarterly Commodities Outlook is available for free now. Download your report →
Market Intelligence Analyst • BRAZIL PRS
USD/BRL and Dollar Index (points)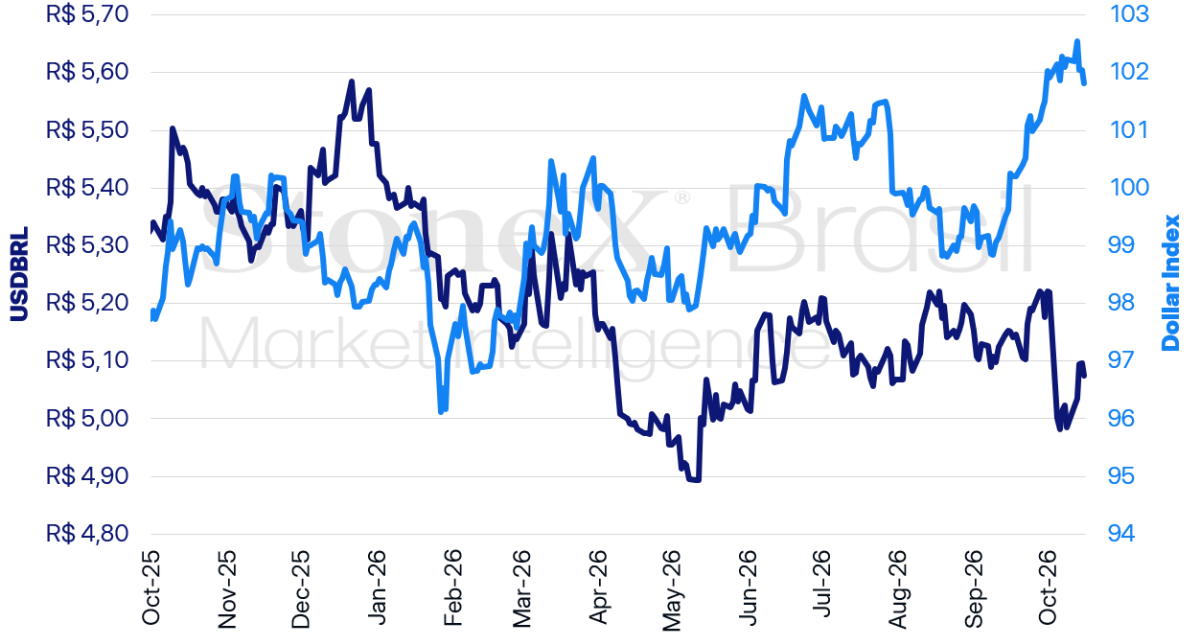
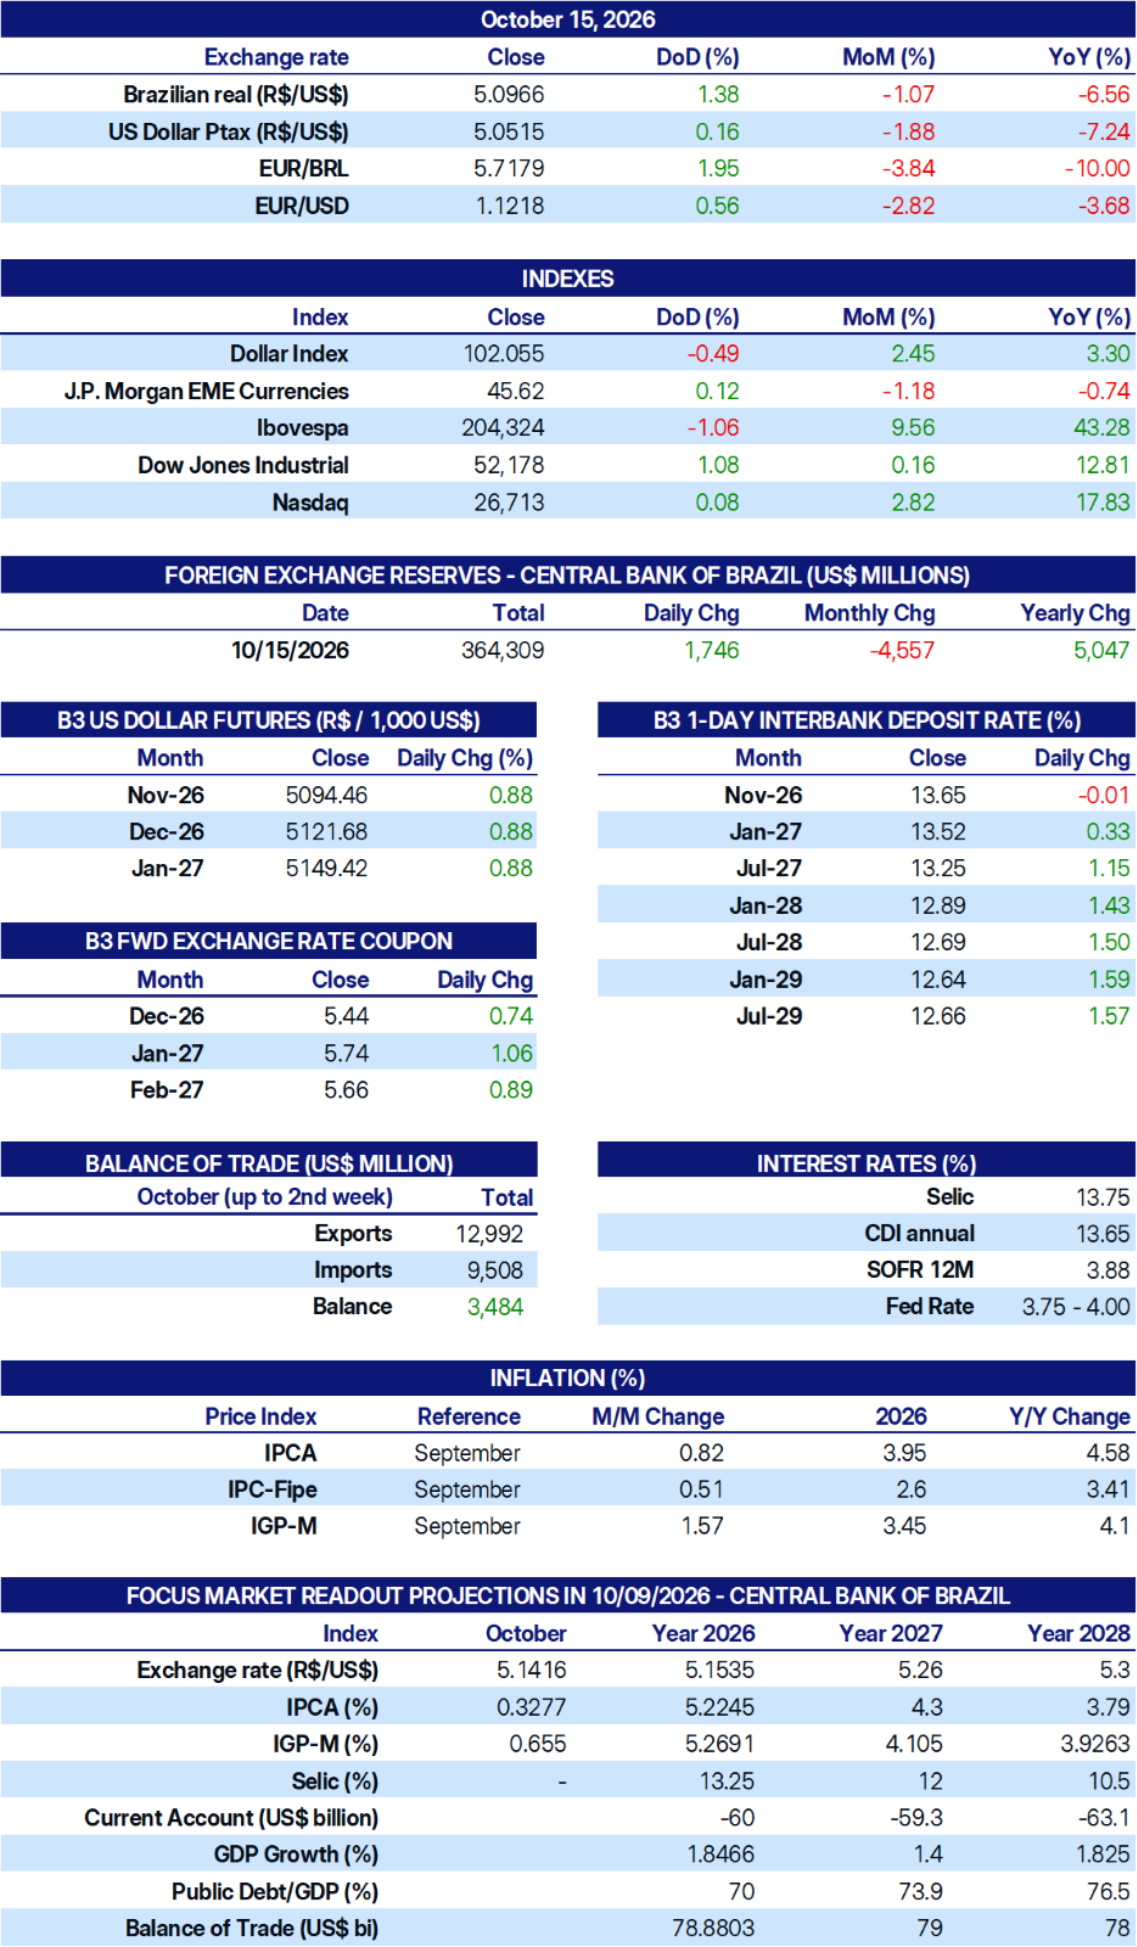
USDBRL Variations | Daily: -0.44% | Weekly: +1.78% | Monthly: -1.96% | Annual: -7.36% | In 12 months: -6.78%
Dollar Index Variations | Daily: -0.24% | Weekly: -0.42% | Monthly: +0.30% | Annual: +3.55% | In 12 months: +3.54%
After the wave of optimism with a possible government change following the first round of elections, the latest voting intention polls indicate a narrowing gap between candidates Flávio Bolsonaro and Lula, reinforcing the perception of a tight second-round race.
Why this mattera: A tight electoral race can reduce predictability about Brazilian economic policies for the next four years, increasing the risk perception of national assets, amplifying volatility, and harming the performance of the Brazilian real.
Latest polls: Despite Flávio maintaining a numerical lead in most polls, recent surveys have indicated a trend of narrowing gap between candidates, reinforcing the perception that the elections are expected to remain tight.
Recent government measures: During the week, the main project approved by the government in the National Congress was the Constitutional Amendment Proposal (PEC) on the end of the 6x1 work shift, which is expected to change working hours in the coming months.
Change in strategy: In recent days, President Lula's campaign changed its communication strategy, focusing on influencers and articulation on social networks and communication apps.
Probability of an interest rate hike at the Federal Reserve's October 28 rate decision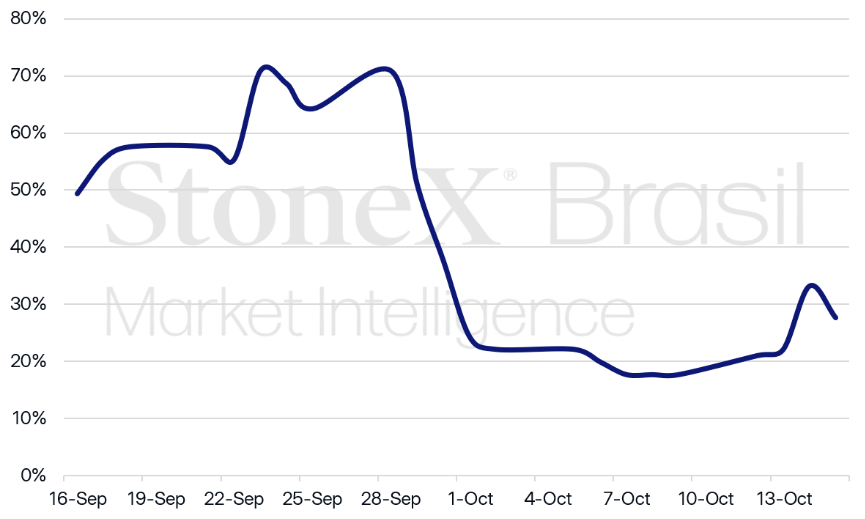
On the external front, the currency market is expected to react to the decrease in investor bets on an interest rate hike by the Federal Reserve in its October decision, even after hotter-than-expected US inflation numbers.
Why this matters: The decrease in bets on new interest rate hikes by the Fed in the short term tends to reduce the yield on US Treasury bonds (Treasuries) and harm the attraction of foreign capital to the country, weakening the USD globally.
Strongwr inflation: Last week, inflation numbers in the United States surprised by showing stronger readings than anticipated, suggesting more persistent and widespread price pressures.
Inflation measures for the United States, accumulated over 12 months (%)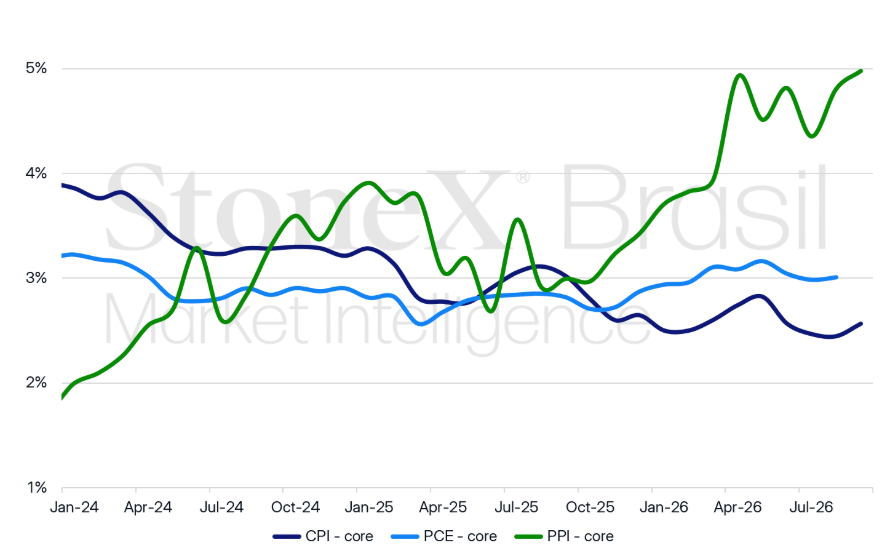
Decomposition of the US Consumer Price Index (CPI), accumulated over 12 months (%)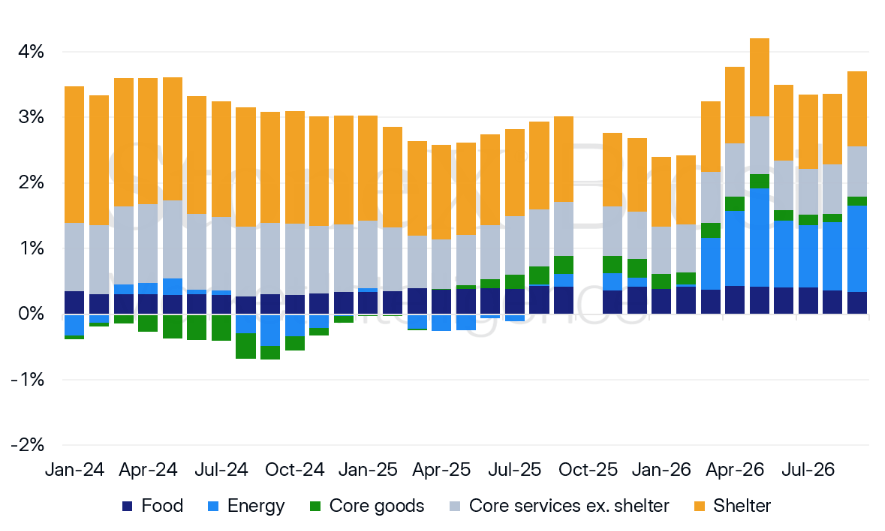
Unchanged bets: However, investors continued to bet on maintaining the interest rate by the Fed in the October decision even after hotter inflation numbers.
Less transparent Warsh communication: It is important to highlight that these apparent contradictions are a reflection of changes implemented by Federal Reserve Chairman Kevin Warsh, which made the central bank's communication more concise, generic, and less informative.
Vocal resistance: Due to this generic and concise communication style and Warsh's refusal to analyze and discuss the American economic outlook, other Federal Reserve members intensified their participation in events, lectures, and interviews.
Domestically, investors are expected to monitor the National Consumer Price Index 15 (IPCA-15), aiming to calibrate their expectations for the inflation trajectory and economic policy in the country.
Why this matters: A stronger inflation reading tends to strengthen investor bets for an interruption in the basic interest rate (Selic) cut cycle, increasing the yields of national public bonds and favoring the attraction of external capital, which would strengthen the Brazilian real.
Latest data: The latest reading of the Broad National Consumer Price Index (IPCA) indicated stronger-than-expected inflation, reinforcing bets on an interruption in the interest rate cut cycle.
Finally, the currency market may reflect heightened investor concerns about the profitability of investments related to artificial intelligence (AI) technologies, which led to sharp losses for the sector's stocks last week.
Why this matters: On one hand, concerns about the profitability of AI companies might generate greater global risk aversion, which tends to favor the performance of assets considered safe havens during stress and uncertainty, such as the dollar.
Fears of an AI "bubble": Last week, investors expressed concerns that the demand for artificial intelligence may not grow as rapidly as necessary to make the intense sector investment expansion profitable, potentially rendering the recent expansion a "bubble."
Portfolio diversification: In theory, these concerns about excessive investment by technology companies should result in a risk-averse scenario and a search for safe assets, which typically strengthens the dollar globally.
INDICATORS
The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided. References to over-the-counter (“OTC”) products or swaps are made on behalf of StoneX Markets LLC (“SXM”), a member of the National Futures Association (“NFA”) and provisionally registered with the U.S. Commodity Futures Trading Commission (“CFTC”) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ (“ECP”) and who have been accepted as customers of SXM. StoneX Financial Inc. (“SFI”) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (“SEC”) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Adviser. References to securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to exchange-traded futures and options are made on behalf of the FCM Division of SFI . StoneX is a trading name of StoneX Financial Ltd (“SFL”). SFL is registered in England and Wales, Company No. 5616586. SFL is authorized and regulated by the Financial Conduct Authority [FRN 446717] to provide to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorised to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorised & regulated by the Financial Conduct Authority under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorised by the Financial Conduct Authority. StoneX Group Inc. acts as agent for SFL in New York with respect to its payments services business. StoneX APAC Pte. Ltd. acts as agent for SFL in Singapore with respect to its payments services business. ‘StoneX’ is the trade name used by StoneX Group Inc. and all its associated entities and subsidiaries.
Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.
© 2026 StoneX Group Inc. All Rights Reserved.
Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.
Dollar expected to reflect electoral race, bets on US interest rates, IPCA-15, and AI concerns
Argentina's borrowing plan has doubled just as bond investors demand higher yields to lend. The financing gap, the World Bank talks and a thin reserve cushion now decide how much room the government has left to support the peso.
Australian business and consumer sentiment surveys are only now capturing the Reserve Bank of Australia's first three rate hikes. With unemployment at a five-year high, firms and households are signaling growing strain from tightening already in the system.

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.
Reach
With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.
Transparency
As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.
Expertise
From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.