Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for November 17

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

November 17 – Wall Street's AI poster child, Nvidia, takes center stage today as their earnings after today’s bell are expected to provide a fresh gauge of hyperscaler AI spending amid escalating scrutiny of the company's global chip sales. To the latter point, investors are increasingly focused on new U.S. efforts to block Chinese access to advanced AI computing power through third-country data centers in Southeast Asia (namely Singapore, Malaysia, Thailand), raising questions about how much of Nvidia's recent demand has ultimately been tied to customers using offshore infrastructure to circumvent existing export controls. The timing of this scandal creates a bit of an uncomfortable backdrop for this week’s gatherings in both Southeast Asia and China, with Trump in the Philippines today meeting with regional leaders before heading to Shenzhen tomorrow with the ultimate feature being his meeting with Chinese President Xi Jinping on the sidelines of APEC summit on Thursday. Obviously, a lot is at stake in the equities space given the outsized role of the tech sector amid the ongoing AI boom, with major implications for commodities as well. Stock futures are pointing to a mixed open after an ugly start to the week, while the VIX remains elevated after yesterday’s spike, currently hovering near the 22.8 mark. The dollar is just on the positive side of unchanged, carving out another fresh nearly 20-month high just above 103.6. Treasuries are off to a quiet start to the day, with 2-year yields just below unchanged to trade at 4.823%, 10-year yields exactly unchanged at 5.121%, and 30-year yields just a tick higher at 5.47%.

Commodities are attempting to stage a turnaround Tuesday this morning, with crude oil prices taking back a portion of yesterday’s losses as nearby WTI trades 1.6% higher to sit near $86.40 and nearby Brent trades 0.7% higher to sit near $93.10. Reports indicated Iran launched another drone attack against a U.S.-linked military installation in Bahrain overnight while additional shipping incidents were reported in the Strait of Hormuz, highlighting the continued disconnect between ongoing mediation efforts and conditions on the ground. Elsewhere in the broader Middle East conflict, Saudi Arabia has replaced the commander overseeing its coalition forces within Yemen following the apparent stalling of their counteroffensive, a major setback to the campaign aimed at recapturing the territory lost around the Bab al-Mandeb Strait in recent months. It appears the Houthis are gearing up for an attack on the Saudi-backed government stronghold of Aden, forcing the coalition to bolster defenses there at the expense of holding areas around the Strait, keeping Red Sea shipping risks present.

Meanwhile, the grains and oilseeds are getting a boost this morning following reports of the Kerch Bridge suffering an arch collapse after consecutive days of Ukrainian strikes, effectively cutting off the Sea of Azov from the Black Sea. Obviously, shipments have already been effectively nonexistent relative to pre-war norms, but this damage could mean a substantial delay to resumed commodity flow even if an agreement was somehow reached. I remain skeptical that such an agreement is near regardless, and today’s news only reinforces that skepticism. Heavy speculative selling pressure has driven the wheat complex down on headlines of optimism regarding the diplomatic push, but on the ground we’ve seen nothing but escalation. Continued Russian strikes on Ukrainian oilseed processing facilities serve as a reminder that this is not just a wheat story either.

U.S. corn harvest advanced another 7% week-on-week to reach 88% complete, 2% below the average analyst estimate and keeping this year’s pace the slowest since the waterlogged 2019 campaign. South Dakota (-14%) is now officially the furthest behind schedule relative to their previous five-year average pace, with Iowa (-11%) not far behind—both similar to but not quite as ugly as 2019. Forecasts shows chances for rains returning to these areas at the tail-end of this week, which may drag things out further, but the Eastern Corn Belt where plenty of corn is still left in the field should stay mostly dry over the next two weeks to wrap up. On the soybean side, harvest advanced another 4% week-on-week to reach 96% complete, as expected.

U.S. winter wheat conditions unexpectedly jumped another 4% week-on-week to now sit at 53% good/excellent, well above the expected 50% and now marking a whopping 9% increase from the initial 44% just two weeks ago. That paints a very different picture of the shape of this fall’s wheat crop, with these ratings now the highest for the comparable week in eight years. With winter wheat crop insurance prices at four-year highs, we expect to see farmers incentivized to increase winter wheat plantings, particularly in those areas of the Plains that are seeing major improvements to soil moisture profiles. Of that group, Oklahoma remains the furthest behind in getting planted, advancing only 7% week-on-week to sit at 84% complete, trailing USDA’s reported five-year average pace by 8% and marking their slowest pace in at least the last 13+ years. At the national level, winter wheat planting only advanced 3% week-on-week, now pegged at 92% complete, below the expected 94%.

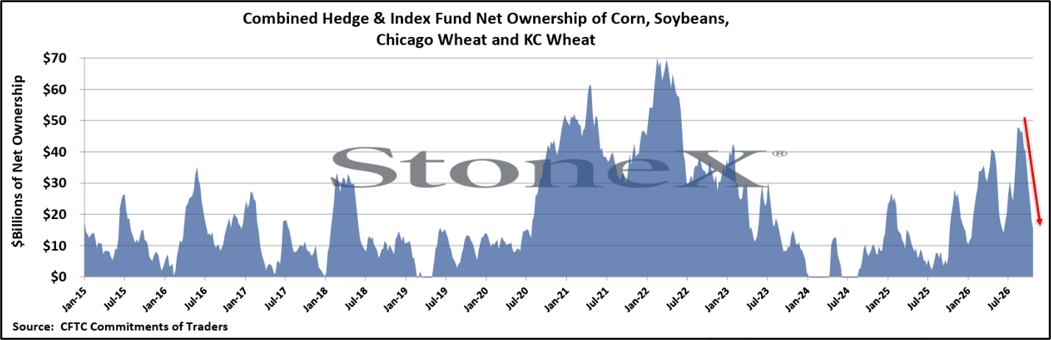
Yesterday’s holiday-delayed CFTC Commitment of Traders report showed managed money continuing their rush for the exit from the broader grain and oilseed space, with heavy selling pressure seen throughout. It’s worth noting that yesterday afternoon’s data is only current through last Tuesday (11/10), but managed money is now estimated net short in corn, Chicago, and KC wheat after seeing a major reverse in course from major net length built earlier this fall. The chart below takes a look at combined hedge and index fund net ownership of corn, soybeans, Chicago, and KC wheat futures which had just recently risen to levels not seen since the period following Russia’s invasion of Ukraine in 2022; that has effectively disappeared. It’s not just grains and oilseeds coming under this selling pressure either, with both live and feeder cattle and lean hogs all seeing net managed money sales on the week as well. This is yet another record net short position held by managed money in lean hogs, with live cattle seeing their biggest net managed money short since February 2024.

image 140654

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for November 17

November 17 – Wall Street's AI poster child, Nvidia, takes center stage today as their earnings after today’s bell are expected to provide a fresh gauge of hyperscaler AI spending amid escalating scrutiny of the company's global chip sales. To the latter point, investors are increasingly focused on new U.S. efforts to block Chinese access to advanced AI computing power through third-country data centers in Southeast Asia (namely Singapore, Malaysia, Thailand), raising questions about how much of Nvidia's recent demand has ultimately been tied to customers using offshore infrastructure to circumvent existing export controls. The timing of this scandal creates a bit of an uncomfortable backdrop for this week’s gatherings in both Southeast Asia and China, with Trump in the Philippines today meeting with regional leaders before heading to Shenzhen tomorrow with the ultimate feature being his meeting with Chinese President Xi Jinping on the sidelines of APEC summit on Thursday. Obviously, a lot is at stake in the equities space given the outsized role of the tech sector amid the ongoing AI boom, with major implications for commodities as well. Stock futures are pointing to a mixed open after an ugly start to the week, while the VIX remains elevated after yesterday’s spike, currently hovering near the 22.8 mark. The dollar is just on the positive side of unchanged, carving out another fresh nearly 20-month high just above 103.6. Treasuries are off to a quiet start to the day, with 2-year yields just below unchanged to trade at 4.823%, 10-year yields exactly unchanged at 5.121%, and 30-year yields just a tick higher at 5.47%.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for November 16

November 16 – Headline whiplash was the feature last week and it’s hard to see that changing this week, with a series of major earnings results and high-level geopolitical events on tap in the days ahead. On the former, AI chip giant Nvidia is set to report after the bell tomorrow, though at this point the market may be less concerned about the health of their Q3 earnings figures and more concerned about what comes next for the company, and the broader sector, amid the ongoing shakeup in leadership in reaction to the developing scandal. This also adds further layers of complexity to negotiations between the U.S. and China this week set to take place in Shenzhen, with the ongoing Nvidia controversy highlighting the challenges of balancing export controls on advanced chips against broader efforts to stabilize bilateral economic relations, with wide-ranging downstream market implications. Amid the ongoing jitters in the tech sector, Anthropic’s highly publicized IPO is currently scheduled to begin trading on the Nasdaq on Thursday—the same day as the planned Trump/Xi summit. Outside of the tech sector, the market also gets a fresh look into the health of consumer spending in the days ahead, with Q3 earnings from Home Depot coming up tomorrow, Target on Wednesday, and Walmart on Thursday. Even without the flurry of geopolitical headlines, this would be a big week—add in these headlines, and expectations are for more volatility ahead.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for November 13

November 13 – Stock futures are pointing to a cautiously higher open as producer level inflation again accelerates to multi-year highs in October, albeit less than feared. The VIX is cooling to start the day, off roughly 3.7% to trade right at 18 at the time of writing. The dollar is quietly higher, touching another fresh 19-month high overnight and hovering near 103.21 at present. Treasury yields are just above unchanged at the front-end of the curve but more elevated at the long-end, with 2-year yields sitting at 4.865% while 10-year and 30-year yields are both up just above 4-basis points each to trade at 5.145% and 5.475%, respectively. Crude oil prices are also quietly higher, with nearby WTI up 0.5% on the day to trade near $89.10 and nearby Brent up 0.9% to trade near $96.70. The ags are mostly higher overnight amid a fresh reality check on the commodity fundamental impact of the Russian/Ukrainian war after headlines of ongoing negotiations dominated earlier in the week.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.