Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for November 5

Mike Castle
Mike Castle

Market Intelligence - Fertilizer Analyst

November 5 – Stock futures are pointing to a mixed open after yesterday’s surge higher, with the Dow Jones looking to add to yesterday’s 3% gain and potentially flirt with pushing to three-month highs, while the tech heavy Nasdaq is looking at a lower open as money rotates out of tech, and the S&P 500 is caught in the middle. The VIX remains notably lower than recent weeks, though up slightly from yesterday’s close, hanging near 16.8 at the time of writing. The dollar is rebounding from yesterday’s losses amid unexpectedly strong U.S. labor market data this morning, reinforcing hawkish Fed bets, as it trades near 101.65. Treasury yields are higher to start the day as well, with 2-year yields trading at 4.618%, 10-year yields at 4.909%, and 30-year yields at 5.288%. Crude oil is bouncing after incredibly sharp losses in recent days, with nearby WTI currently up 2% on the day to trade near $89.80 and nearby Brent up 2.6% to trade near $97.10. Meanwhile, the ags are higher at the break as they look to find a rebound of their own.

Ukraine struck Russia’s Ryazan refinery overnight, one of the country’s largest and most frequently targeted refineries, marking the sixth Russian refinery targeted in the last week as any hope of an energy ceasefire disappears, with Russia also carrying out widespread strikes on Ukrainian power plants and substations over the same span. Russian officials said more than 200 drones had targeted the Ryazan region overnight, acknowledging fires at the facility and temporary power outages, but not confirming the extent of the damage. While crude oil has come under extreme pressure this week as hopes for a quicker end to the conflict in the Middle East rise, the renewed disruptions to Russian refining capacity may continue to provide support to the refined product side. Given both sides’ acceleration of targeting each other’s energy sectors despite this being the primary focus in a potential first step towards peace, the continuation of these attacks could signal any meaningful end to the conflict being pushed back further, keeping disruption to commodity flow from the Black Sea in focus.

U.S. employers announced 43.99k job cuts in October per this morning’s Challenger Report, up slightly from the 43.28k in September but down 71.2% versus the same month last year and marking the lowest October job cuts since 2023. Food companies saw the most cuts at 9.68k, followed by the tech sector (5.58k), and services (5.46k). Cumulative job cuts in 2026 now stand at 617.19k, down a notable 43.9% versus the same span last year and marking the lowest level for January – October since 2022, yet another signal of a largely tighter-than-previously-expected U.S. labor market. The tech sector has seen the most cuts this year at 171.50k, up 21% year-over-year, though it’s worth noting that 22 of the 30 industries that Challenger tracks have seen fewer jobs cuts in 2026 than they did in 2025.  It’s also worth noting that the primary reason for reported job cuts is now shifting from the advancement of technology to actual economic conditions, with market/economic conditions overtaking AI as being the top reported reason for cuts in October for the second consecutive month. The report noted: “AI dominated layoff announcements through the spring and summer, but this fall companies are pointing to demand and economic conditions. That is a more cautious signal, though the overall pace of cutting remains low.”

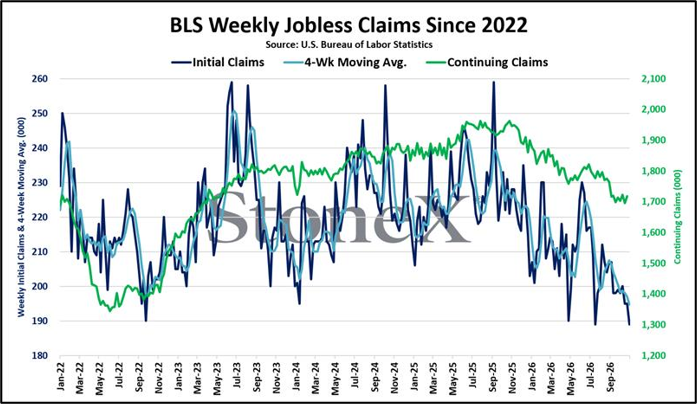
First-time claims for unemployment benefits fell to their lowest in nearly four months at only 189k in the week ending October 31, sharply below the average analyst estimate of a modest rise to 196k. This pushed the four-week moving average for initial jobless claims down to 194.75k, their lowest level since September 1969. Continuing claims ticked up to 1.718M, however, above the average trade estimate of 1.710M. However, it’s worth noting that the week prior was revised down to 1.695M from the 1.701M initially reported, marking the lowest level of continuing claims seen since April 2023. Coupled with this morning’s job cuts data, the U.S. labor market continues to prove unexpectedly resilient, a good sign for the broader economy but another permission signal to the Fed to continue their path of hiking rates moving forward.

Sticking with the theme of more hawkish monetary policy, the Bank of England today raised rates for the first time since 2023 while signaling that more increases were likely moving forward. The 25-basis point hike saw an 8-1 vote, but it’s worth noting the lone dissenter was not arguing for a hold, but rather for a larger 50-basis point hike. Catherine Mann, the lone dissenter, had previously warned that the Bank of England has not done enough to reassure markets that it had a grip on inflation. While the sharp drop in crude oil this week does alleviate some concern moving forward, it’s important to keep in mind the huge build-up in inflationary pressures already in the pipeline, as well as the ongoing tightness in refined products, not crude, which ultimately have the bigger impact on the consumer. The ultimate question is how the U.S. Fed’s path forward will look amid these pressures, with CME’s FedWatch showing the odds of a 25-basis point hike at their December meeting now up to 83%. This conversation, and the broader path into 2027 and the years ahead, will surely remain in focus, with plenty of market-moving macroeconomic data and geopolitical developments currently standing between today and their next meeting.

image 140236

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Brazil's Distillers Grains Market Runs on Logistics, Not Export Totals

Brazil's distillers grains market is shaped by regional logistics around ethanol plants in Mato Grosso, not by national export totals. Rising corn ethanol output has absorbed China's growing demand, and the DG to corn price relationship shows if that balance holds.

Editorial Team
Editorial Team
  • Grains & Oilseeds

Perspective: Morning Commentary for November 5

November 5 – Stock futures are pointing to a mixed open after yesterday’s surge higher, with the Dow Jones looking to add to yesterday’s 3% gain and potentially flirt with pushing to three-month highs, while the tech heavy Nasdaq is looking at a lower open as money rotates out of tech, and the S&P 500 is caught in the middle. The VIX remains notably lower than recent weeks, though up slightly from yesterday’s close, hanging near 16.8 at the time of writing. The dollar is rebounding from yesterday’s losses amid unexpectedly strong U.S. labor market data this morning, reinforcing hawkish Fed bets, as it trades near 101.65. Treasury yields are higher to start the day as well, with 2-year yields trading at 4.618%, 10-year yields at 4.909%, and 30-year yields at 5.288%. Crude oil is bouncing after incredibly sharp losses in recent days, with nearby WTI currently up 2% on the day to trade near $89.80 and nearby Brent up 2.6% to trade near $97.10. Meanwhile, the ags are higher at the break as they look to find a rebound of their own.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Meats & Livestock
  • Forest Products

Brazilian Chicken Exports Are Quietly Draining Demand for Feed Corn

Cheaper Brazilian frozen chicken is replacing local poultry production across the Mediterranean and Middle East, taking feed corn demand with it. Corn looks cheap after its slide, but without feed buyers the market struggles to attract fresh demand.

Editorial Team
Editorial Team
  • Grains & Oilseeds
StoneX: Your access to global markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.