Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for October 13

By: Mike Castle, Market Intelligence - Fertilizer Analyst

October 13 – Stock futures are pointing to a mixed open as the tech sector sells off both in the U.S. and Asian markets amid a fresh round of AI jitters ahead of upcoming third quarter earnings season. The big banks are kicking off that earnings season today, with mixed results thus far as Goldman Sachs showed a huge earnings beat with its second-best quarterly revue on record, though JPMorgan Chase had a headline earnings miss, taking out some momentum. Traders will continue parsing through this morning’s data and reacting in turn, with more big earnings reports on deck in the days ahead. The VIX is off to a relatively muted start, holding near 15.3 at the time of writing. The dollar is giving back yesterday’s gains as it trades 0.35% lower at the time of writing to hang near 102.2 after closing at a fresh 18-month high on Monday. Treasury yields are mixed as trade resumes, with the front-end of the curve higher and long-end lower this morning, as 2-year yields rise back near 4.80% but 10-year yields fall to 5.206%, and 30-year yields fall to 5.559%. Crude oil is quietly lower to start the day, with nearby WTI down 0.3% on the day to trade near $92.90 and nearby Brent down close to 1% to trade near $105.60. The ags are quietly mixed, with selling pressure seen overnight but fresh escalations in the Black Sea that we’ll dive into below providing support.  

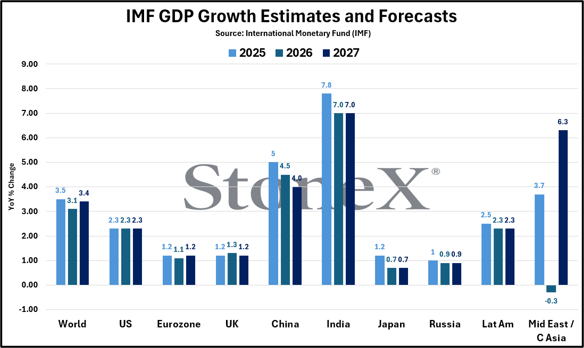
IMF raised their forecast for global economic growth to 3.1% in 2026, up from the 3.0% seen in July, with notable increases in Europe and India more than offsetting declines in Russia and the Middle East. They noted that the large-scale releases of strategic reserves has helped blunt disruptions to the Strait of Hormuz, with said disruption only shaving 0.3% off anticipated growth in 2026, noting that it could have been three times that if not for such measures being taken. With that said, the IMF noted that their growth outlook could erode further if the conflicts in the Middle East or Black Sea continue to escalate. Global growth is still expected to rebound to 3.4% in 2027, holding steady with their previous July estimates. There was some shifting around regarding where that growth will come from, with the U.S., China, and India all revised higher while Russia, Latin America, the Middle East / Central Asia, and the U.K. all saw slight downward revisions.

IMF Chief Economist Silvana Tenreyro did warn that 2027 growth could be “materially lower” and inflation “significantly higher” under a scenario in which sustained higher commodity prices and concerns regarding sovereign debt cause a reassessment of borrowing risks, noting that keeping publicly held debt on a “sustainable path” could prevent this scenario from playing out. The IMF also noted that the global buildout of AI has helped the economy offset geopolitical headwinds, though noting that this buildout is very concentrated in a handful of countries, namely the U.S., China, South Korea, etc. They tied the AI investment boom to near-term inflationary pressures as well, cautioning that any future re-assessment of AI profitability could sharply decrease investment and tighten financial conditions. Hence the jitters in the tech sector both in U.S. and South Korean markets seen overnight.

Russia sank another cargo vessel off the coast of Bulgaria overnight, while another was struck in the vicinity but suffered less serious damage. Reuters is reporting 11 sailors missing at the time of writing, with search and rescue efforts still ongoing. This follows similar attacks last week, with Russia sinking two vessels in the far western Black Sea near Romania and Bulgaria, both NATO members. Russia has been continuously probing the edges of NATO territory for some time now, not just in the Black Sea but also in the Baltics and Arctic, effectively seeing what they can get away with and how NATO forces will respond to such incursions. Bulgaria has reportedly summoned Russia’s ambassador, with Prime Minister Rumen Radev noting the attack was “absolutely unacceptable,” urging both European Commission President Ursula von der Leyen and NATO Secretary General Mark Rutte for support. On the latter, Rutte said this morning that NATO will continue to adjust its military presence on its eastern flank as needed, but the obvious elephant in the room is U.S. support for the bloc. The Trump administration has been very publicly critical of NATO, and the announced diesel diplomacy could potentially embolden Russia further if they view U.S. support as waning, which could drive them to test the edges more aggressively. This keeps Black Sea shipping risks front of mind for the market, with Russia targeting Ukraine’s primary alternative routes with their primary Black Sea ports still effectively cut off.

Mother Nature is impacting the flow of commodities via the Danube River as well, with the Sulina Canal being closed today due to adverse weather, with shippers expecting the closure to last a few days. Coupled with the disruptions from Russian attacks, this adds additional pressure on Ukrainian commodity shipment. Ukrainian farmers union UAC today said they expect the country’s wheat exports to total no more than 11 million metric tons in 2026/27 due to the myriad of disruptions; that is 1.5 million metric tons lower than USDA’s most recent estimate of 12.5 million on Friday’s October WASDE. Cumulative Ukrainian wheat exports since July 1 are currently down 44.2% versus the same period last year.

NFIB’s Small Business Optimism Index fell for the second consecutive month in September, coming in at 97.9 versus the 98.7 seen in August, effectively matching analyst estimates but representing the lowest reading since June. NFIB Chief Economist Bill Dunkelberg noted: “small business owners are proceeding with caution as they interpret how rising costs, interest rates, and the difficulty in finding qualified employees are impacting their business.” Interestingly, the top reported problem was labor quality and availability for the third consecutive month, followed by inflation. Self-evaluations of the health of their own businesses saw a substantial decline from August into September, with the share of “good” falling 9% month-on-month to now sit at 48%. The share of small business owners reporting that it is a good time to expand their business also fell notably to now sit at only 7%, down from the 12% seen in August.

image 138877

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for October 13

October 13 – Stock futures are pointing to a mixed open as the tech sector sells off both in the U.S. and Asian markets amid a fresh round of AI jitters ahead of upcoming third quarter earnings season. The big banks are kicking off that earnings season today, with mixed results thus far as Goldman Sachs showed a huge earnings beat with its second-best quarterly revue on record, though JPMorgan Chase had a headline earnings miss, taking out some momentum. Traders will continue parsing through this morning’s data and reacting in turn, with more big earnings reports on deck in the days ahead. The VIX is off to a relatively muted start, holding near 15.3 at the time of writing. The dollar is giving back yesterday’s gains as it trades 0.35% lower at the time of writing to hang near 102.2 after closing at a fresh 18-month high on Monday. Treasury yields are mixed as trade resumes, with the front-end of the curve higher and long-end lower this morning, as 2-year yields rise back near 4.80% but 10-year yields fall to 5.206%, and 30-year yields fall to 5.559%. Crude oil is quietly lower to start the day, with nearby WTI down 0.3% on the day to trade near $92.90 and nearby Brent down close to 1% to trade near $105.60. The ags are quietly mixed, with selling pressure seen overnight but fresh escalations in the Black Sea that we’ll dive into below providing support.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for October 12

October 12 – Geopolitics are the feature to start the week, with major weekend escalations in the Middle East and a surprising U.S. / Russian agreement throwing a wrench into Black Sea diplomacy. Stock futures are pointing to a quietly mixed open as traders attempt to digest the weekend developments, as well as prepare for this week’s September inflation data, and look ahead to the upcoming third quarter earnings season. The VIX is elevated to start the week but remains near the low-end of 2026’s range, hovering near 15.5 at the time of writing. The dollar continues to march higher, though it does appear to be running into resistance every time it approaches the 102.5 level, currently trading near 102.42 this morning. U.S. bond markets are closed today in observance of Columbus Day, though Treasury futures will be trading normally. Crude oil is rising following the weekend escalations, with nearby WTI up 2.15% at the time of writing to trade near $93.65, while nearby Brent is up 1.9% to trade near $106.70, a nearly four-week high. The ags are largely mixed to start the week, with the market finding its footing following Friday’s surprises in USDA’s October WASDE report.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

U.S. Corn Acres Shrink as Fertilizer Costs Push Growers to Soybeans

Low corn prices and rising fertilizer costs pushed U.S. growers toward soybeans, shrinking the U.S. corn crop after a record season. The smaller crop arrives as other exporters face constraints, leaving global buyers more dependent on U.S. corn.

Editorial Team
Editorial Team
  • Grains & Oilseeds
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.