Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for October 16

By: Mike Castle, Market Intelligence - Fertilizer Analyst

October 16 – Stock futures are pointing to a mixed open, keeping theme with the choppy week of trade seen thus far as the broader equity sector pushes mostly higher but with a notable shuffling of money flow out of tech and into other areas. The VIX is off notably to start the day, hovering back around 16 after pushing to a fresh one-month high above 18 yesterday. The dollar is adding to yesterday’s losses, down 0.2% at the time of writing to trade near 101.8 after touching a two-week low overnight. Treasury yields are modestly higher this morning, with 2-year yields near 4.76%, 10-year yields at 5.11%, and 30-year yields just above 5.44%. Crude oil is looking to end a strong week on a weak note, with nearby WTI off 1.6% to hang near $96 after posting a fresh four-week high yesterday, while nearby Brent is near unchanged around $105.9 at the time of writing. The ags are off to a mostly lower start, though it will be interesting to see if this morning’s export data that we’ll touch on below brings any strength on the open.

This morning’s holiday-delayed USDA export sales report showed a rebound in corn sales to 44.2 million bushels in the week ended October 8, a five-week high, with Mexico the featured destination. That was effectively right in line with the previous five-year average for weekly corn sales, but again weaker than last year, with cumulative 2026/27 corn sales of 814 million bushels now 32.7% behind last year’s pace. After USDA added another 25 million bushels to their expected 2026/27 corn export demand on last week’s October WASDE, the market needs to see a meaningful uptick in realized sales to play catch-up with the pace needed or risk seeing that figure walked back downward. It’s worth noting that today’s report is the first full week of U.S. export sales data following the September 30 quarterly stocks surprise that drove corn prices notably lower. There’s plenty of intrigue on next week’s report as well, as that will give us the first look at U.S. corn sales following USDA’s second bearish surprise on the October WASDE. My own expectation is to see a notable rebound as buyers that had previously been sitting on the sidelines watching prices move higher start to step forward to take advantage of the break in prices. This morning’s daily flash sale announcement of 127k metric tons (5.0 million bushels) of corn to Japan may be evidence of this.

Elsewhere, weekly soybean and wheat sales both came in near the low-end of expectations at 21.1 million bushels and 11.8 million bushels, respectively. On the soybean side, China was yet again the featured buyer, as they have been all year, with a surge of flash sales announced this week, including today. USDA this morning reported total daily flash soybean sales of 794k metric tons (29.2 million bushels), with 558k metric tons (20.5 million bushels) to China and the remaining 236k metric tons (8.7 million bushels) to unknown destinations, potentially also China. This brings the total over the last three days to an impressive 1.877 million metric tons (69.0 million bushels), helping offset some of the disappointment following yesterday’s unexpectedly weak September NOPA soy crush. On the wheat side, U.S. exports remain off to a slow start in the 2026/27 marketing year, with the cumulative total now sitting at 383 million bushels, down 32.6% from last year’s strong pace and maintaining the weakest pace in three years. Disruptions to Black Sea shipping and potential quality problems in both Canada and Argentina do keep the door open for additional U.S. export demand in the months ahead, but USDA’s 25 million bushel cut in their export target on last week’s WASDE reflects the market’s growing impatience over seeing more of this demand come to fruition.

Fed Chair Kevin Warsh’s address from the IMF meeting in Bangkok helped calm markets overnight as he expressed optimism regarding the resilience of not just the U.S. but global economy in the wake of ongoing shocks in the energy sector and beyond, while also referring to inflation as a “common challenge,” pointing to the synchronous tightening in monetary policy around the world to address such pressures. Given this week’s hot inflation data at both the producer and consumer level, market expectations had shifted notably hawkish, but have cooled notably to end the week, with Warsh’s comments and those from other FOMC members easing fears of an October hike, with CME’s FedWatch showing the odds of such a hike back down to ~15%, maintaining a base case of one more 25-basis point hike by year’s end, coming at the December meeting. We’ve also seen tech stocks shaken this week by renewed jitters regarding the sector’s massive debt load, but Warsh’s confirmation of the Fed’s new task force on the impact of AI on productivity and jobs set to hold a “field hearing” in the Bay area one month from today helped bring some sense of calm as well. While he covered the topic of AI extensively, he also pointed to strength in U.S. investment beyond AI providing further resilience to U.S. economic growth, noting: “it means we’ve got plenty of tailwinds that are giving some strength and durability to this economy,” highlighting that such tailwinds are not present everywhere globally.

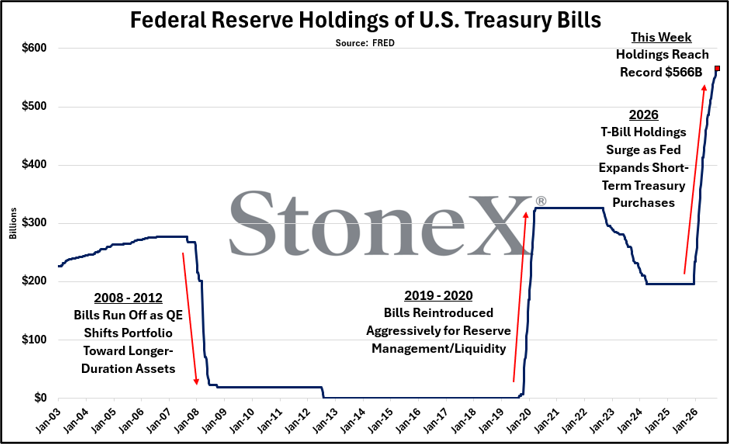
Total assets in the Fed's balance sheet (less eliminations from consolidation) rose 0.12% week-on-week to $6.756T, their largest weekly increase in nine weeks and the highest level over that span. For a period still characterized as quantitative tightening, it is notable that the Fed’s balance sheet has not been shrinking meaningfully in recent months and is now up 3.36% from the recent low of $6.536T posted in December 2025, though still 24.7% below the pandemic-era peak of $8.965T reached in April 2022. The most notable development continues to be the growing concentration in Treasury bills, which increased another $3.9B on the week to a fresh all-time high of $566.0B. Treasury bill holdings are now up $370.6B from a year ago, accounting for nearly all of the $374.3B annual increase in the Fed's Treasury portfolio. Meanwhile, mortgage-backed securities (MBS) holdings have declined $187.8B over the same period, reinforcing the view that the Fed is steadily reshaping the composition of its portfolio away from MBS and toward Treasuries. While hardly indicative of renewed balance-sheet expansion, the trend does suggest that quantitative tightening in 2026 looks considerably different than it did two years ago. The Fed's portfolio continues to migrate toward shorter-duration Treasury holdings even as overall asset levels have largely stabilized, a backdrop that points to abundant system liquidity and a balance sheet much closer to its eventual steady-state composition than many may appreciate.

image 139102

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for October 16

October 16 – Stock futures are pointing to a mixed open, keeping theme with the choppy week of trade seen thus far as the broader equity sector pushes mostly higher but with a notable shuffling of money flow out of tech and into other areas. The VIX is off notably to start the day, hovering back around 16 after pushing to a fresh one-month high above 18 yesterday. The dollar is adding to yesterday’s losses, down 0.2% at the time of writing to trade near 101.8 after touching a two-week low overnight. Treasury yields are modestly higher this morning, with 2-year yields near 4.76%, 10-year yields at 5.11%, and 30-year yields just above 5.44%. Crude oil is looking to end a strong week on a weak note, with nearby WTI off 1.6% to hang near $96 after posting a fresh four-week high yesterday, while nearby Brent is near unchanged around $105.9 at the time of writing. The ags are off to a mostly lower start, though it will be interesting to see if this morning’s export data that we’ll touch on below brings any strength on the open.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Behind China's Two-Speed Economy, a Ceiling on Agricultural Demand

China's growing exports and advanced manufacturing sit alongside weak property, investment and consumer spending, and the split is reshaping commodity demand. Industrial metals draw support from the stronger side, while cautious consumers limit growth in restaurant spending and premium meat.

Editorial Team
Editorial Team
  • Grains & Oilseeds

Perspective: Morning Commentary for October 15

October 15 – Inflation is the feature again today, with this morning’s headline September PPI surging to 6.3% year-on-year, sharply above the average analyst estimate of 5.3% and representing the hottest reading since December 2022. Furthermore, August was revised 0.2% higher to now show a 5.6% rise. In month-on-month terms, this was a 1.3% uptick, sharply above the expected 0.5% and marking the highest monthly increase since March 2022. Stripping back the more volatile food and energy sectors, the inflationary pressures were still significant. Core PPI surged 0.7% month-on-month, sharply above August’s 0.2% and the average analyst estimate of 0.3%. In year-on-year terms, core PPI was up 5.0%, well above the expected 4.4% gain and marking the highest level seen since 2023. As with the headline print, August core PPI was revised higher by 0.2% as well, now showing a 4.8% gain.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.