StoneX logo

Perspective: Morning Commentary for October 6

By: Mike Castle, Market Intelligence - Fertilizer Analyst

October 6 – Stocks are looking to add to yesterday's gains, with futures pointing to a notably stronger open across the major indexes, with the Nasdaq looking to extend further into all-time high territory and the S&P 500 not far from doing the same. The VIX is lower to start the day, hovering near the 15.3 level at the time of writing. The dollar is giving back some of its recent sharp gains after pushing to a fresh 18-month high yesterday, currently hanging 0.25% lower on the day to trade near 101.85. Treasury yields are easing this morning, with 2-year yields trading at 4.785%, 10-year yields trading at 5.275%, and 30-year yields at 5.646%. Crude oil prices are extending their decline, with nearby WTI down 2.3% at the time of writing to trade at a month-plus low near $87.20, while nearby Brent is off 2.5% to trade near $97.80. The grains and oilseeds are mostly higher at the break following some surprises on yesterday’s USDA Crop Progress report as well as fresh escalation in the Black Sea.

Russia sank another vessel in the Black Sea today after already doing so on Monday, this time the Togo-flagged ALFA WATAN while another ship, the Palau-flagged ABLE, was also hit in the same vicinity, catching fire but not sinking. While we’ve seen a massive number of ships targeted in the Black Sea in recent months, the most notable part of today’s development comes down to geography. These strikes both took place in Bulgaria’s exclusive economic zone (EEZ) in the Black Sea, the first such instance of this happening. As a reminder, Bulgaria is a NATO member, bringing the potential for additional escalation into focus. Russia has been increasingly testing the boundaries of the NATO alliance, most notably in the Black Sea region, but also in the Baltics and Arctic—something worth keeping an eye on moving forward.

Yemen remains the primary flashpoint of the ongoing Middle East conflict this week, with intense fighting taking place on the ground and from the air amid the now ongoing Saudi-backed Yemeni government offensive. Yemen’s government forces have claimed notable battlefield gains, with heavy Saudi airstrikes providing support, but it remains too early to make any real conclusions about how much territory has been recaptured, with the most strategic importance on the land surrounding the Bab al-Mandeb Strait that was recently seized by the Houthis. Officials from Pakistan and Turkey traveled to Riyadh yesterday to meet with Saudi leadership amid the escalating conflict, bringing their new Mecca Joint Defense Agreement into focus. Following the meeting, the three nations released a joint statement “to move immediately to the practical implementation of the collective defense commitments and to take the necessary measures to provide the agreed military forces and capabilities and ensure their rapid deployment in the Kingdom.” Put simply, Pakistan and Turkey appear to be honoring the commitment to the new Mecca Pact by sending troops of their own to defend Saudi Arabia, but it’s unclear at this point what sort of role those troops will fill. The bombardment is not just happening in Yemen either, with the Houthis continuing to send drones and ballistic missiles into Saudi territory, including strikes on multiple civilian airports in southwestern Saudi Arabia, with multiple injuries reported. Other neighboring Gulf countries have expressed solidarity with the Saudis, and their Mecca Pact allies, following the attacks, piling on additional pressure to the Iranian axis.

Wet weather delayed U.S. corn and soybean harvest notably last week, with yesterday afternoon’s USDA Crop Progress report showing corn harvest advance only 5% week-on-week versus the expected 8% to now sit at 23% complete, while soybean harvest advanced only 8% week-on-week versus the expected 12% to now sit at 25% complete. Both have slipped further behind their respective average paces, and both represent their slowest start since the waterlogged 2019 campaign. Combines should’ve started rolling again heavily over the weekend once the soil dried out, however, with this week’s warm, dry forecast is likely to produce a big week of progress to play catch up for next Monday’s report.

U.S. corn and soybean ratings fell 3% and 1% week-on-week to sit at 54% and 57% good/excellent, respectively. That matched analyst expectations on the soybean side but represented a 2% miss to the downside on corn, remaining at the lowest level in three years. The sharpest decline in corn ratings this week was in Nebraska (-8%), followed by Iowa (-3%). The intuitive takeaway here would be disappointing harvest results, but these two states made very little progress, with Nebraska advancing only 4% and Iowa 2% week-on-week. Could this just be a function of the crops taking a dive in the beauty contest due to the excessive rainfall on the mature crop, or is this a function of what has been able to be harvested showing poor results versus expectations? That’s the ultimate question the market will be asking, but unfortunately, we don’t know enough today to answer it. If the current forecasts verify and we do see the expected uptick in harvest progress in the heart of the Corn Belt, a clearer picture should begin taking shape.

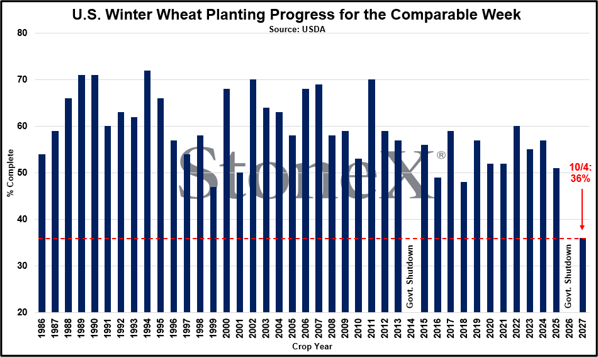
U.S. winter wheat planting remains off to its slowest start for the comparable week on record, advancing only 9% week-on-week to reach 36% complete on yesterday afternoon’s Crop Progress report. This was sharply behind the average analyst estimate of a 16% advancement to reach 43% complete and lags the previous five-year average (note: last year is not included because of the government shutdown) by 19%. You may find yourself asking: “if the U.S. is off to such a slow start, why is the market not reacting more?” The answer to that question lies with the forecasts for what lies ahead, as alluded to above. Yesterday’s figures likely did not capture the catch-up being played over the weekend across the Plains, as the recent boost to soil moisture profiles finally gives farmers the green light to put the hammer down. Coupled with expectations for a largely dry week this week, we should see considerable progress made by next Monday’s USDA report. Add in the fact that July 2027 KC wheat futures averaged $8.11/bushel for the fall crop insurance price discovery period (8/15 – 9/14), and the incentive for a notable uptick in winter wheat plantings is clearly present. The question now is how these forecasts verify and how much progress is made in the weeks ahead.

image 138550

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for October 6

October 6 – Stocks are looking to add to yesterday's gains, with futures pointing to a notably stronger open across the major indexes, with the Nasdaq looking to extend further into all-time high territory and the S&P 500 not far from doing the same. The VIX is lower to start the day, hovering near the 15.3 level at the time of writing. The dollar is giving back some of its recent sharp gains after pushing to a fresh 18-month high yesterday, currently hanging 0.25% lower on the day to trade near 101.85. Treasury yields are easing this morning, with 2-year yields trading at 4.785%, 10-year yields trading at 5.275%, and 30-year yields at 5.646%. Crude oil prices are extending their decline, with nearby WTI down 2.3% at the time of writing to trade at a month-plus low near $87.20, while nearby Brent is off 2.5% to trade near $97.80. The grains and oilseeds are mostly higher at the break following some surprises on yesterday’s USDA Crop Progress report as well as fresh escalation in the Black Sea.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for October 5

October 5 – It’s a relatively light week of economic data, so geopolitics will likely remain in focus. Stock futures are pointing to a quietly mixed open to kick off the week as they await the next headline, with the VIX rebounding from Friday’s drop to hang in the middle of last week’s range, sitting just above 16.1 at the time of writing. The dollar has carved out another 18-month high, pushing above 102.5 overnight and remaining up ~0.3% on the day to trade near 102.25 at present. Treasury yields are modestly higher to start the day, with 2-year yields trading at 4.835%, 10-year yields at 5.305%, and 30-year yields at 5.66%. Crude oil prices are modestly lower this morning, with nearby WTI down roughly 2% to trade near $89.40 but Brent down a much more modest 0.1% to trade near $102.10. The ags are mostly higher to start the day, looking to claw back some of last week’s sharp losses.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Mid-Day Commentary for October 2

October 2 – The Nasdaq surged to another fresh all-time high this morning and remains up roughly 1% on the day at the time of writing, while the S&P 500 is up 0.65%, and the Dow Jones is up 0.3% as equities breathe a sigh of relief on falling rate expectations. The VIX has bounced from its morning lows but remains notably lower, hovering near 15.8 at midday. The dollar remains in the red as well, albeit still notably elevated after breaking above 102 for the first time since April 2025 yesterday, trading near 101.88 at present. Interestingly, Treasury yields have risen through the session to now sit higher on the day, with 2-year yields at 4.806%, 10-year yields at 5.252%, and 30-year yields at 5.613%. Crude oil prices remain notably lower but also off the morning lows, with nearby WTI down 3.1% to trade near $90 and nearby Brent down 1.6% to trade just below $100.70. The ags remain quietly mixed, mostly in the red at the time of writing.

Mike Castle
Mike Castle
  • Grains & Oilseeds
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.