Quarterly Commodities Outlook is available for free now.  Download your report  →

StoneX logo

Perspective: Morning Commentary for October 8

By: Mike Castle, Market Intelligence - Fertilizer Analyst

October 8 – Crude oil is higher and stock futures are pointing lower to start the day while the VIX rises back above the 15.7 level. The combination of escalatory rhetoric and continued Iranian strikes on vessels in the region coupled with hurricane related U.S. Gulf production impacts has nearby WTI up close to 4% on the day as it trades at its highest level of the week near $92.40, while nearby Brent is up a stronger 4.6% to trade at a three-week high near $104.80. The rise in crude prices and another week of strong U.S. labor data drives rate expectations higher, reflected in the rise in the dollar as it pushes another 0.1% higher to trade near 102.35, while Treasury yields push higher as well, with the strength at the front-end of the curve. 2-year Treasury yields are up 5 basis points to trade at 4.814%, 10-year yields are up 3 basis points to trade at 5.307%, and 30-year yields are up just over 1 basis point to trade at 5.674%. Meanwhile, the ags are quietly mixed at the break, with the biggest weakness on the soy side while the wheat complex hovers just above unchanged.

U.S. Gulf producers have shuttered roughly 25% of oil and 16.4% of natural gas production due to the arrival of Hurricane Isaias, according to the Marine Minerals Administration, with personnel being evacuated from offshore rigs near the expected path as a precautionary measure. Hurricane Isaias is officially the first of the 2026 Atlantic season, with models pointing to an intensification through today and early tomorrow, then weakening before making landfall overnight Friday and into Saturday morning. The current expected path is centered on the Mobile Bay area, on the far eastern edge of the offshore production belt. Markets will be keeping a close eye on that path through today and tomorrow to see if the path or intensity changes, with increasing importance on U.S. energy exports to the global market amid the ongoing supply disruptions elsewhere. From an ag market perspective, the focus will be on not just export logistics disruptions, but also how the expected heavy rains impact cotton harvest and quality in the Southeast, as well as how far north the system brings moisture that could slow corn and soybean harvest progress in the Ohio River Valley and broader Eastern Corn Belt.

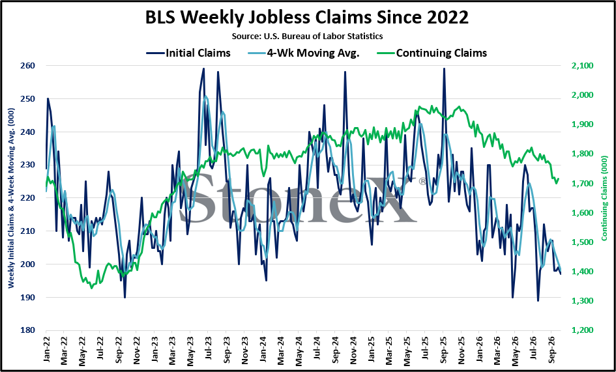
First time claims for unemployment benefits came in below expectations yet again at 197k in the week ending October 3, down slightly from an upwardly revised 199k (originally reported at 197k) in the week prior and 3k below the average analyst estimate. This brought the four-week moving average for initial jobless claims to only 198k, now officially the lowest level in exactly four years. Continuing claims did tick higher to 1.716M, up from a downwardly revised 1.699M in the week prior, that represented a three-and-a-half year low, and above the average analyst estimate of a more moderate rise to 1.708M. Overall, the U.S. labor market continues to prove much more resilient than expected, a welcome sign for economic health but increasingly viewed as a permission signal to the Fed to continue moving rates higher.

The September Fed meeting minutes released yesterday afternoon reinforced a higher-for-longer policy outlook, showing a Fed increasingly concerned about persistent inflation tied to energy markets and AI-driven investment demand, while viewing economic growth and labor-market conditions as strong enough to justify at least one additional rate hike before year-end. Despite the unanimous 12-0 vote to hike, one notable caveat under the surface was the divide within the Fed over the source of inflation. Policymakers appeared split between those viewing recent inflation pressures as largely the result of energy and other supply shocks and those increasingly concerned that strong demand, resilient spending, and AI-driven investment are creating a more persistent inflation problem that may require additional policy restraint. That will likely drive debate at the upcoming October meeting taking place on 10/27 – 10/28. Generally speaking, the FOMC clearly assesses the broader U.S. economy as persistently strong and labor market concerns as diminishing relative to their earlier stances, with this morning’s data only reinforcing that position. Again, this is one of those things that sounds like a positive on the surface, but the equities market can take as a negative as it reinforces the justification for moving rates higher for longer. In my read, perhaps the most hawkish quote from the September minutes was: “several participants stated that they viewed the current policy rate as not restrictive or only mildly restrictive.” That implies that these members either view current conditions as too loose, or that the neutral rate is higher than previously believed.

At the end of the day, the Fed’s path forward will likely be data dependent, with plenty to take in between now and their October meeting, including our first look at September inflation data next week, with CPI out on Wednesday (10/14) and PPI on Thursday (10/15). The market is pricing in strong expectations of the FOMC holding steady at the October meeting, with odds at roughly 79% this morning, per CME’s FedWatch. With that said, the bigger interest will likely be on the following meeting in December where the next 25-basis point hike is being priced in, with those odds sitting around 69%. It is worth noting that the odds of two hikes by the end of 2026 are currently being priced in slightly higher than the odds of no hikes by then, hinting at the hawkish tilt in market expectations. We’ll also get an updated Q3 print from the Atlanta Fed’s GDPNow later this morning, with traders watching for developments in broader U.S. economic growth expectations that act as another permission signal for moving rates higher.

image 138733

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for October 8

October 8 – Crude oil is higher and stock futures are pointing lower to start the day while the VIX rises back above the 15.7 level. The combination of escalatory rhetoric and continued Iranian strikes on vessels in the region coupled with hurricane related U.S. Gulf production impacts has nearby WTI up close to 4% on the day as it trades at its highest level of the week near $92.40, while nearby Brent is up a stronger 4.6% to trade at a three-week high near $104.80. The rise in crude prices and another week of strong U.S. labor data drives rate expectations higher, reflected in the rise in the dollar as it pushes another 0.1% higher to trade near 102.35, while Treasury yields push higher as well, with the strength at the front-end of the curve. 2-year Treasury yields are up 5 basis points to trade at 4.814%, 10-year yields are up 3 basis points to trade at 5.307%, and 30-year yields are up just over 1 basis point to trade at 5.674%. Meanwhile, the ags are quietly mixed at the break, with the biggest weakness on the soy side while the wheat complex hovers just above unchanged.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Quarterly Commodities Outlook - Q4 2026

Diesel squeeze, rising global rates and a very strong El Niño: what is driving commodity markets in Q4 2026.

StoneX Intelligence Brazil
  • Grains & Oilseeds
  • Energy
  • Renewable Fuels
  • Coffee
  • Cotton
  • Sugar
  • Fertilizers
  • Meats & Livestock
  • Currencies

Euro Weakness Hands Paris Wheat an Export Advantage as Tenders Swell

A weaker euro is making European wheat potentially cheaper for overseas buyers just as international tenders grow larger. Black Sea attacks and a slower Ukrainian export pace add to the supply picture European wheat competes against.

Editorial Team
Editorial Team
  • Grains & Oilseeds
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.