StoneX logo

Perspective: Morning Commentary for September 28

By: Mike Castle, Market Intelligence - Fertilizer Analyst

September 28 – Stock futures are pointing to a lower open to start the week, with the Nasdaq and S&P 500 both remaining within shouting distance of their respective all-time highs, while the Dow Jones continues to be the laggard of the major indexes, holding in a clear downtrend after touching a three-plus month low last week. The VIX is elevated to start the week but remains on the low-end of 2026 trade, hovering just above 16 at the time of writing. The dollar is in the green again after big weekly gains but a lower close on Friday, trading at 101.16 to start the day. Treasury yields are looking to start the week in focus as they show signs of renewed upward momentum, as 2-year yields rise to 4.91%, 10-year yields rise to 5.215%, and 30-year yields pushing near 5.53%. Crude oil is higher but the grains and oilseeds are widely lower to start the week as speculative length expresses its disappointment regarding more concrete progress between the U.S. and China.

Last week’s diplomatic push between the U.S. and Iran reopened a pathway toward negotiations, but the two sides remain far apart on the concessions needed to translate renewed dialogue into a durable peace agreement. President Trump over the weekend said he had rejected the latest Iranian offer, but signaled expectations of talks continuing this week. This has crude oil prices pointing higher to start the week, with nearby WTI and Brent both up 2.3% at the time of writing to trade near $94.60 and $99.70, respectively. Ongoing escalations between Russia and Ukraine add additional risk premium as well, with Ukraine striking both a refinery and oil storage facilities in Krasnodar Krai over the weekend and into Monday, while Russia maintained heavy pressure on Ukrainian logistical and power infrastructure. That casts doubt on last week’s diplomacy, with the proposed restraint on targeting energy infrastructure clearly not taking hold at this point, though the grain markets will continue to watch for progress on Turkey’s push for renewal of something similar to the Black Sea Grain Initiative of 2022/23.

The U.S. and China have reached agreement on a $30B reciprocal tariff relief framework in each direction, with roughly 90% of covered products eventually returning to Most Favored Nation tariff levels once domestic procedures are completed. The weekend announcement is more substantive than Friday's summit readout, but it is primarily a market-access agreement rather than a new Chinese purchasing pledge. While this continues to point to an easing of tensions that could look to stabilize trade relations and work towards improving the competitiveness of U.S. ag products into China, the market is still expressing its disappointment regarding a lack of concrete purchase commitments, as evidenced by the broad selloff to start trade today. The White House release noted the creation of a dedicated agricultural market-access working group, with U.S. Trade Representative Jamieson Greer noting the administration would continue “ensuring compliance with commitments on agricultural and energy purchases.” China confirmed this working group in their own release, noting the first meeting planned before the end of 2026. That keeps open the possibility of seeing improved Chinese import demand for U.S. ag products down the road but stops short of providing a material increase today.

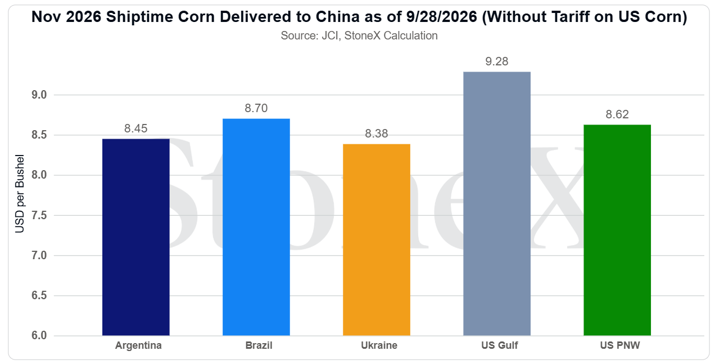
Interestingly, soybeans were left off the $30B list of products qualifying for tariff relief, with only seed beans being included—to me, this seems like a negotiating tactic. China is willing to use state-directed soybean purchases to meet the political commitment, already surpassing the halfway mark of the 25 million metric ton agreement with state buyers alone, but it is not yet willing to normalize the broader commercial soybean trade by eliminating the tariff to open this demand up to the country’s private crushers. Corn, wheat, sorghum, beef, and pork were all included, a potentially meaningful step in increasing trade down the road, but again being taken as a bit of a let down by the market which had priced in significant optimism coming in. As shown in the graphic below, the removal of this tariff makes U.S. corn look more competitive relative to the main competing origins this fall, namely South America due to Ukrainian shipments remaining largely cut off, though we’re still a bit overpriced in the immediate near-term given Argentina’s big export program following its record corn production.

Ultimately, the summit produced tangible progress, but it stopped short of resolving several of the most important structural disputes. Commercial soybean tariffs remain largely untouched, rare earths and critical-mineral export controls are still under negotiation, and implementation of the broader tariff reductions will depend on follow-through from both governments. With the current trade truce extended into January, those unresolved issues—along with the pace of Chinese agricultural purchases—will likely remain the biggest sources of uncertainty heading into the next round of negotiations. Skeptics may view this as China essentially buying time to see how things play out geopolitically in the months ahead before making any real concrete commitments, which likely keeps the headline trade in play. It’s also worth noting that China’s readout included an explicit focus on Taiwan, noting Xi urged the U.S. to oppose Taiwanese independence and handle the issue cautiously, while the U.S. did not mention the topic. There doesn’t appear to be any public release of discussion regarding the existing ~$14B arms sales package to Taiwan that has been authorized by Congress but not yet approved by Trump; this could be one of the more important unresolved sticking points to keep an eye on moving forward.

image 138147

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for September 28

September 28 – Stock futures are pointing to a lower open to start the week, with the Nasdaq and S&P 500 both remaining within shouting distance of their respective all-time highs, while the Dow Jones continues to be the laggard of the major indexes, holding in a clear downtrend after touching a three-plus month low last week. The VIX is elevated to start the week but remains on the low-end of 2026 trade, hovering just above 16 at the time of writing. The dollar is in the green again after big weekly gains but a lower close on Friday, trading at 101.16 to start the day. Treasury yields are looking to start the week in focus as they show signs of renewed upward momentum, as 2-year yields rise to 4.91%, 10-year yields rise to 5.215%, and 30-year yields pushing near 5.53%. Crude oil is higher but the grains and oilseeds are widely lower to start the week as speculative length expresses its disappointment regarding more concrete progress between the U.S. and China.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Mid-Day Commentary for September 25

September 25 – The Dow Jones continues to favor the high side of level-par through the morning hours but it is still set for a fourth straight losing week; the Nasdaq and S&P 500 are trading steady-to-lower at the time of this writing. Treasuries are slightly higher again today after hitting their highest levels in around two decades yesterday. WTI crude oil is trading lower but not materially so, below the $100 per barrel mark but almost $2/bbl off session lows as wars rage on on multiple fronts.

Mike Castle
Mike Castle
  • Grains & Oilseeds

Perspective: Morning Commentary for September 25

September 25 – The grains and oilseeds are taking the lack of breakthroughs from yesterday’s U.S. / China negotiations as bearish, and I’m not just talking about pandas. Although the overall tone of the summit was one of reconciliation and diplomacy, a welcomed development amid the environment of ongoing geopolitical tensions, there have been no concrete announcements of fresh Chinese purchase agreements for U.S. agricultural commodities as of the time of writing. It’s encouraging to see a two-month extension to the existing trade truce, now extended to January 10, as well as the plans for additional meetings between the two sides during this span, but some of the existing speculative length coming into the meeting is clearly reacting with disappointment to the duration of the extension and lack of a broader agreement. The fact that we’re continuing to see China purchase U.S. soybeans, as evidenced by yesterday’s fresh flash sale announcement, is an encouraging sign, but we still have not seen any evidence of actual progress on the alleged $17B in non-soy ag purchases—nor have we seen confirmation from China on this agreement.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.