
South American Grain Report
Brazilian soybean, corn and sorghum exports in October; Sorghum exports hit record high; Comments on the November WASDE for Brazil and Argentina
StoneX Intelligence Brazil
- Grains & Oilseeds
Quarterly Commodities Outlook is available for free now. Download your report →
StoneX Intelligence Brazil
South American grain market fundamentals
Brazilian soybean, corn and sorghum exports in October; sorghum shipments hit a new monthly record
MDIC released consolidated data on Brazilian soybean, corn and sorghum exports for October:
For more details, see this interactive report.
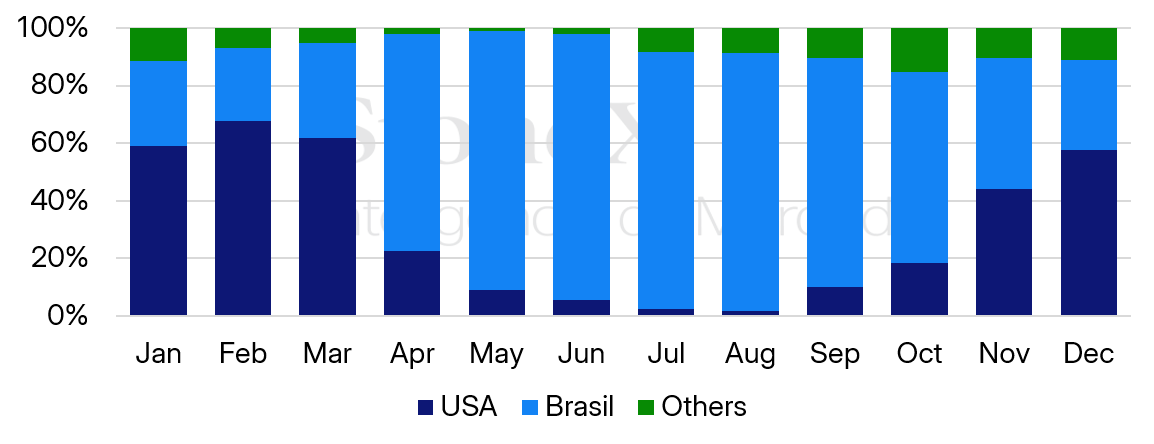
Comments: The decline in Brazilian soybean exports in October compared with September reflects the usual seasonal pattern for this time of year, as the shipping window for the domestic crop comes to a close. From now on, shipments to China should increasingly come from the U.S., which gains a larger share of the Asian country's imports after the U.S. harvest. Based on historical averages, this share should keep rising through February, and Brazil should regain its lead as China's main supplier of the commodity in April 2027.
China | Share (%) of soybean imports by origin, per month
Once again, the highlight of the month was Brazilian sorghum exports. Brazil exported 1.2 million tonnes of the grain in October, a new monthly record. Two factors explain this strong performance. The first is the growth in domestic production, as planted area has grown about 6.5-fold over the last five crop seasons.
The second, and perhaps the most important, is China opening its market. China is the world's largest sorghum importer, accounting for more than 80% of global purchases. In November 2025, it approved the first Brazilian facilities to export sorghum to the country.
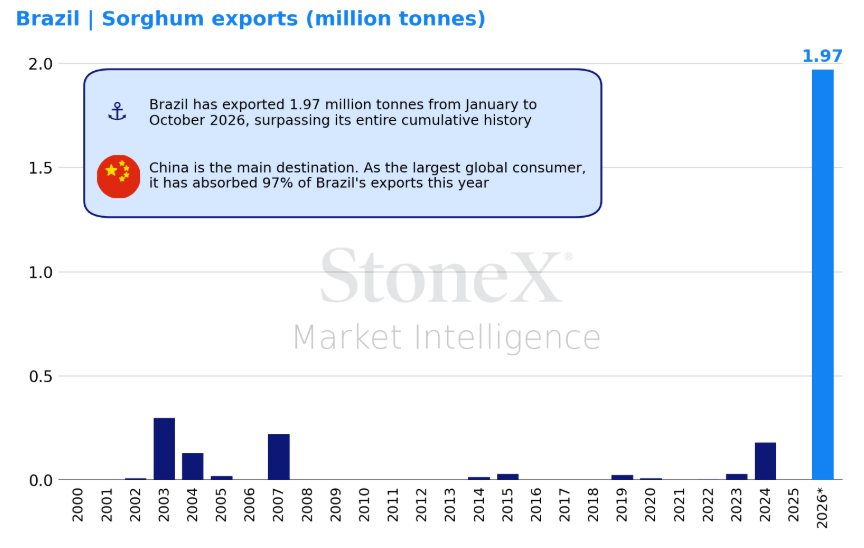
For more details, see this special report on Brazilian sorghum published by StoneX yesterday.
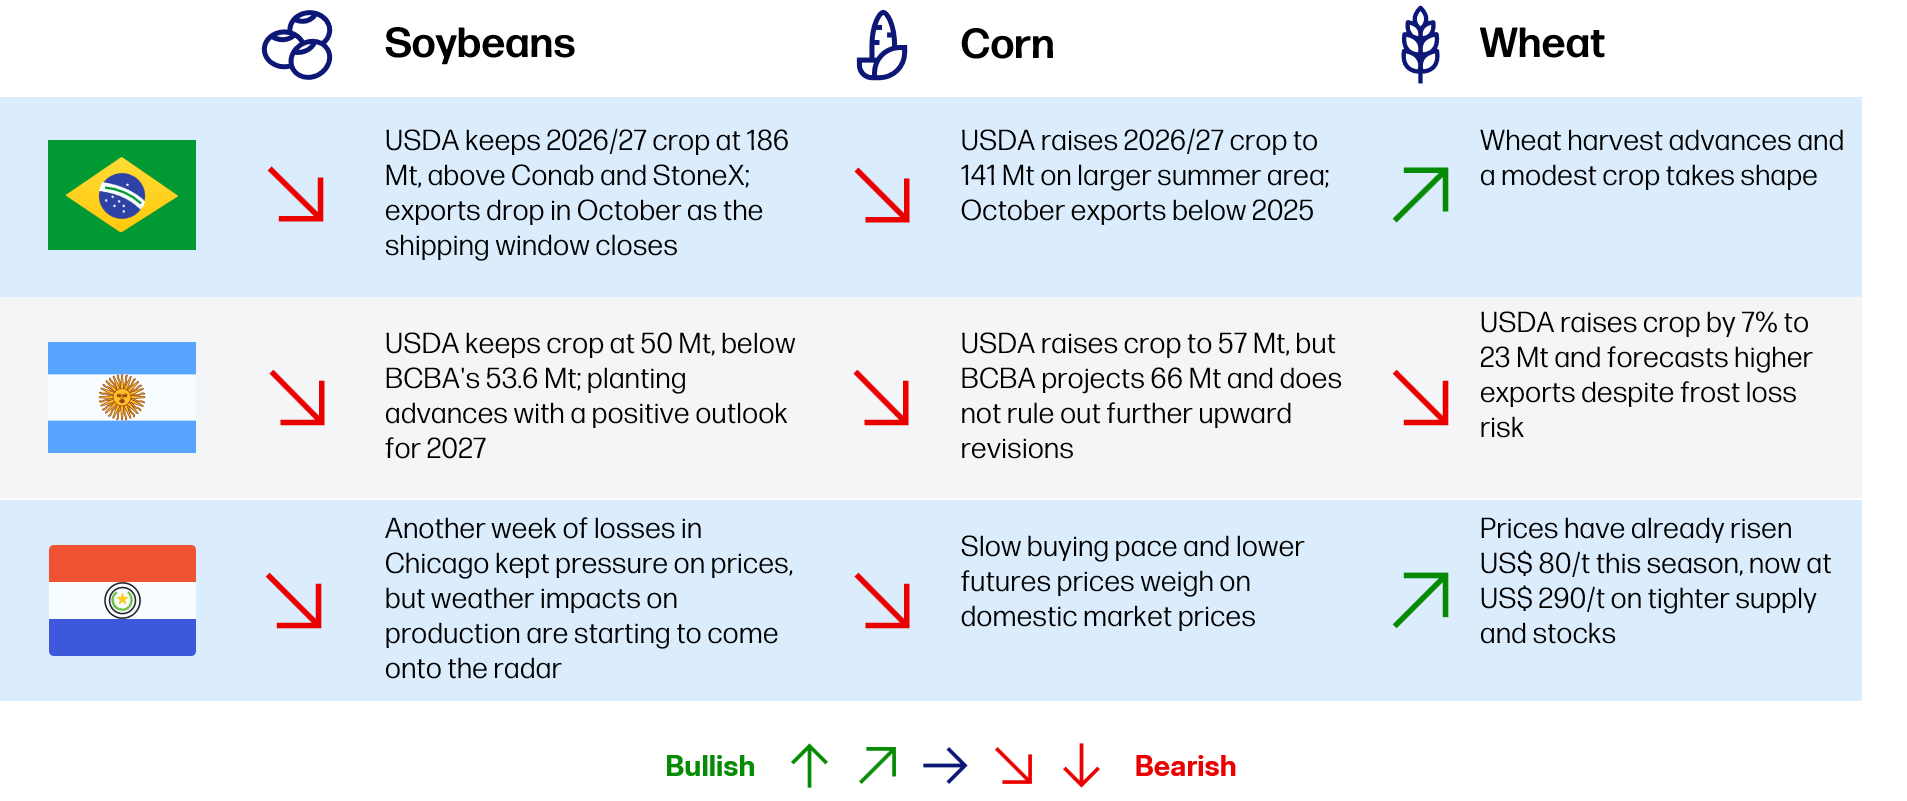
November WASDE – USDA estimates for Brazil and Argentina
USDA raises corn production estimates for both countries and keeps soybean estimates unchanged
The USDA released its November World Agricultural Supply and Demand Estimates (WASDE) report on Tuesday (Nov. 10). Its revisions for South America's 2026/27 crop were:
Comments: The report confirmed the estimates for South American crops, with no surprises for soybeans. Still, the USDA's numbers remain below local estimates for most products:
--------------------------------------------------------------------------------------------------
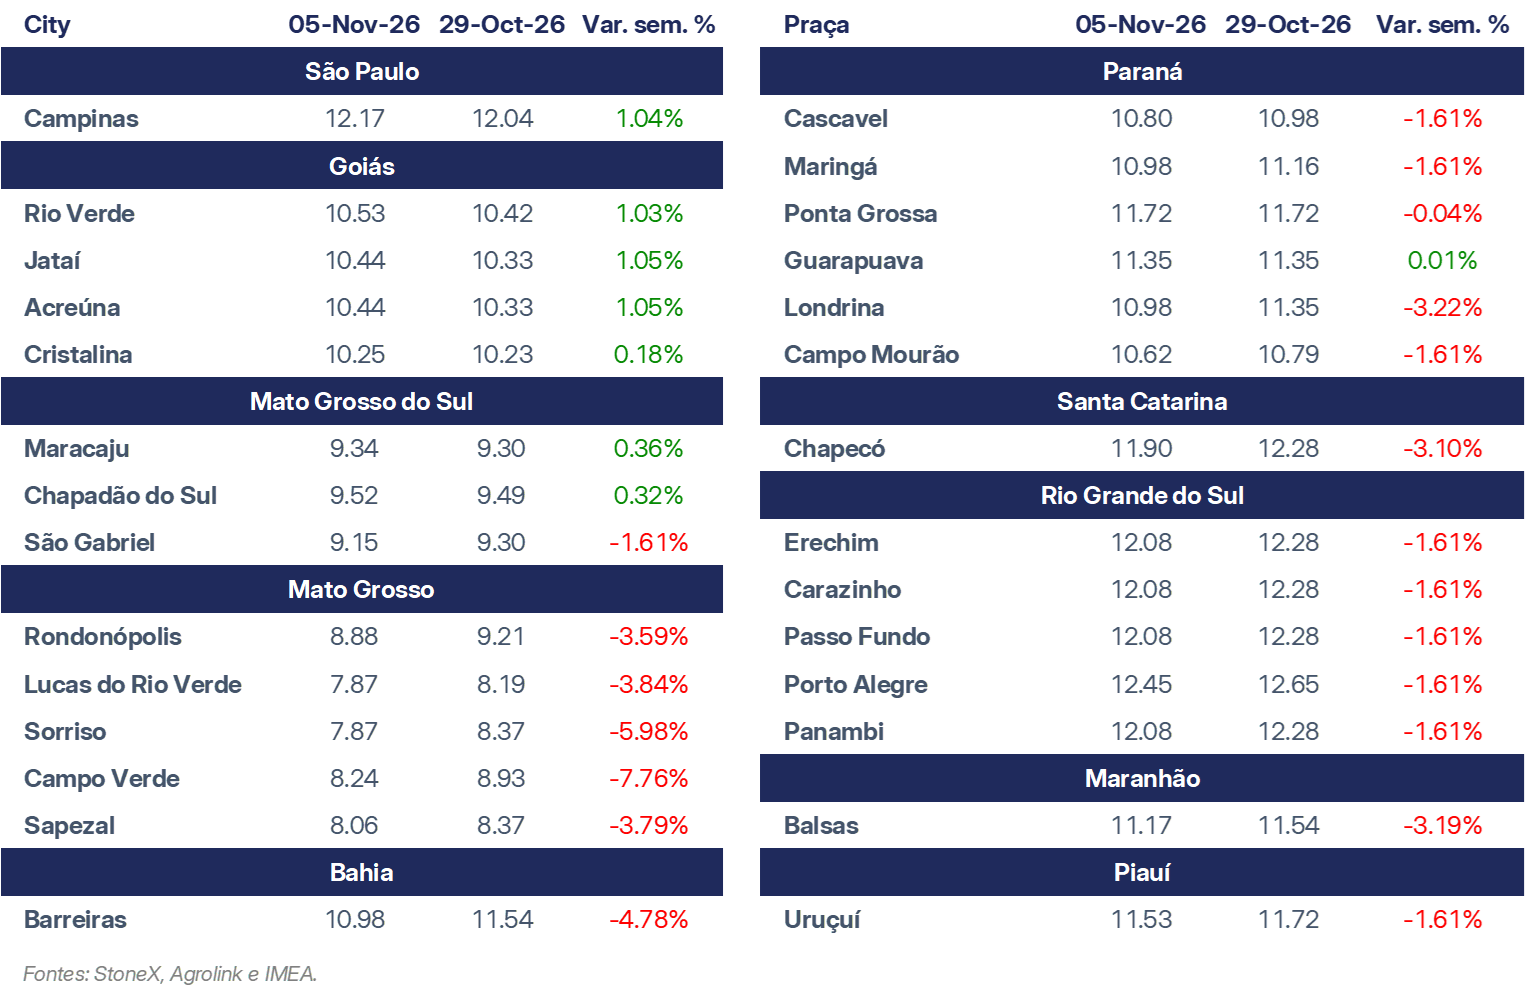
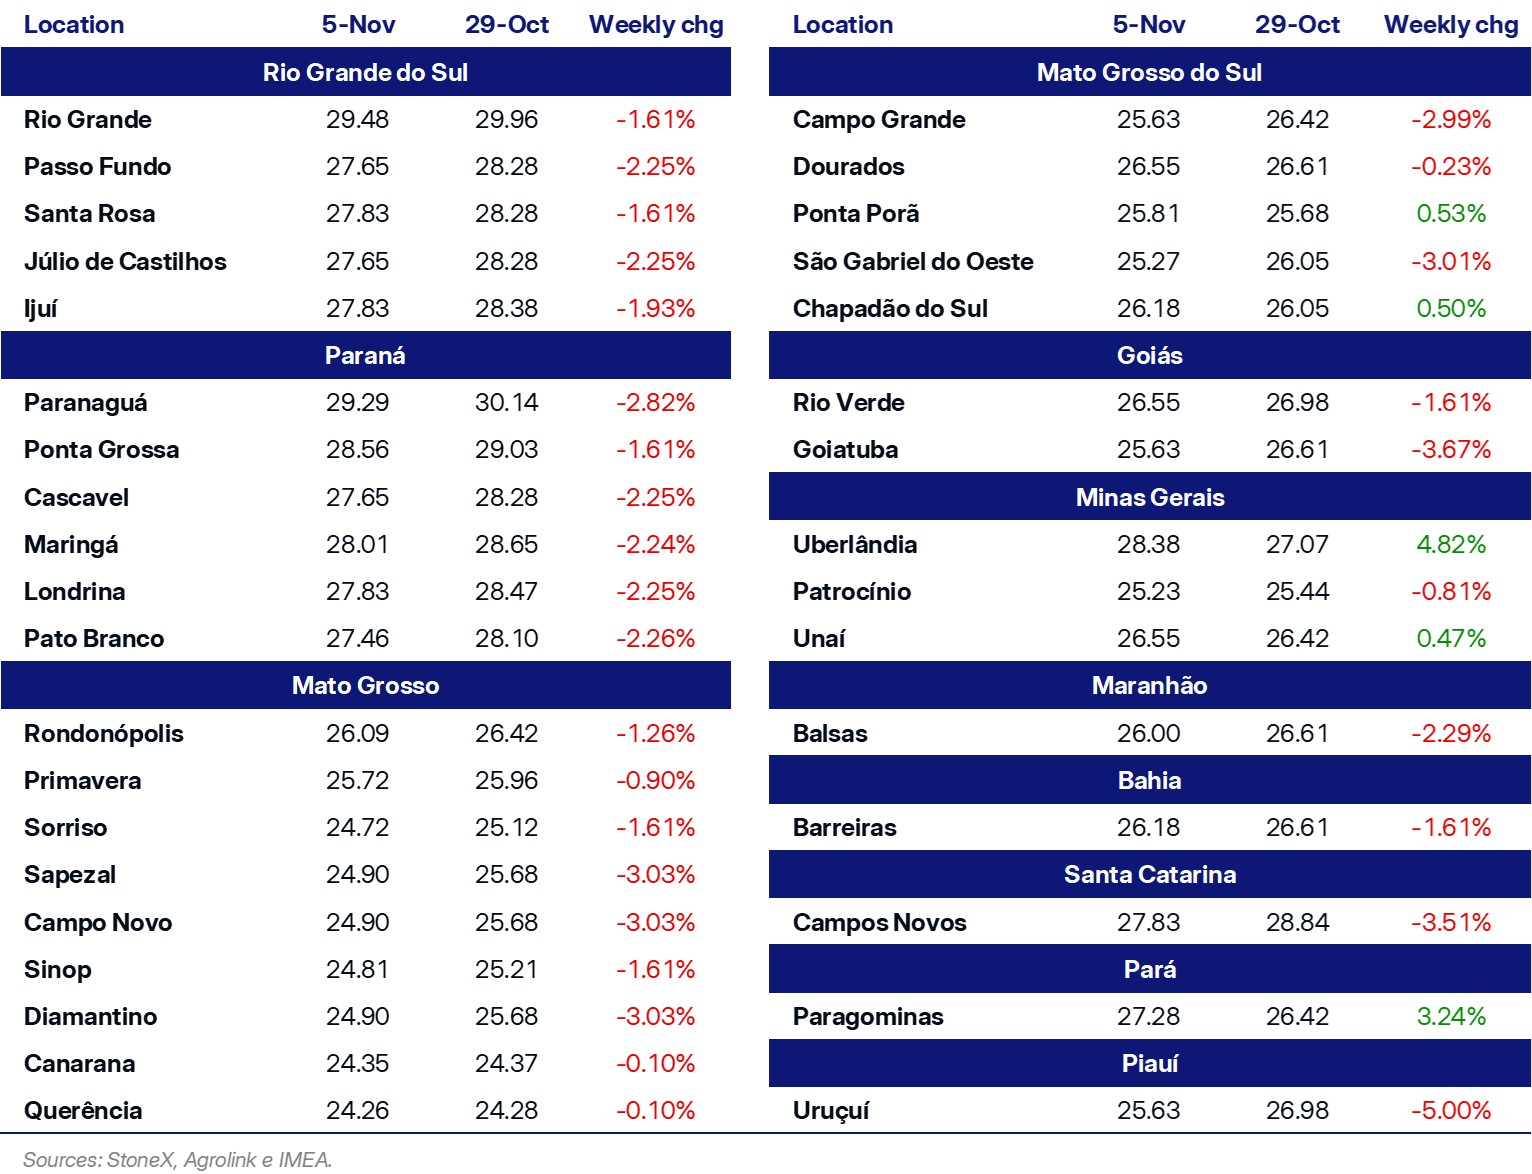
Brazil physical corn prices (BRL/bag)
The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided. References to over-the-counter (“OTC”) products or swaps are made on behalf of StoneX Markets LLC (“SXM”), a member of the National Futures Association (“NFA”) and provisionally registered with the U.S. Commodity Futures Trading Commission (“CFTC”) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ (“ECP”) and who have been accepted as customers of SXM. StoneX Financial Inc. (“SFI”) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (“SEC”) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Adviser. References to securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to exchange-traded futures and options are made on behalf of the FCM Division of SFI . StoneX is a trading name of StoneX Financial Ltd (“SFL”). SFL is registered in England and Wales, Company No. 5616586. SFL is authorized and regulated by the Financial Conduct Authority [FRN 446717] to provide to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorised to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorised & regulated by the Financial Conduct Authority under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorised by the Financial Conduct Authority. StoneX Group Inc. acts as agent for SFL in New York with respect to its payments services business. StoneX APAC Pte. Ltd. acts as agent for SFL in Singapore with respect to its payments services business. ‘StoneX’ is the trade name used by StoneX Group Inc. and all its associated entities and subsidiaries.
Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.
© 2026 StoneX Group Inc. All Rights Reserved.
Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.
Brazilian soybean, corn and sorghum exports in October; Sorghum exports hit record high; Comments on the November WASDE for Brazil and Argentina
November 11 – Stock futures are pointing to a stronger open, particularly in the tech heavy Nasdaq following a fresh sigh of relief for the sector after CoreWeave’s third quarter earnings results. The mood on Wall Street is calming as the VIX is notably lower to start the day, currently hovering at its lowest level in a week near the 18.4 mark. The dollar is adding to yesterday’s gains after the hotter than expected October CPI data reinforced fears of a more hawkish Fed, currently up 0.5% to trade at 102.73. Treasury yields surged higher yesterday but markets are closed today in observance of Veterans Day; 2-year yields yesterday settled 20-basis points higher at 4.748%, 10-year yields just under 14-basis points higher at 5.00%, and 30-year yields 10-basis points higher at 5.358%. Crude oil prices are bouncing from sharp early week losses, with nearby WTI up 0.9% on the day to trade near $87.20 and nearby Brent up 1.5% to trade near $92.90. The ags are mixed to start the day, with corn and soybeans showing modest losses after the big post-WASDE jump yesterday, while the wheat complex is clinging to small gains at the break following fresh escalations between Russia and Ukraine that we’ll dive into below. Stock futures are pointing to a lower open in classic turnaround Tuesday fashion as they look to take back some of yesterday’s sharp gains. The VIX is up 5.7% from yesterday’s close, currently sitting just above 21, though well below the recent highs above 28 seen last week. The dollar is looking at a turnaround Tuesday as well, up 0.3% to trade near 102 at the time of writing. Treasury yields are sharply higher to start the session, with 2-year yields up near 15-basis points to trade near 4.70%, 10-year yields up 9-basis points to trade near 4.955%, and 30-year yields up 6-basis points to trade just below 5.32%. Crude oil prices are continuing lower amid de-escalatory rhetoric coming from the Trump administration, with nearby WTI down 2.2% on the day to trade below $84.50 while nearby Brent is down 3.4% to trade near $89.40. Meanwhile, the ags are quietly lower at the break.
November 10 – October CPI inflation data came in slightly hotter than expected this morning, with headline CPI rising 0.4% month-on-month and core CPI rising 0.3% month-on-month, both of which were 0.1% above the average analyst estimate. Year-on-year figures were not published due to last October’s government shutdown, but we can interpolate using the CPI index itself. If we take the average of last September and November’s CPI index of 324.461, it would imply a headline CPI increase of 4.0% year-over-year, which would be an acceleration from the 3.7% seen in September and the hottest reading since May. Given the major build-up of inflationary pressures already seen at the producer level, it’s no surprise to see the pass-through to the consumer taking place, as we’ve been pointing to for months. Stock futures are pointing to a lower open in classic turnaround Tuesday fashion as they look to take back some of yesterday’s sharp gains. The VIX is up 5.7% from yesterday’s close, currently sitting just above 21, though well below the recent highs above 28 seen last week. The dollar is looking at a turnaround Tuesday as well, up 0.3% to trade near 102 at the time of writing. Treasury yields are sharply higher to start the session, with 2-year yields up near 15-basis points to trade near 4.70%, 10-year yields up 9-basis points to trade near 4.955%, and 30-year yields up 6-basis points to trade just below 5.32%. Crude oil prices are continuing lower amid de-escalatory rhetoric coming from the Trump administration, with nearby WTI down 2.2% on the day to trade below $84.50 while nearby Brent is down 3.4% to trade near $89.40. Meanwhile, the ags are quietly lower at the break.
Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.
Reach
With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.
Transparency
As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.
Expertise
From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.