StoneX logo

Perspective: Mid-Day Commentary for September 23

By: Mike Castle, Market Intelligence - Fertilizer Analyst

September 23 – Stocks remain in the red at midday, with the Nasdaq and S&P 500 appearing to be taking a bit of a breather after their sharp rally to start the week, with additional weakness hanging over the sector amid resurgent treasury yields, particularly in the long-end of the curve. 2-year yields are trading back above 4.89%, 10-year yields are trading near 5.106%, and 30-year yields are pushing near 5.40%. The VIX is modestly higher but still on the low side of recent history as it hovers near the 15-mark. The dollar has broken above the 101 level for the first time since late July on expectations of higher rates ahead, especially amid surging yields, adding to the sharp gains seen this week. Crude oil is continuing its bounce after the sharp drop seen since late last week, with nearby WTI up 2.75% on the day to trade at $92.30 and nearby Brent up 3.8% to trade near $103 at the time of writing. The grains and oilseeds finished the session widely lower, while the cattle market saw a solid rebound today, particularly in the forwards.

U.S. commercial crude oil stocks unexpectedly rose 2.969 million barrels week-on-week, reversing course from analyst expectations of a 0.641-million-barrel draw and marking the first build in four weeks. That brings U.S. crude oil stocks excluding the SPR to 426.4 million barrels, a four-week high. Perhaps even more importantly, this week’s build in crude stocks was not a function of big SPR releases, with the SPR only seeing a 410k barrel weekly draw, effectively in line with the 400k seen in the week prior. I’d like to point out that the average weekly withdrawal from the SPR in September is now only ~685k barrels per week, a dramatic slowdown from the weekly average of ~4.55 million in August and the 8+ million per week seen at the height of the move in late spring/early summer. With that said, total crude oil stocks in the SPR of 284.55 million barrels are still the lowest since late October 1982 and not far from the all-time low of roughly 270M; the slowdown in weekly draws at least extends the timeframe for which we would break that all-time low. Part of this was a function of weekly crude exports falling to their lowest since early May at 1.55 million barrels, as well as a notable drop in refinery inputs to 16.81 million barrels, with refinery utilization dropping 2.8% week-on-week to 94.0%, the lowest level since May. This is likely in part due to Exxon’s Joliet refinery outage, evidenced further by the huge drop in PADD 2 (Midwest) run rates. For what it’s worth, it does sound like that facility is now in the middle of a staged restart this week, with no public confirmation from Exxon for when it will return to full run rates but watching next week’s report and more likely the following week (10/7) should show us the evidence of when the refinery is back up to full speed.

The refined product side was uglier, however, with U.S. gasoline stocks falling 1.686 million barrels week-on-week, a huge miss versus the average analyst estimate of a 0.095-million-barrel build and also the sharpest draw in four weeks. That puts total U.S. gasoline stocks at 206.05 million barrels, the tightest at this point in the year since 2012. Distillate stocks fell 0.428 million barrels week-on-week, slightly better than the estimated 0.633 million, reversing course after three consecutive weekly builds. Total U.S. distillate stocks now sit at 107.43 million barrels, the tightest at this point in the year on record.

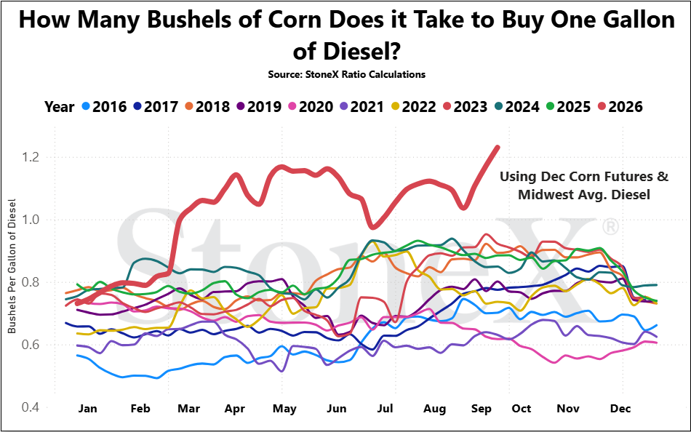
Tying this back to the ag side, the Joliet refinery going down just as harvest enters full swing equates to about the worst timing possible for Midwestern ag demand. National average retail on highway diesel prices rose to another fresh all-time high in today’s EIA data at $6.53/gallon, a weekly increase of $0.24/gallon, but the pressure was much worse in the Midwest (PADD 2). Midwest average diesel prices also posted a fresh all-time high this week at $6.68/gallon, but that was a whopping $0.43/gallon weekly rise, the sharpest since the beginning stages of the war in early March. The graphic below puts this into perspective, comparing the ratio of Midwest average diesel prices to December corn futures. This helps gain a sense of the strain at the farm level for those who did not lock in their fuel needs in advance, which I would assume to be the overwhelming majority. In practical terms, there’s no real way around this—

farmers are not going to leave their crops in the field to rot just because fuel prices are too high. Effectively, that just translates into margin pressure, something worth keeping an eye on moving forward, especially as we move into the fall fertilizer application season.

image 138012

  • Grains & Oilseeds

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for September 25

September 25 – The grains and oilseeds are taking the lack of breakthroughs from yesterday’s U.S. / China negotiations as bearish, and I’m not just talking about pandas. Although the overall tone of the summit was one of reconciliation and diplomacy, a welcomed development amid the environment of ongoing geopolitical tensions, there have been no concrete announcements of fresh Chinese purchase agreements for U.S. agricultural commodities as of the time of writing. It’s encouraging to see a two-month extension to the existing trade truce, now extended to January 10, as well as the plans for additional meetings between the two sides during this span, but some of the existing speculative length coming into the meeting is clearly reacting with disappointment to the duration of the extension and lack of a broader agreement. The fact that we’re continuing to see China purchase U.S. soybeans, as evidenced by yesterday’s fresh flash sale announcement, is an encouraging sign, but we still have not seen any evidence of actual progress on the alleged $17B in non-soy ag purchases—nor have we seen confirmation from China on this agreement.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for September 24

September 24 – Angst in the bond market and increasing expectations of higher for longer interest rates has stock futures pointing to a lower open today, with trade likely to be volatile around headlines from today’s Trump/Xi meeting. Treasury yields yesterday rose to fresh multi-year highs across the curve, with the biggest moves seen in the long end. Most notably, 30-year yields made a new high not seen since 2004, 10-year yields made highs not seen since 2007, and 2-year yields made new highs not seen since early 2024. They do look to be coming off of these highs to start the day, with 2-year yields back down to 4.85%, 10-year yields at 5.10%, and 30-year yields at 5.40% at the time of writing. The VIX is pushing to its highest level of the week back above 16, but it’s worth noting this remains on the low-end of 2026’s trade. The dollar is continuing its surge higher as well amid the aforementioned rising rate expectations, posting another near two-month high above the 101.3 mark. Crude oil is bouncing from its recent bottom but remains notably lower than trade over the last two weeks, with nearby WTI trading at $93.70 and nearby Brent trading at $99.80 at the time of writing. The ags are largely mixed, with soybeans showing the most strength at the break with all eyes on today’s Trump/Xi meeting, with major implications for the sector.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Mid-Day Commentary for September 23

September 23 – Stocks remain in the red at midday, with the Nasdaq and S&P 500 appearing to be taking a bit of a breather after their sharp rally to start the week, with additional weakness hanging over the sector amid resurgent treasury yields, particularly in the long-end of the curve. 2-year yields are trading back above 4.89%, 10-year yields are trading near 5.106%, and 30-year yields are pushing near 5.40%. The VIX is modestly higher but still on the low side of recent history as it hovers near the 15-mark. The dollar has broken above the 101 level for the first time since late July on expectations of higher rates ahead, especially amid surging yields, adding to the sharp gains seen this week. Crude oil is continuing its bounce after the sharp drop seen since late last week, with nearby WTI up 2.75% on the day to trade at $92.30 and nearby Brent up 3.8% to trade near $103 at the time of writing. The grains and oilseeds finished the session widely lower, while the cattle market saw a solid rebound today, particularly in the forwards.

Mike Castle
Mike Castle
  • Grains & Oilseeds
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.