StoneX logo

Perspective: Morning Commentary for September 15

By: Mike Castle, Market Intelligence - Fertilizer Analyst

September 15 – The Fed’s September meeting kicks off today with the market pricing in strong expectations of a 25-basis point hike being announced tomorrow as CME’s FedWatch now shows the probability of such a hike at 92.5%. This is currently expected to be followed up with a hold in October and one more 25-basis point hike in December. Hot inflation data, particularly concentrated at the producer level for now, is signaling the FOMC to move rates higher, while an impressively resilient U.S. labor market gives them permission to do so. It’s worth keeping in mind that this does set the table for a more significant surprise if the FOMC opts to hold steady, which I would not rule out at this point. The other thing worth keeping a close eye on is how much additional tightening is implied moving into 2027. New Fed Chair Kevin Warsh has been rather explicit in his intention for the Fed to provide less forward guidance and fade more into the background, but traders will surely be parsing through all his comments with a fine-tooth comb to shape their expectations for what lies ahead.

Stock futures are pointing to a turnaround Tuesday to start the day, while the VIX is holding effectively steady with where it ended yesterday near the 17 level. The dollar is in the green as the Fed meeting kicks off as traders price in expectations of higher rates ahead. Treasuries will likely remain in focus today with the 10-year yield back above that psychological 5.00% this morning, while 2-year yields firm to 4.65% on expectations of a hike tomorrow, and 30-year yields resume their push higher to hang around 5.375% at the time of writing. Crude oil is moderately higher to start the day, with nearby WTI up 0.8% to trade near $102.70 and nearby Brent up 1% to trade near $106.70. Fighting in Yemen continues to intensify, with the air response from the Saudis increasing while the Houthis launch widespread strikes targeting a variety of Saudi Red Sea port cities, most notably at the critical site of Yanbu. The ags are mostly lower to start the day with the wheat complex leading the way down again following perceived momentum in improving commodity flow through the Black Sea, while no fresh bullish fodder for corn or soybeans was found in yesterday’s Crop Progress report.

U.S. corn conditions rebounded 1% week-on-week to sit at 57% good/excellent, reversing course from the average analyst estimate of a 1% decline to 55%. This remains 10% below last year, as well as 2% below the previous five-year average at this time. Corn harvest advanced another 3% week-on-week to reach 8% complete, 1% slower than expected but still sitting ahead of last year’s 7% and the previous five-year average pace of 6%. The widespread heatwaves seen to finish the growing season have certainly sped up maturity but scattered heavy rains across the Midwest in the last week ultimately kept somewhat of a lid on progress at the national level. Meanwhile, U.S. soybean ratings held steady at 58% good/excellent, matching expectations, while we also got our first report of soybean harvest progress of the year, pegged at 6% complete nationally. This was notably above the average estimate of 5% and is double the previous five-year average pace of 3% at this time, again reflecting the rapid maturation due to recent excessive heat.

U.S. spring wheat harvest is nearing completion, advancing another 7% week-on-week to reach 93% complete. Spring wheat harvest had been notably ahead of schedule for much of the year but has slowed down at the tail-end following rain delays primarily seen in Montana, leading this week’s pace to now match this time last year and sit only 1% ahead of the average pace. It’s worth noting the harvest delays seen on the other side of the border as well, with Saskatchewan and Manitoba catching another round of rain over the last 24 hours, as localized totals up to 2” are likely pushing combines out of the field again. We’ll continue keeping an eye on not just the harvest delays on the Canadian Prairies, but also the rising potential for quality issues, with the ultimate question being whether or not this translates to additional demand for U.S. exports in the year ahead. While spring wheat season ends, winter wheat planting season is just entering full swing, advancing another 6% week-on-week to reach 8% complete, also matching analyst estimates. This is a bit behind schedule, however, trailing last year’s pace by 2% and the five-year average pace by 4%, with the delays primarily being seen across the Plains.

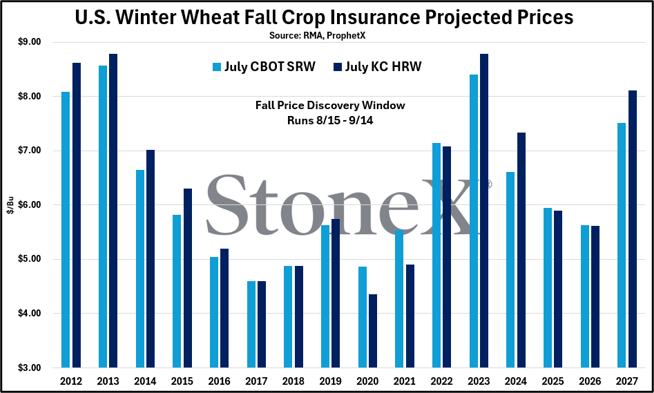
Given the poor state of soil moisture profiles seen in much of the traditional U.S. hard red winter wheat belt, it’s not a huge surprise to see farmers hesitant to go plant into dust today, as USDA’s subsoil moisture index for both Oklahoma and Texas are currently at their lowest level for the comparable week since at least 2015. Forecasts do show plenty of chances of rain for the Plains over the next two weeks, which should help drive more significant advancement if they verify. The sharp rally in wheat prices was well timed for prospective U.S. winter wheat growers, with yesterday marking the end of the fall Projected Price discovery period for 2027 crop insurance purposes. July 2027 Chicago wheat futures averaged $7.51/bushel during the period, with July 2027 Kansas City wheat futures averaging $8.11/bushel. As shown in the graphic below, this is a dramatic improvement from last year, with Chicago up $1.88/bushel and KC up $2.50/bushel, both marking their highest in four years and giving farmers an incentive to increase winter wheat acres in the year ahead.  

image 137550

  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

This material should be construed as market commentary and represents the opinions and viewpoints of the author, and does not reflect tailored advice associated with any specific account.


The views are current only through the date stated and are subject to change at any time based upon market or other conditions, and StoneX Group Inc. (“SGI”) disclaims any responsibility to update such views. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. Past performance does not guarantee future results.


The StoneX Group Inc. group of companies provides financial services worldwide through its subsidiaries, including physical commodities, securities, exchange-traded and over-the-counter derivatives, risk management, global payments and foreign exchange products in accordance with applicable law in the jurisdictions where services are provided.


References to certain OTC products or swaps are made on behalf of StoneX Markets, LLC (SXM), a member of the National Futures Association (NFA) and provisionally registered with the U.S. Commodity Futures Trading Commission (CFTC) as a swap dealer. SXM’s products are designed only for individuals or firms who qualify under CFTC rules as an ‘Eligible Contract Participant’ and who have been accepted as customers of SXM.


StoneX Financial Inc. (SFI) is a member of FINRA/NFA/SIPC and registered with the MSRB. SFI is registered with the U.S. Securities and Exchange Commission (SEC) as a Broker-Dealer and with the CFTC as a Futures Commission Merchant and Commodity Trading Advisor. StoneX Financial (Canada) Inc. (SFCI) is registered in Canada and is a member of CIRO and CIPF. References to certain securities trading are made on behalf of the BD Division of SFI and are intended only for an audience of institutional clients as defined by FINRA Rule 4512(c). References to certain exchange-traded futures and options are made on behalf of the FCM Division of SFI. Wealth Management is offered through SA Stone Wealth Management Inc., member FINRA/SIPC, and SA Stone Investment Advisors Inc., an SEC-registered investment advisor, both wholly owned subsidiaries of SGI.

R.J. O’Brien & Associates, LLC (RJO) is registered with the CFTC as a Futures Commission Merchant and is a member of NFA.


StoneX Financial Ltd (SFL) is registered in England and Wales, company no. 5616586. SFL is authorized and regulated by the Financial Conduct Authority (FCA) (registration number FRN:446717) to provide services to professional and eligible customers including: arrangement, execution and, where required, clearing derivative transactions in exchange traded futures and options. SFL is also authorized to engage in the arrangement and execution of transactions in certain OTC products, certain securities trading, precious metals trading and payment services to eligible customers. SFL is authorized and regulated by the FCA under the Payment Services Regulations 2017 for the provision of payment services. SFL is a category 1 ring-dealing member of the London Metal Exchange. In addition SFL also engages in other physically delivered commodities business and other general business activities which are unregulated and not required to be authorized by the FCA.


This communication is issued in the European Economic Area by StoneX Financial Europe GmbH (SFEG). StoneX is the trade name used by STONEX GROUP INC. and all its associated entities and subsidiaries. StoneX Financial Europe GmbH (“SFEG”) is a securities trading firm registered in Germany under Company No. HRB 80844.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism. SAP is an “Approved International Trading Company” authorized to act as a “Spot Commodity Broker” under the Commodity Trading Act.


StoneX Financial Pte Ltd (Co. Reg. No 201130598R) (“SFP”) is regulated by the Monetary Authority of Singapore and is a Capital Markets Service Licence holder (for dealing in capital market products), an Exempt Financial Adviser (for advising on investment products and issuing or promulgating analyses/ reports on investment products) and a Major Payment Institution (for domestic and cross-border money transfer services).


SFP may distribute analysis/report produced by its respective foreign affiliates within the StoneX Group of companies pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations Recipients should contact SFP at (65) 6309 1000 for any matters arising from, or in connection with, this webinar.


StoneX APAC Pte. Ltd. (“SAP”) (Co. Reg. No 200616676W) is regulated as a Dealer (PS20190001002) under the Precious Stones and Precious Metals (Prevention of Money Laundering and Terrorism Financing) Act 2019 for purposes of anti-money laundering and countering the financing of terrorism.


StoneX Financial (HK) Limited (CE No.: BCQ152) (“SHK”) is regulated by the Hong Kong Securities and Futures Commission for Dealing in Securities and Dealing in Futures Contracts.


StoneX Financial Pty Ltd (ACN 141 774 727) holds an Australian Financial Service License (AFSL: 345646) for Dealing in Securities, Exchange-Traded Derivatives Contracts, OTC Derivatives Contracts and Foreign Exchange Contracts, and is regulated by the Australian Securities and Investments Commission.


StoneX Securities Co., Ltd. (“SSJ”) (Co. Reg. No 010401047199) is regulated by the Japanese Financial Services Agency as a Type-I Financial Instruments Business Operator (Kanto Local Finance Bureau (FIBO)No.291’), is a member of the Financial Futures Association of Japan for dealing and broking FX and FX Option transactions, and is a member of the Japan Securities Dealers Association for dealing and broking stock indices and option transactions.


Trading swaps and over-the-counter derivatives, exchange-traded derivatives and options and securities involves substantial risk and is not suitable for all investors. Past performance of any futures or option is not indicative of future success. Indicators are not a trading system and are not published as a specific trade recommendation. The information herein is not a recommendation to trade nor investment research or an offer to buy or sell any derivative or security. It does not take into account your particular investment objectives, financial situation or needs and does not create a binding obligation on any of the StoneX group of companies to enter into any transaction with you. You are advised to perform an independent investigation of any transaction to determine whether any transaction is suitable for you. No part of this material may be copied, photocopied or duplicated in any form by any means or redistributed without the prior written consent of StoneX Group Inc.


The report/analysis herein is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation.


© 2026 StoneX Group Inc. All Rights Reserved.

Satellite view of Earth at night showing illuminated cities across Asia and the Middle East

Discover more insights

Our subscribers have access to comprehensive market analysis from StoneX spanning commodities, equities, currencies and more.

Related articles for Grains & Oilseeds

Perspective: Morning Commentary for September 15

September 15 – The Fed’s September meeting kicks off today with the market pricing in strong expectations of a 25-basis point hike being announced tomorrow as CME’s FedWatch now shows the probability of such a hike at 92.5%. This is currently expected to be followed up with a hold in October and one more 25-basis point hike in December. Hot inflation data, particularly concentrated at the producer level for now, is signaling the FOMC to move rates higher, while an impressively resilient U.S. labor market gives them permission to do so. It’s worth keeping in mind that this does set the table for a more significant surprise if the FOMC opts to hold steady, which I would not rule out at this point. The other thing worth keeping a close eye on is how much additional tightening is implied moving into 2027. New Fed Chair Kevin Warsh has been rather explicit in his intention for the Fed to provide less forward guidance and fade more into the background, but traders will surely be parsing through all his comments with a fine-tooth comb to shape their expectations for what lies ahead.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Morning Commentary for September 14

September 14 – The week is set to kick off with stocks lower and oil higher following fresh deterioration in the Middle East, with the timing of the fresh rise in energy prices supporting the case of the hawks prior to the Fed’s September meeting that begins tomorrow. CME’s FedWatch now shows over 88% odds of a 25-basis point hike at this week’s meeting, with one more hike being priced in by year’s end. It’s a very light day of economic data, putting more market focus on the weekend’s notable geopolitical developments. The VIX matched last Thursday’s month-plus high at 18.17 overnight; it is now off its high as it trades near 17.6, but it’s worth noting that is up 11% from Friday’s close, reflecting these elevated concerns. The dollar is firming in response to these expectations of a more hawkish Fed, up 0.5% on the day to trade back above 99.6 for the first time in nearly two weeks. Treasuries are quietly mixed, largely remaining at or near multi-year highs as 2-year yields trade at 4.643%, 10-year yields at 4.979%, and 30-year yields at 5.359%. Nearby WTI is trading at a nearly four-month high around $104.30 at the time of writing, while nearby Brent is up 4.7% on the day to trade at $109.50. The ags traded mixed in the overnights but are mostly looking at small gains to kick off the week after an ugly Friday selloff following the release of the September WASDE.

Mike Castle
Mike Castle
  • Grains & Oilseeds
  • Energy
  • Dairy
  • Renewable Fuels
  • Cocoa
  • Coffee
  • Cotton
  • Sugar
  • Meats & Livestock
  • Forest Products

Perspective: Mid-Day Commentary for September 11

September 11 – The major stock indexes are all up roughly 1% at midday, with the VIX cooling notably to hang below 15.7, erasing yesterday's gains. The dollar continues to linger around unchanged, currently trading at 99.06. The front-end of the treasury yield curve continues to push higher amid increasingly hawkish rate expectations, with 2-year yields up to 4.615%, while 10-year yields are up more modestly to 4.955%, and 30-year yields are slightly lower on the day at 5.347%. Crude oil is still in the red as traders take weekly profits and assess Monday’s planned talks in Oman, with nearby WTI trading near $99.6 and nearby Brent trading near $105.2 at the time of writing. The ags are largely mixed, with corn reversing course and rebounding to trade in the green following the release of this morning’s September WASDE.

Mike Castle
Mike Castle
  • Grains & Oilseeds
StoneX: We open markets

Our market expertise, advanced platforms, global reach, culture of full transparency and commitment to our clients’ success all set us apart in the financial marketplace.

Reach

With access to 40+ derivatives exchanges, 180+ foreign exchange markets, nearly every global securities marketplace and numerous bi-lateral liquidity venues, StoneX’s digital network and deep relationships can take clients anywhere they want to go.

Transparency

As a publicly traded company meeting the highest standards of regulatory compliance in the markets we serve; our financials and record of accomplishment are matters of public record. StoneX’s commitment to “doing the right thing over the easy thing” sets us apart in the industry and helps us build respect, client trust and new partnerships.

Expertise

From our proprietary Market Intelligence platform, to “boots on the ground” expertise from award-winning traders and professionals, we connect our clients directly to actionable insights they can use to make more informed decisions and achieve their goals in the global markets.