Weekly round-up for StoneX Bullion
Rhona O'Connell, Head of Market Analysis, EMEA & Asia
Tel: +44 203 580 6115 / mobile +44 7384 833897
26th October 2026
Weekly round-up for StoneX Bullion; Rhona O'Connell, Head of Market Analysis,
EMEA & Asia, 26th October Tel +44 203 580 6115 / +44 7384 833897
- Sentiment remained sour in the gold and silver markets last week and the technical picture has deteriorated for both as a result. Pressure on the equity markets from sharp falls in the tech sector saw gold offloaded in an effort to hike liquidity while silver again underperformed on concerns over fundamental deterioration.
- The developments over the weekend, with Iran reported to be meeting negotiators from Saudi Arabia, Pakistan and Turkey at the start of this week, may prevent escalation, at least in the short term, while the press is reporting concerns over possible renewed hostilities post mid-term elections (3td November);
- This week sees the Israel general election (Tuesday 27th) which is currently too close to call; plus the FOMC meeting Tuesday and Wednesday.
- Continued Russian official sector selling, plus offloading from Kazakhstan, again underpin gold’s role as an insurance policy and may well be deterring some potential buyers -ETF activity is instructive in this regard – notably 10.5t of net redemptions at the end of last week.
Opinion is largely unchanged
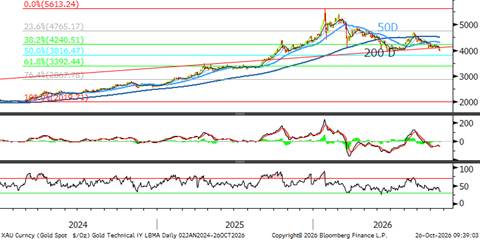
Gold has started this week with a mild relief rally, taking it towards $4,020 after posting a low on Friday 23rd of $3,976 during New York hours. With the above-listed geopolitical and financial uncertainties surrounding the market we are not expecting much by way of aggressive positioning and the bond markets are likely to remain the key driver as they respond in turn to external developments.
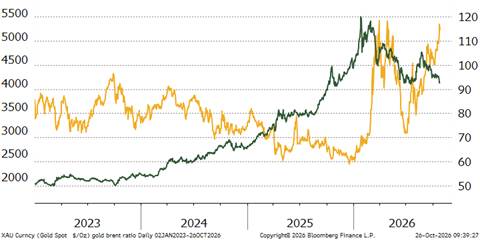
Last week‘s key influences were again a combination of geopolitical risk and rising inflation fears. Escalating Iran-related conflict and Houthi attacks on Saudi Arabia pushed Brent crude to $117/barrel, from as low as $70 in early July and unwinding 84% of the fall from its April high of $126 and contributing to concern that inflation, and by association bond yields, would stay “higher-for-longer”. would stay high and central banks would keep rates elevated—or tighten further.
Meanwhile Festival buying is picking up in India with local prices posting premia to London. Diwali starts on 8th November.
Also in India, the government is reported to have issued import quotas of up to 6,000t of silver, to remain in place for six months. This is likely to ease any possible tightness in India as buying picks up ahead of Diwali and the following wedding seasons. We have written a separate not on this, putting it into context, which can be found here.
Gold; uptrend under attack immediate support $3,940. Resistance $4,298 - $4,498
Source; Bloomberg, StoneX
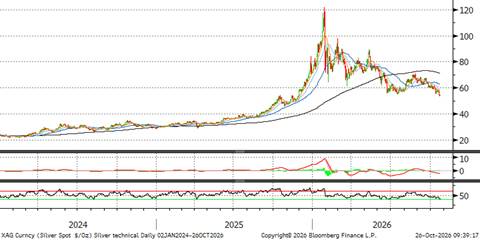
Silver is still unloved, continuing to underperform and sliding to an intraday low of $53.0 on Friday as the market washed out in the face of gold’s drop, and continuing to show concern over potential threats to industrial offtake – not just the much-mentioned (temporary) over supply of solar cells amid continued thrifting and some competition from copper, but also the pressure on the high-tech stocks in the US at least, and ahead of the earnings season. Meta reported on the 21st; Microsoft and Alphabet report on the 28th and Amazon on the 29th. Meta’s Q3 revenues were up 26% year-on-year (to $64.60Bn) ginally ahead of consensus expectations, but operating profit was down 37%, largely on the back of a legal settlement over social media and teenagers’ mental health.
We are expecting silver to throw off a surplus equivalent to roughly seven weeks’ global fabrication demand this year. If liquidation from ETPs is taken into account then that excess rises to roughly eleven weeks’ demand.
Silver support $52.3; resistance from $56.8 to $63.0 and then at $71.3
Source; Bloomberg, StoneX
Précis of our note on US inflation numbers
As noted in the Fed’s Beige Book Survey, commercial firms have, until now at least, been reluctant to pass price increases through to the consumer given the latter’s resistance and lack of confidence. But if PPI continues to run substantially higher than CPI, there may come a point where commercial entities are forced to pass it through or else absorb much reduced margins. Where is the tipping point?
For the full analysis, please follow this link
The correlation between Brent and the 10Y yield is coming off pretty steeply
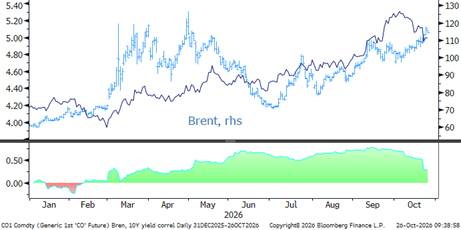
Source; Bloomberg, StoneX
Key long bond yields, long-term and the 5Y-30Y spread; yield curve continues to flatten
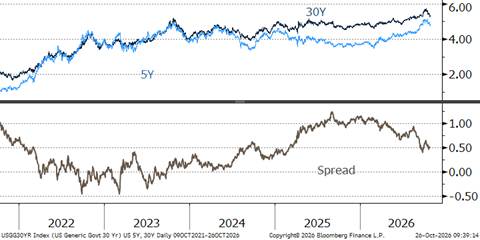
Source for both charts: Bloomberg, StoneX
Inventories, ETFs; poor sentiment prevails
COMEX gold stocks fell for a third consecutive session on 23rd October and ended the week 4.5t, or 0.6%, lower at 724t, the lowest level since the Gold Enhanced Delivery Contract was closed on 22nd September.
The ETFs were little changed over the week, down 1.3t to 3,146t, though this masks a build to 3,159t on 21st October followed by an outflow of 10.5t on the 23rd, the largest daily outflow since 31st August.
Managed money cut its net long for an eighth consecutive week, by 9.0t, or 2.7%, to 324t on 20th October, the lowest since 26th May, taking the reduction since the 450t peak on 25th August to 126t. This time the move came from long liquidation of 11.8t, which took the gross long to 376t, its lowest since 7th April, while 2.8t of shorts were covered.
Silver positioning deteriorated sharply for a fourth week: the net long fell by 329t, or 38%, to 545t, the lowest since 27th February 2024, as 388t of new shorts took the gross short to 1,971t, the highest since 30th December 2025, more than offsetting 59t of fresh buying.
The physical market again moved the other way. COMEX stocks rose by 135t, or 1.3%, to 10,516t, the highest since 5th October, and the ETFs edged up by just 9.4t to 25,066t, still the highest since 25th March.
.Gold COMEX positioning, Money Managers (t)
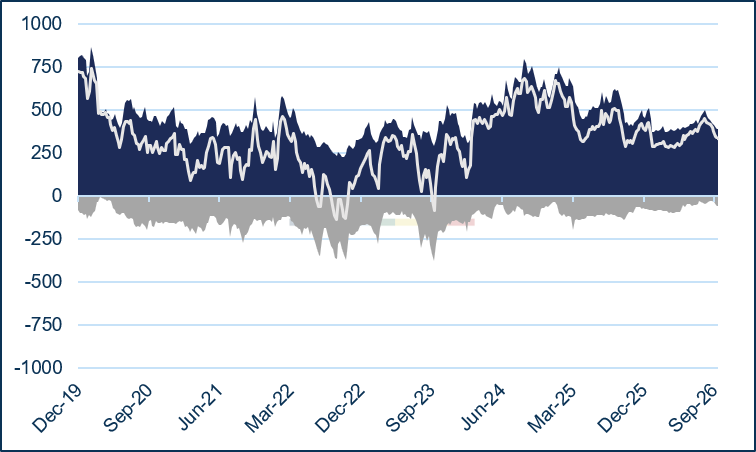
Source: CFTC/Bloomberg, StoneX
Declining open interest in both gold and silver on COMEX
COMEX Managed Money Gold Longs as % of 1st continuation Open Interest
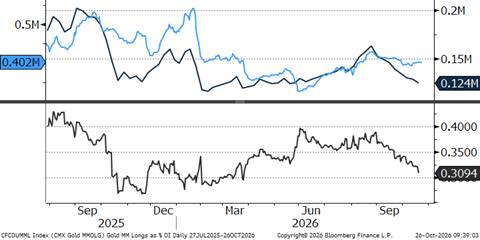
Source: Bloomberg, StoneX
COMEX Managed Money Silver Positioning (t)
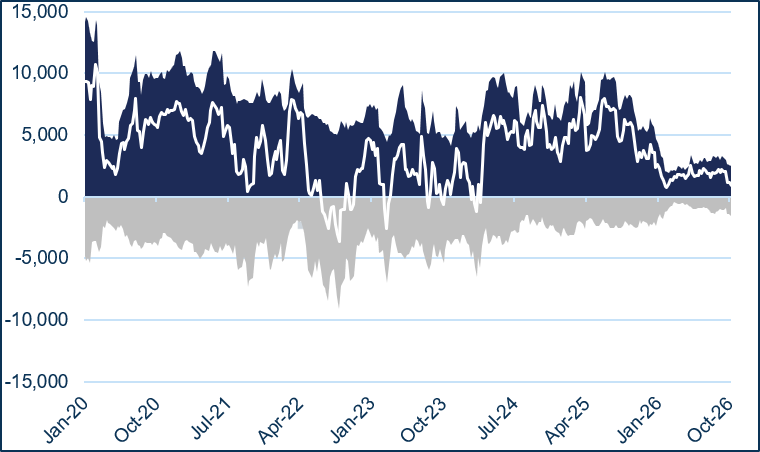
Source: CFTC/Bloomberg, StoneX
COMEX Managed Money Silver Longs as % of 1st continuation Open Interest
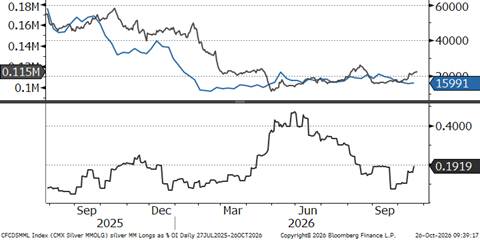
Source: Bloomberg, StoneX
The S&P, gold and copper; S&P/gold correlation steady at 0.51 while S&P:Cu correlation is also steady; latest at 0.41
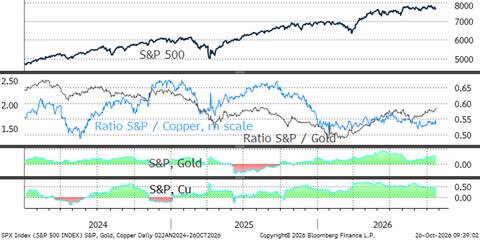
Source: Bloomberg, StoneX
Gold, silver and copper correlations; silver-gold a lot easier at 0.73 silver-copper, down to 0.31 as silver comes under pressure
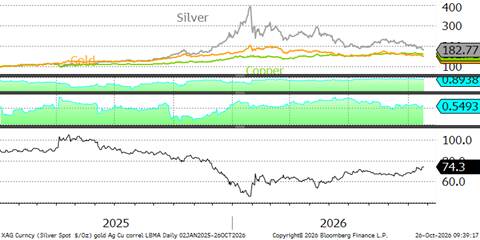
Gold:Brent ratio
Gold in key local currencies. Year-to-date, up 1.8% in Rupee terms, down 4.0% in US$
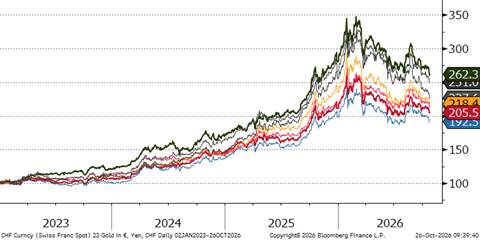
Source for above charts; Bloomberg, StoneX
Gold:silver ratio
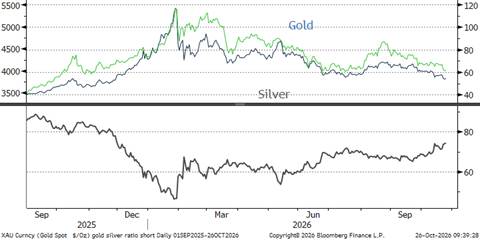
Source: Bloomberg, StoneX
| | 26 October 2026 | Previous week | % change | Year-to-date | Range Jan 2024 onwards | | Range as % |
| | | | | | Min | Max | |
| Gold (pm LBMA price) | 4,018.10 | 4,140.72 | -2.96% | -7.25% | 3,976.50 | 5,417.21 | 36.23% |
| Silver (LBMA price) | 58.66 | 62.05 | -5.47% | -23.41% | 57.42 | 116.70 | 103.25% |
| Platinum (pm LBMA price) | 1,629.94 | 1,632.90 | -0.18% | -28.41% | 1,552.52 | 2,054.12 | 32.31% |
| Palladium (pm LBMA price) | 1,271.77 | 1,271.28 | 0.04% | -25.94% | 1,047.11 | 2,054.12 | 96.17% |
| S&P 500 | 7,623.68 | 7,659.44 | -0.47% | 11.37% | 4,688.68 | 7,818.93 | 66.76% |
| $:€ | 1.1202 | 1.1239 | -0.33% | -4.41% | 1.0244 | 1.2041 | 17.54% |
Source: Bloomberg, StoneX