
US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.
Written by
Matt Weller
Head of Market Research
- US Core PCE expectations are for a 0.3% m/m (3.4% y/y) print.
- This will be the last Core PCE print before the FOMC’s monetary policy meeting on October 28, where traders are pricing in 70% odds that the central bank will raise interest rates
- The technical outlook for the US Dollar Index
Wednesday’s Core PCE report could have an outsized impact on expectations for the Federal Reserve’s next move, with markets already debating whether policymakers will hike again in October or wait until December.
Economists broadly expect core PCE to rise 0.3% month-over-month in August, up from 0.2% in July, leaving the annual rate around 3.3% to 3.4%. Headline PCE is expected to rise roughly 0.4% to 0.5% on the month.
That makes 0.3% the key hurdle.
A 0.4% core reading would be difficult for the Fed to dismiss, particularly after its September rate hike, and could strengthen the case for another move at the October 27-28 meeting. A 0.2% print or lower would point in the opposite direction, giving policymakers more reason to wait and assess incoming data.
The details may matter even more than usual. The Bureau of Economic Analysis will publish its annual update to the national accounts alongside the August report, meaning recent inflation history could be revised. Some economists expect methodology changes to lower previously reported core inflation, so traders should watch the revised three- and six-month annualized rates rather than focusing only on the August year-over-year figure.
Consumer demand will be another important part of the release. Personal income is expected to rise around 0.5%, while spending forecasts are clustered around 0.8% to 0.9%. Another strong spending print would suggest households remain resilient despite higher rates, potentially making the Fed less comfortable assuming inflation will cool on its own.
The policy backdrop is straightforward. The Fed raised rates by 25 basis points in September to 3.75% to 4.00%, while the latest dot plot showed the median policymaker expecting one additional quarter-point hike before year-end.
That puts the focus on timing. A hot inflation print, upward revisions and strong spending would favor the October debate moving in a more hawkish direction. An in-line report would likely keep October and December both in play.
Wednesday’s report is also the final PCE release before the October meeting, raising the stakes for Treasury yields, the US dollar and broader risk sentiment.
US Dollar Technical Analysis: DXY Weekly Chart
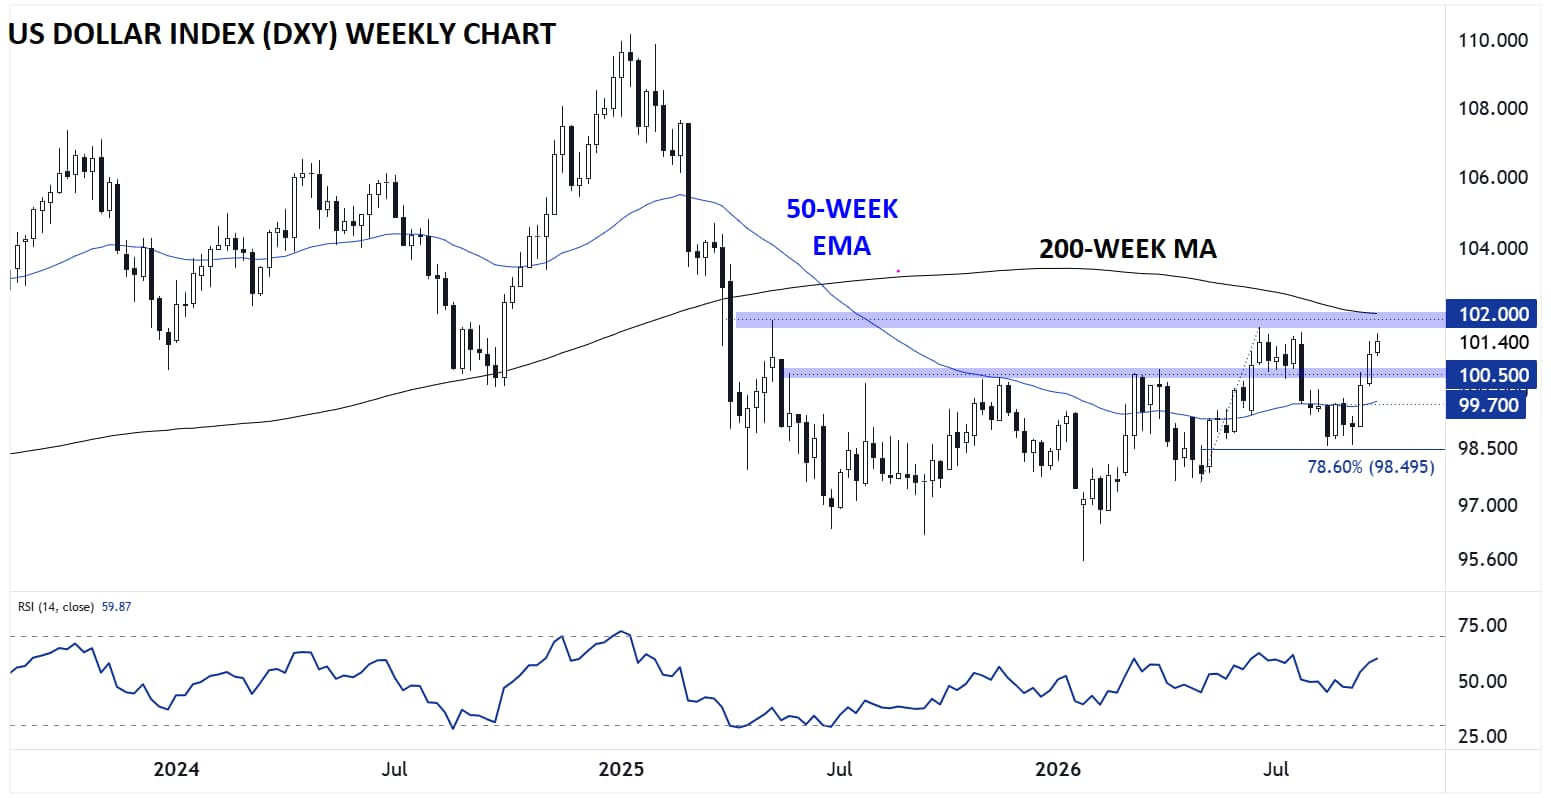
Source: TradingView, StoneX
The US Dollar Index has seen a strong rally this month, taking the broad measure of the strength of the world's reserve currency back toward its highest level since April 2025. A hotter-than-expected Core PCE reading (and its likely impact on the FOMC's October meeting) could bring the 102.00 resistance level into play in short order, whereas any inflation relief may be brushed off as stale and lead to only a short-term dip back toward 101.00.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX
Related tags:
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
Nasdaq 100 Forecast: NDX slips ahead of Fed Chair Warsh’s speech
U.S. stocks are edging lower on Friday, giving back some of yesterday's gains after Nvidia's strong outlook revived the tech trade. The focus has now shifted firmly to Fed Chair Kevin Warsh's Jackson Hole speech, with investors looking for more clarity on the outlook for interest rates.


EUR/USD forecast: All eyes on Warsh at Jackson Hole - Forex Friday
For much of this week, the EUR/USD has been edging lower with the US dollar regaining some ground after last week’s sell-off that was triggered, in part, by the bond market worries. Investors have been unwilling to bet further against the US dollar so far this week ahead of Kevin Warsh’s keynote speech at the Jackson Hole summit, due later today.


Bitcoin Forecast: BTC/USD Back to $80K Ahead of Warsh’s Jackson Hole Speech
After surging over $15,000 in the past 10 days alone, there is risk of a near-term pullback if Warsh says anything remotely hawkish at Jackson Hole - what are the levels to watch from here?