EUR/USD Short Squeeze Underway as Yields Drag US Dollar Lower
EUR/USD short squeeze gathers pace as US Treasury yields retreat, despite strong GDP and sticky inflation. Fed and ECB policy expectations remain in focus.
Written by
Matt Simpson
Market Analyst
EUR/USD is gaining momentum as falling Treasury yields undermine the US dollar, despite stronger GDP growth and stubborn inflation. With record bearish positioning in euro futures and the Fed reluctant to signal further tightening, the short squeeze could have further to run.
Euro Rebounds as Falling Treasury Yields Weigh on the US Dollar
US GDP Accelerates, but Consumer Spending Loses Momentum
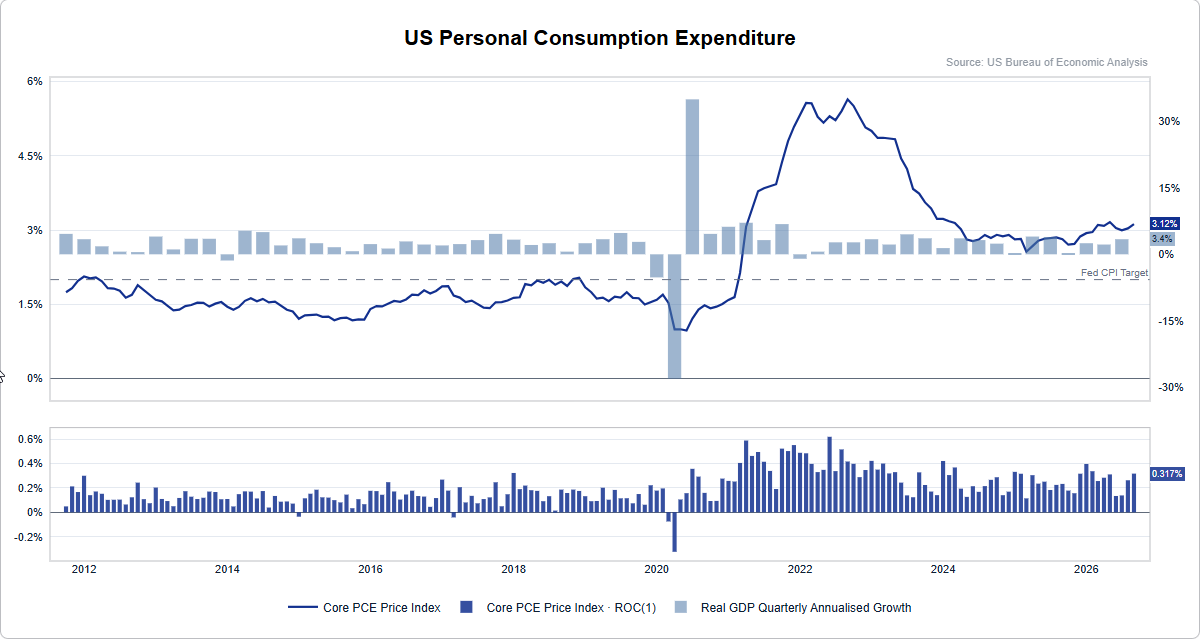
The US dollar weakened despite GDP growth accelerating to 3.4% annualised in Q3 and core PCE inflation reaching 3.1% y/y. However, quarterly core inflation eased to 2.5% annualised from 3.3%, while real consumer spending stalled in September despite growing 3.8% annualised over Q3. Real disposable income also fell 0.3% m/m, suggesting households entered Q4 with less spending power.
Treasury yields fell across the curve as bond-market volatility continued to subside. With inflation broadly matching forecasts and the Fed unwilling to commit to further tightening, the data failed to generate a fresh hawkish repricing. Meanwhile, weakness in technology shares may have encouraged demand for Treasuries, adding downward pressure to yields.
ECB Holds Rates, but December Hike Remains in Play
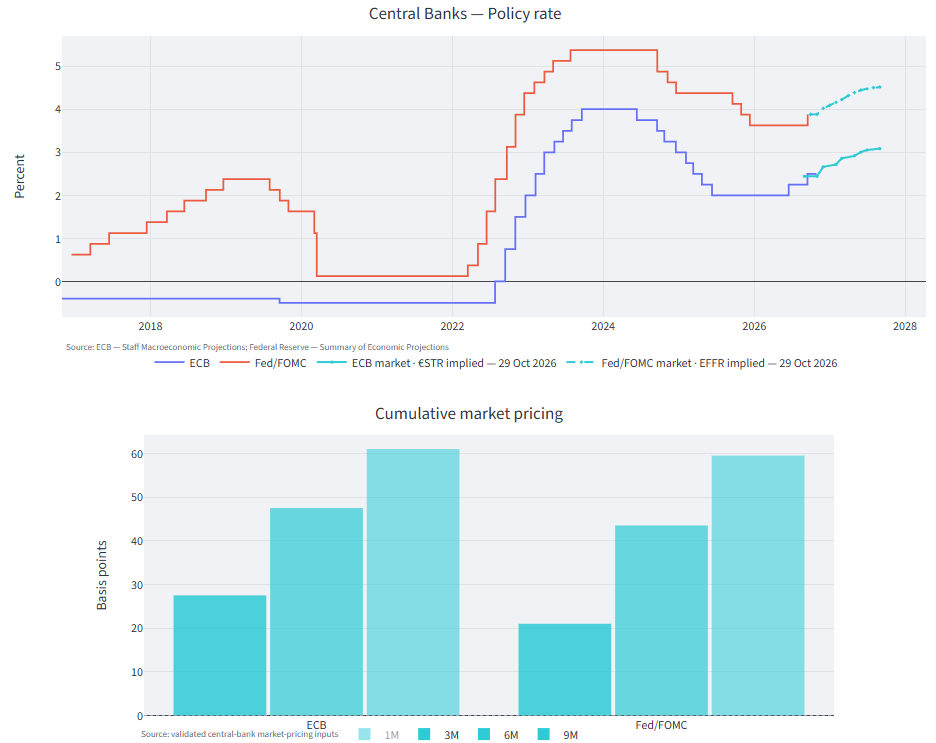
The ECB held its deposit rate at 2.5% as expected, although the meeting carried a hawkish undertone as rising energy prices increased inflation risks. President Lagarde confirmed policymakers had discussed hiking immediately, but opted to wait for further data amid tighter financing conditions and concerns about economic growth.
A 25bp ECB hike in December now looks increasingly likely, although rising bond yields could limit how far policymakers can tighten thereafter. Market pricing suggests the ECB could tighten slightly faster than the Fed over the near term, although both central banks are expected to deliver around 60bp of cumulative hikes over six months. This leaves EUR/USD sensitive to relative bond yields and positioning, particularly given the sentiment extremes that could leave the euro vulnerable to a short squeeze.
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
Falling Treasury yields and bond volatility weigh on the US dollar
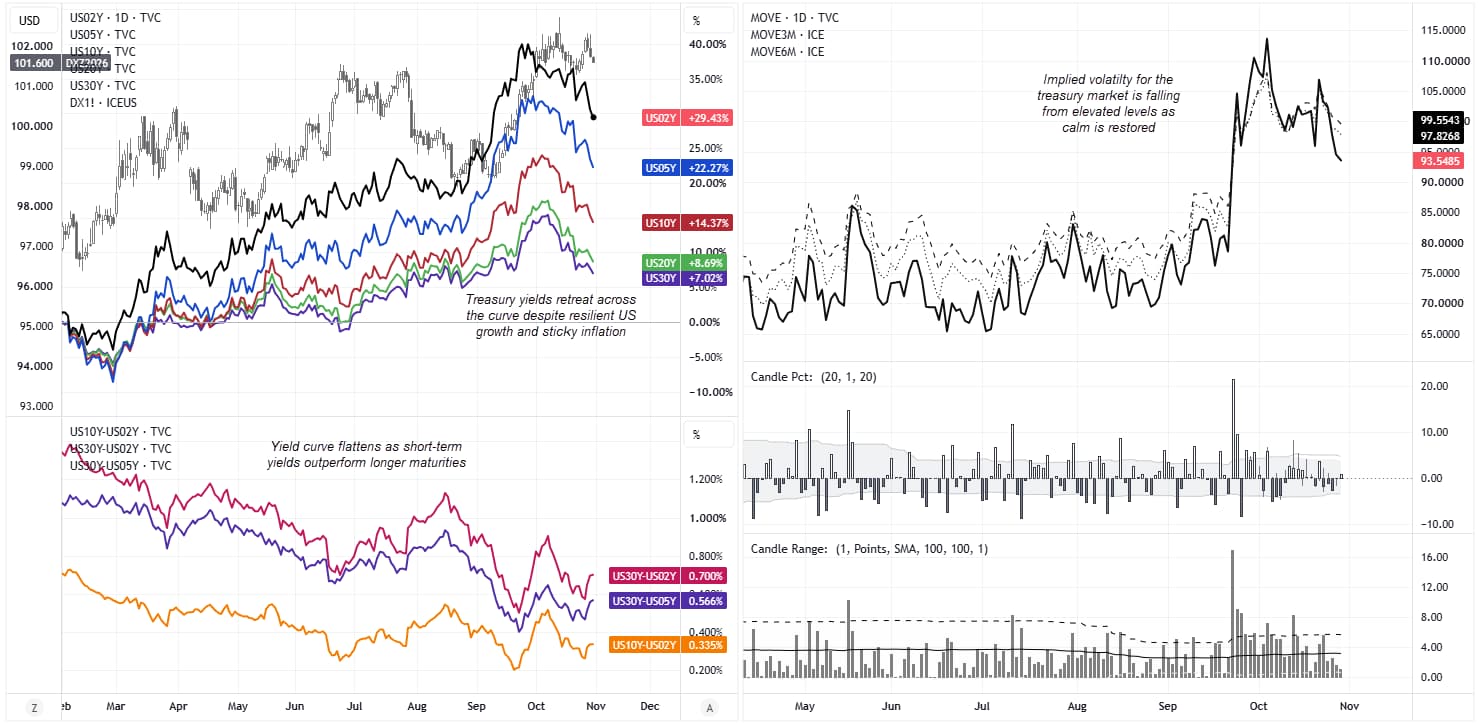
Despite stronger US growth and elevated inflation, Treasury yields have fallen sharply from their October highs across the curve. Shorter-dated yields have experienced the largest percentage increases this year, with the two-year up nearly 30%, compared with around 14% for the 10-year and 7% for the 30-year. This has contributed to a substantial flattening of the yield curve, with the 10-year versus two-year spread narrowing to around 33bp from over 100bp earlier this year.
Meanwhile, the MOVE index has fallen towards 95, below its three- and six-month averages, pointing to declining Treasury-market volatility. The combination of falling yields and subdued volatility suggests markets are becoming less concerned about further aggressive tightening, despite stubborn inflation. Demand for Treasuries amid weakness in technology shares may also be contributing to the decline in yields.
The dollar's failure to rally on stronger economic data is therefore telling. For now, falling Treasury yields and a reassessment of the Fed's longer-term policy path appear to be outweighing the hawkish economic headlines. That could bode well for the euro, particularly given the sentiment extremes I previously warned could leave it vulnerable to a short squeeze.
US Dollar Index (DXY) Technical Outlook
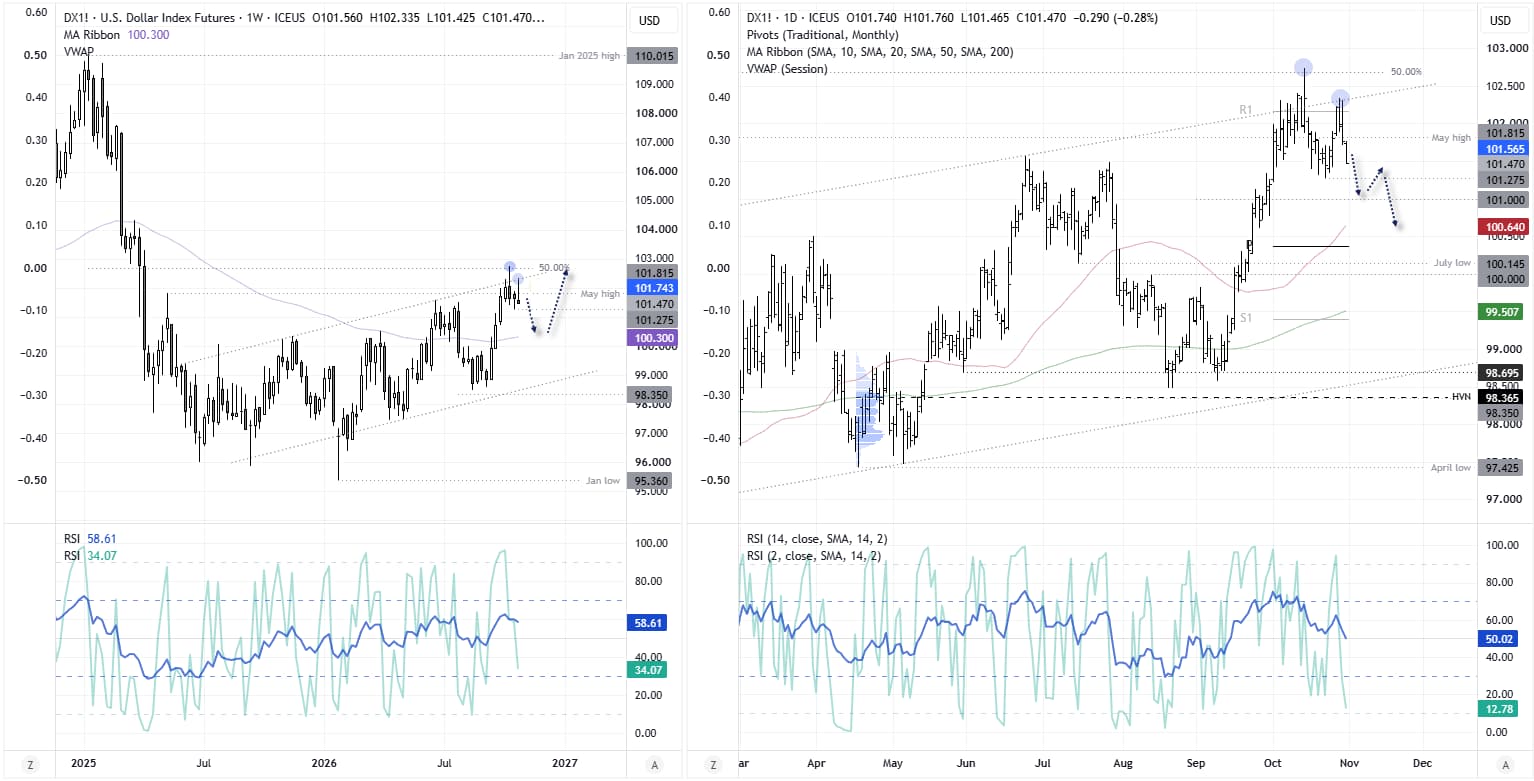
The weekly charts shows how the dollar rally has stalled around the upper trend channel – after an inverted hammer candle met resistance around a long-term 50% level. At current prices, the USD index is on track for a shooting star week – which could also be a lower high. And with prices also beneath the May high, perhaps bears could gain some momentum if incoming US data even slightly lowballs.
The daily chart shows the lower more prominently, and bearish momentum is picking up pace. Perhaps a move down to 101 is on the cards, a break beneath which brings the 50-day SMA into focus.
Source: ICE, TradingView
EUR/USD Technical Outlook: Euro vs US Dollar
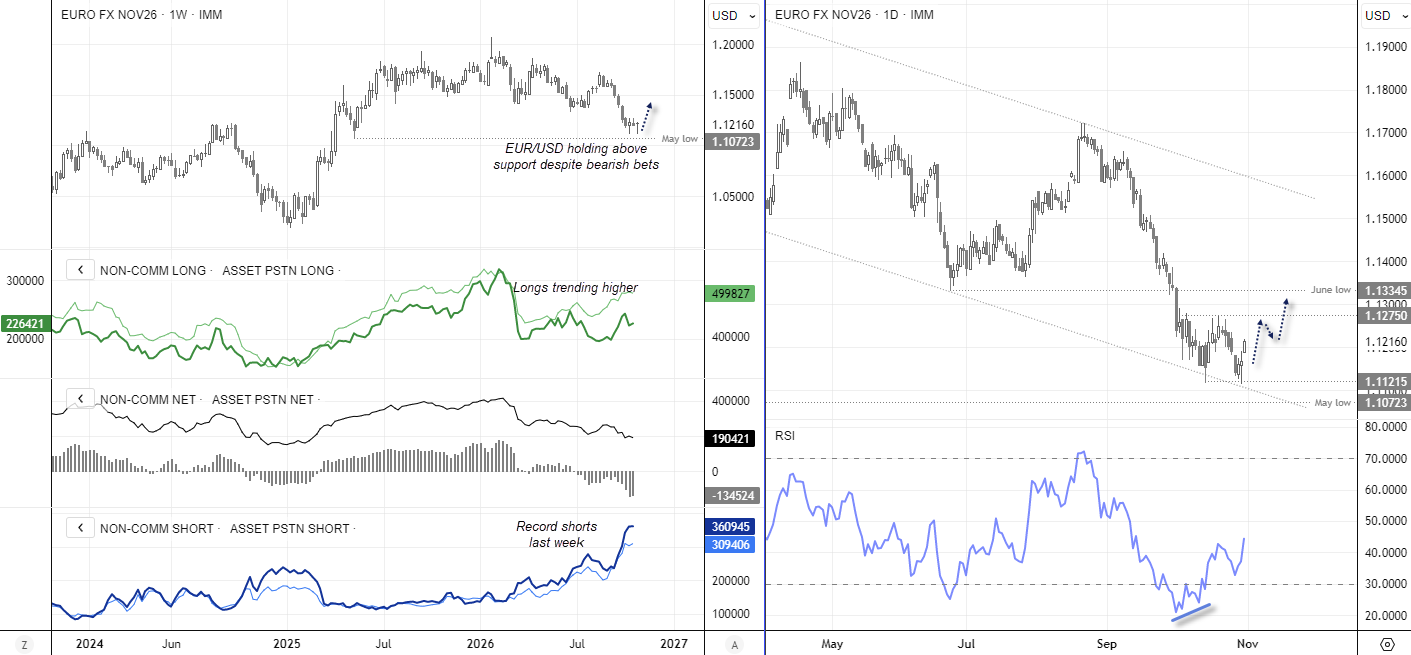
I sent a couple of reminder heading into the ECB meeting that euro futures were flashing a sentiment extreme.
The most recent Commitment of Traders (COT) report showed that large specs and asset managers had pushed net and gross-short exposure to a record high. Yet the inability for bears to drive EUR/USD beneath the May low to me suggested a crowded trade. And momentum has since turned higher. Given we’re now seeing the US dollar retreat on downwardly revised Fed expectations, the euro could have further to bounce in the coming weeks in my humble opinion.
Source: ICE, TradingView
Related tags:
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
EUR/USD forecast: All eyes on Warsh at Jackson Hole - Forex Friday
For much of this week, the EUR/USD has been edging lower with the US dollar regaining some ground after last week’s sell-off that was triggered, in part, by the bond market worries. Investors have been unwilling to bet further against the US dollar so far this week ahead of Kevin Warsh’s keynote speech at the Jackson Hole summit, due later today.

DAX and EUR/USD forecast: Lower energy prices, yields offer support
But the question, of course, is how much further oil prices and bond yields can fall. For now, the combination is supportive of risk assets and is helping to sustain a relatively benign decline in the dollar. The focus today will be on US core PCE inflation, due for release shortly, while Nvidia’s second-quarter earnings will provide another test for risk appetite after the US markets close – not just for US indices but for global tech-heavy indices given the influence Nvidia has over the global tech and AI names.
Oil, EUR/USD Forecast: Two trades to watch 2608
Oil falls further on diplomatic hopes for a Middle East resolution. EUR/USD consolidates ahead of U.S. inflation and Jackson Hole.
