Nasdaq and S&P 500 into the Fed
It’s a delicate balancing act for Kevin Warsh at today’s FOMC meeting where the bank is highly expected to raise rates for the first time in three years. The Nasdaq 100, meanwhile, hasn’t set a fresh high since the day before his first press conference.
Written by
James Stanley
Sr. Strategist
Nasdaq 100, S&P 500 Talking Points:
- The Fed is expected to hike today and then again in December, and with oil prices flaring there’s still concern around inflation even despite relatively calm US data over the past couple months.
- The other side of the argument and speaking to inflation concerns are Treasury yields, which have jumped to multi-decade highs. If the Fed doesn’t sound serious about addressing inflation then there’s even less reason for investors to hold duration and that lessened demand means lower prices and even higher yields.
In the post Financial Collapse backdrop the Federal Reserve has become more important to the performance of global markets as a constant driving of stimulus or liquidity or bond purchases have given investors even more reason to take on risk.
Forward guidance was central to this, and it was rolled out in 2011 at Jackson Hole as the thought was if the bank could communicate to markets that they had no intention of hiking rates and tightening policy, there would be even more motivation for investors to take on risk. This also meant that with yields staying low, due in part to a constant bid from the government, there was a level of incentive to hold bonds.
But that forward guidance concept really only works if the central bank is expecting to hold rates lower, right? Because if the bank is expecting to hike rates and they tell the market that hikes are coming in a consistent fashion, well, there’s even less reason to hold Treasuries and if there’s no government bid behind them because of QE, well, even less motivation.
For those that have learned markets or macro over the last ten or 15 years, this is really a degree of distortion that wasn’t present before and it really re-framed the Fed’s role in the marketplace, and it was previously unthinkable that the Federal Reserve would mettle in stocks. But, given that desperate backdrop in 2008 and 2009, the concept of the wealth effect took over and this is another push point for the Fed, which probably has more bearing on recent Fed decisions than it should.
The wealth effect dictates that if markets are rising, and consumers feel more flush with larger account balances, then they’re more likely to spend. This keeps consumer activity humming and it produces the most accommodative backdrop for Fed policy achieving its aim, particularly when they’re in a supportive mode. On the converse, if consumers are opening their 401k statements and they see losses of 10 or 20% in a year, well, there’s even more reason for them to save and less reason to spend freely. That leads to a higher marginal propensity to save and effectively lowers the velocity of capital in the economy.
So, there’s rationale that can be justified for the Fed to care about stock market gains and there’s also reason for them to try to prevent stock market losses, and this effectively became known as the Fed’s ‘third mandate.’
Of course, this has been denied multiple times. But that denial is difficult to justify when you look at something like 2024, when the Fed cut rates by 50 basis points – while employment data remained strong and inflation was far above the Fed’s own 2% target from pretty much every read.
That’s also probably why Treasury yields jumped so high after that rate decision – because markets thought the bank wasn’t serious about tackling inflation. And if that’s the case, and inflation is at or around 2.5% when the Fed is actively starting a rate cut cycle, why would an investor want to hold a 10-year note at 3.5%? It makes less sense as the rate cuts begin and that’s precisely what showed as 10-year yields flew up to 4.8% over the next few months.
There’s also the issue of supply because, after all, the Treasury market is like any other in which prices are dictated by supply and demand.
If the government is spending more money and they have to issue even more debt, well, absent any other driver for bringing more participants (or demand) into the marketplace, higher levels of supply will drive lower prices. And in bonds, lower prices mean higher yields and that’s precisely what the problem was a year earlier.
At that point, a trove of long-term US Treasury debt was coming due. Investors responded by selling Treasuries because, after all, if you’re holding long and you see an oncoming wave of supply, well, you practically have a guillotine hanging over your head. Why would you want to hold an asset long when a supply wave is about to push prices lower? The only rationale thing to do is to sell – and that’s exactly what was happening.
In six months the 10-year note went from 3.25% all the way up to 5%, largely pushed by supply fears. The benchmark hit that 5% rate briefly on the morning of October 23rd, 2023; but it was just after that when we saw the Treasury Secretary at the time, Janet Yellen, shift the Quarterly Refunding Announcement towards more short-term debt. This effectively answered the supply problem, but only in the near-term.
This was kicking the can down the road and now we’re at the point where the can is so large that kicking it even further presents more and more problems.
US 10-Year Yields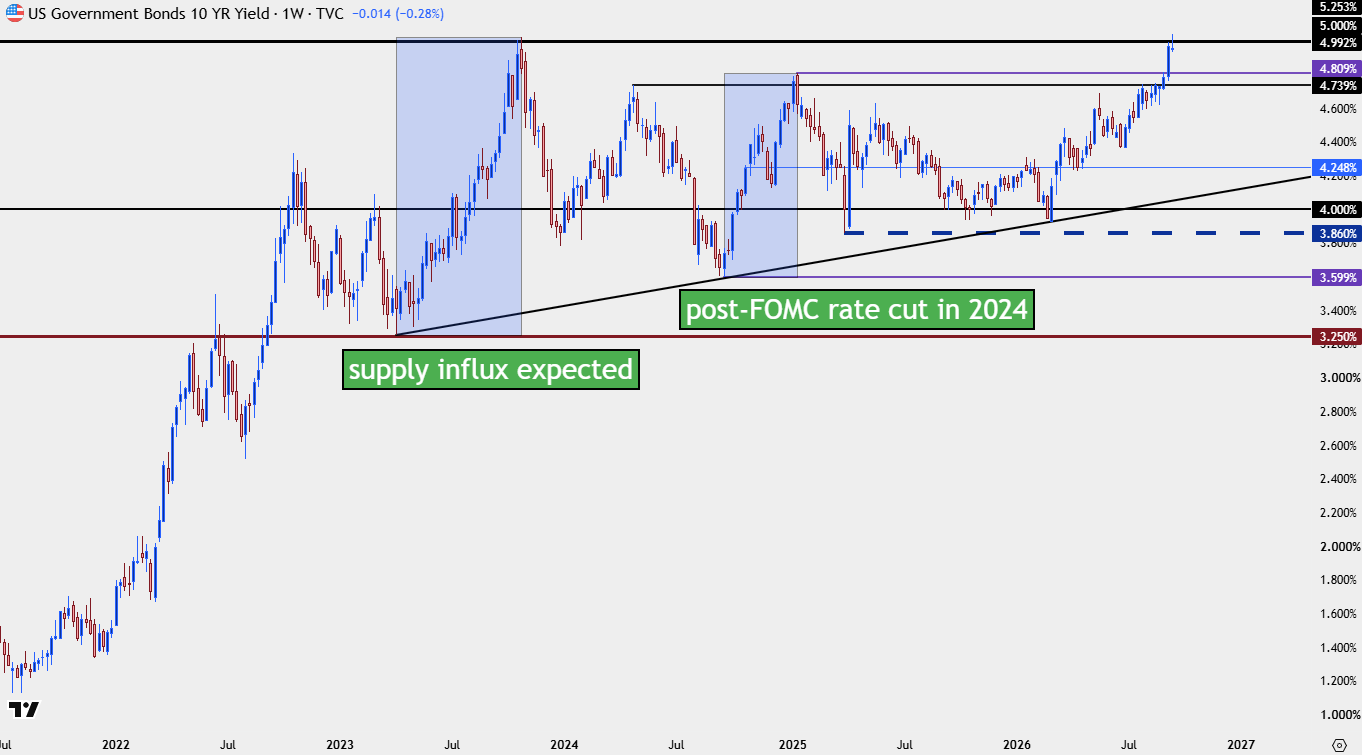
Chart prepared by James Stanley; data derived from Tradingview
Stocks
The reason this matters so much for equities is the defining factor for rallies since 2009 now carries more question. And while the Fed has cut rates multiple times even with inflation above their own target, we’re now at a spot with US Treasuries where they may not have that same flexibility.
Sounding weak on inflation can lead to selling of debt, which leads to higher yields and for a US government that’s heavily indebted, that’s a far more costly endeavor.
But also of concern is something that’s already started to happen – and that’s the tech heavy Nasdaq starting to lag behind the S&P 500. The AI trade that was very much the forerunner of equity rallies from the 2022 lows is now on its back foot and that’s been the case ever since Kevin Warsh’s first rate decision atop the Fed. Nasdaq 100 futures set a fresh ATH a day before that meeting, and hasn’t taken it out since even though the S&P 500 has.
So while there’s still been a show of bullish behavior in stocks particularly after the July FOMC rate decision, the high flying AI stocks that were leading the way for much of the past four years are now lagging behind.
Nasdaq 100 Weekly Chart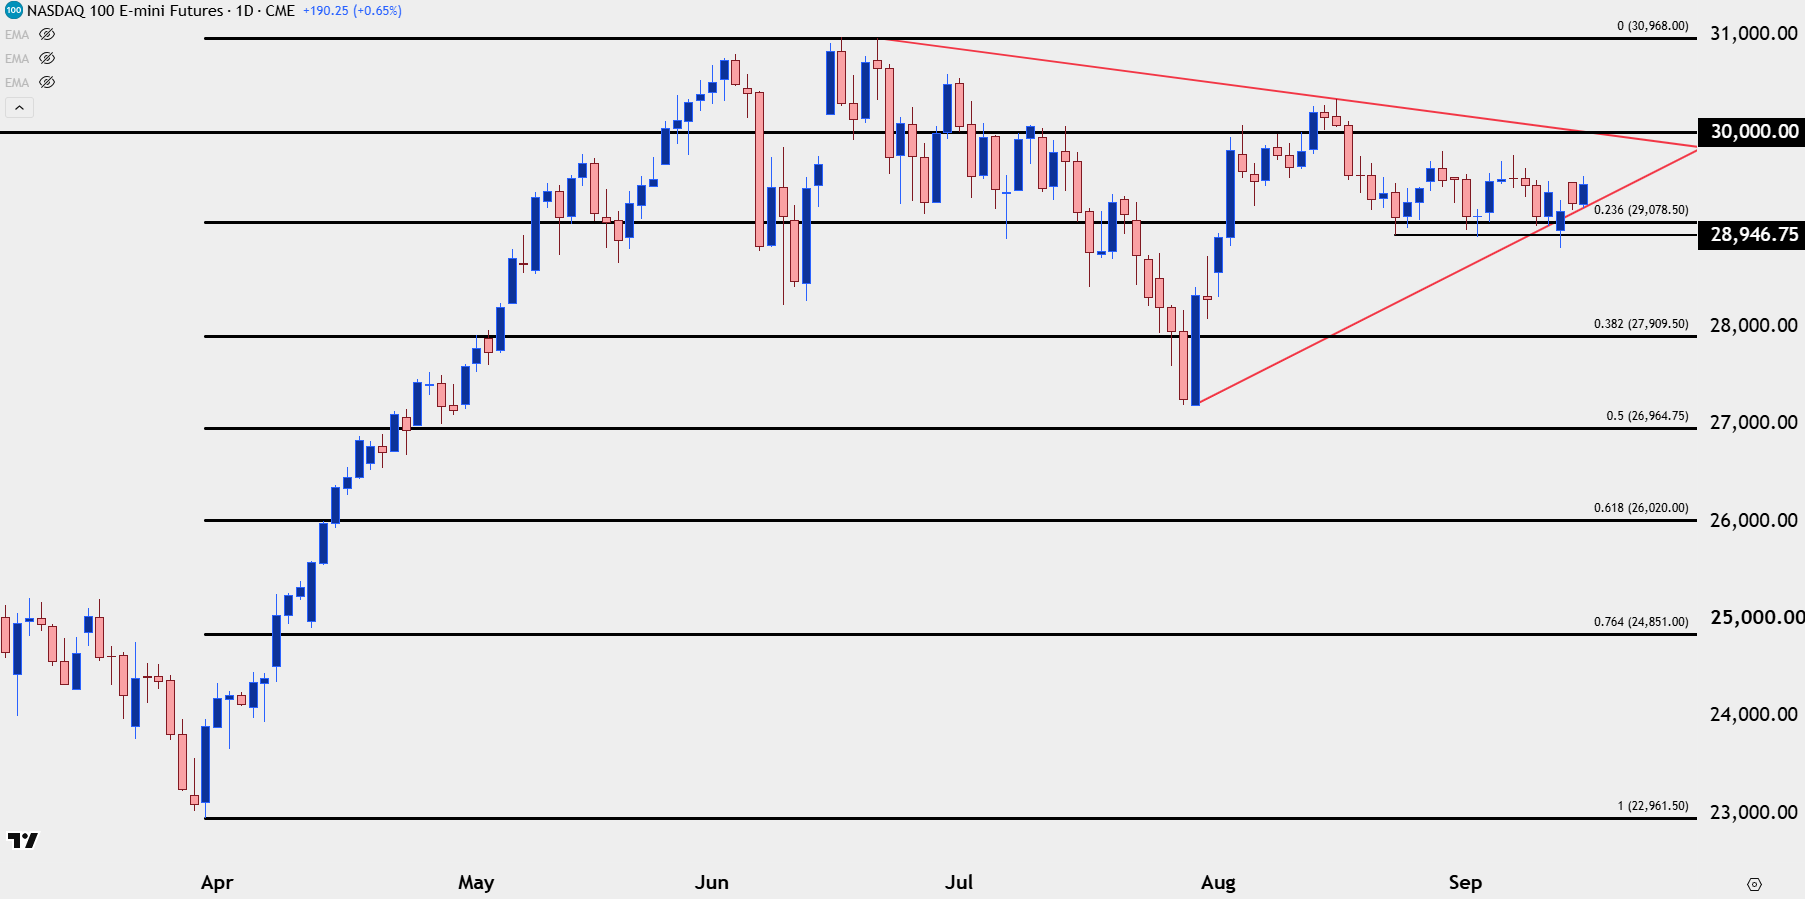
Chart prepared by James Stanley; data derived from Tradingview
S&P 500
There’s no reason for doom and gloom just yet because as you can see from the above chart, sellers haven’t exactly jumped on the opportunity to drive bearish breakouts. But given the context when earnings were strong especially for the market leader of NVDIA, and the fact that we are seeing this divergence between the indices, the change is notable.
In the S&P 500, however, there’s still bullish scope as price has so far held support at prior resistance, while forming a bull flag formation. As we go into today’s rate decision there’s still some hope for buyers given this backdrop.
S&P 500 Daily Chart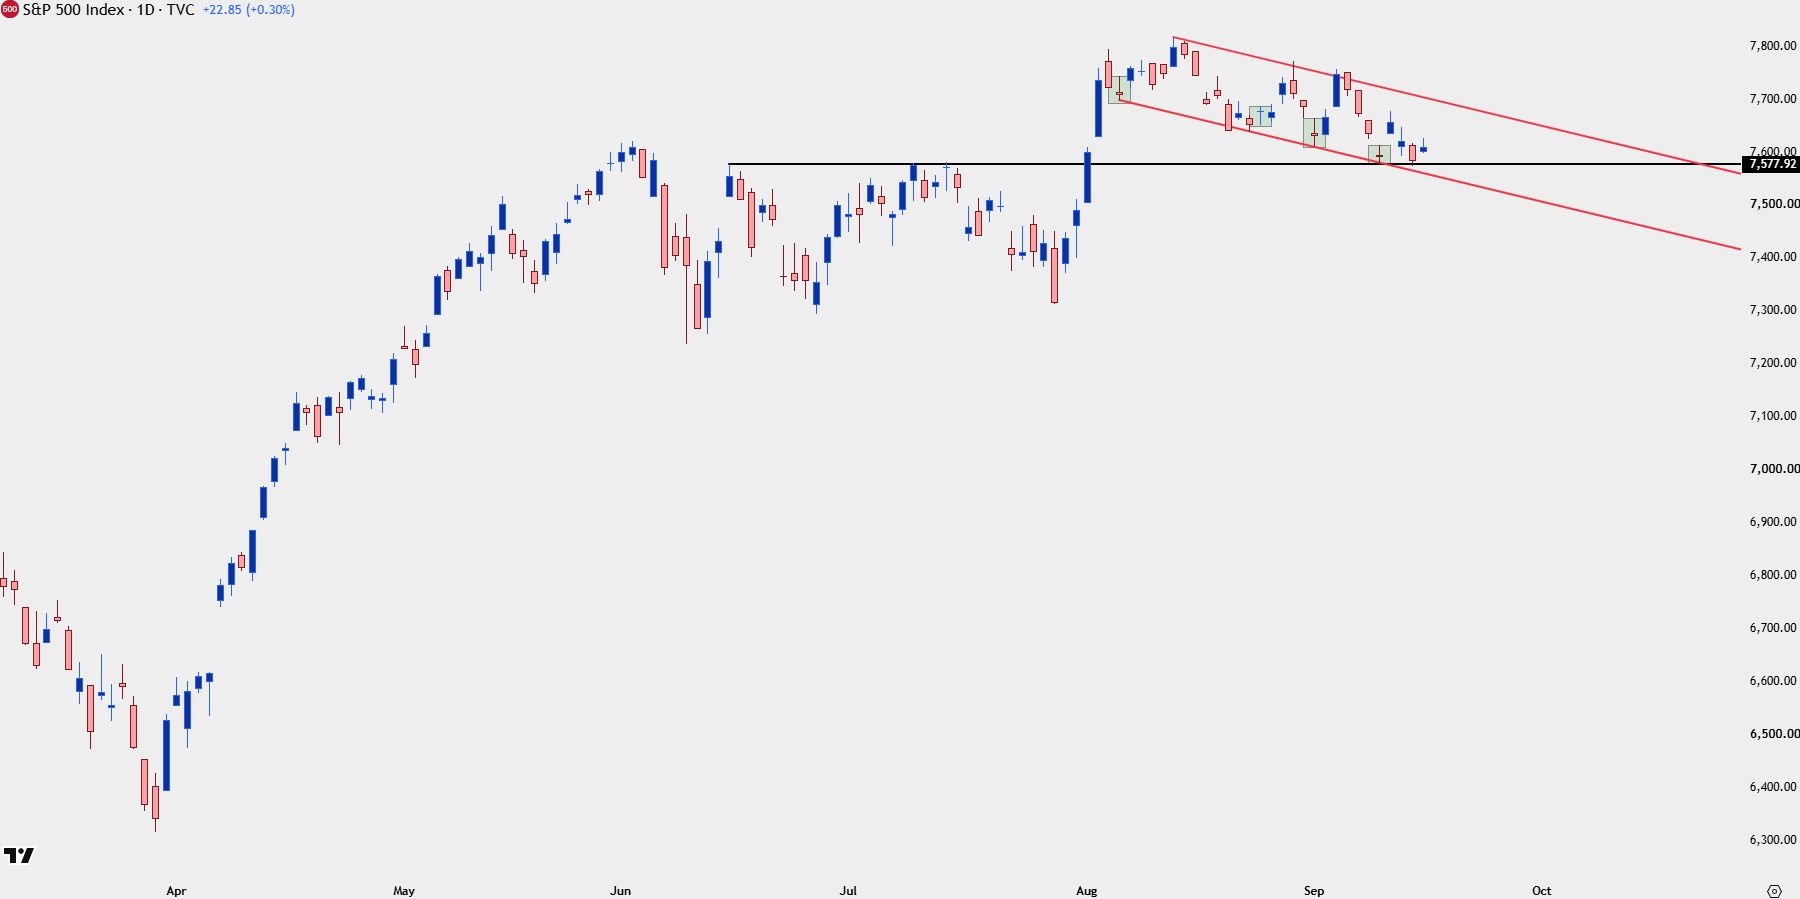
Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Market Analyst, Global Macro
Related tags:
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
Gold and S&P 500 analysis: What now after Warsh’s hawkish speech?
The dollar surged across the board after the Fed Chair Kevin Warsh surprised with a hawkish-leaning speech at the Jackson Hole summit. All the bearish dollar bets that had been accumulated since last Friday on the back of data weakness and bond market troubles had to be squared and that triggered a short squeeze rally for the dollar. Gold and silver dropped, as a result, as too did bitcoin, while US indices were giving back earlier gains.

Nasdaq 100 Forecast: NDX slips ahead of Fed Chair Warsh’s speech
U.S. stocks are edging lower on Friday, giving back some of yesterday's gains after Nvidia's strong outlook revived the tech trade. The focus has now shifted firmly to Fed Chair Kevin Warsh's Jackson Hole speech, with investors looking for more clarity on the outlook for interest rates.

Bitcoin Forecast: BTC/USD Back to $80K Ahead of Warsh’s Jackson Hole Speech
After surging over $15,000 in the past 10 days alone, there is risk of a near-term pullback if Warsh says anything remotely hawkish at Jackson Hole - what are the levels to watch from here?