
Tankan Backs BOJ Tightening, but Yen Rate Expectations Ease
Japan’s Tankan supports further BOJ tightening, although softer rate expectations could limit support for the Japanese yen.
Written by
Matt Simpson
Market Analyst
Japan’s latest Tankan kept the case for further BOJ tightening intact, with manufacturing sentiment improving, labour shortages persisting and firms expecting further price increases. Yet softer forward conditions and easing JPY OIS rates suggest traders see little urgency for the BOJ to accelerate its tightening cycle.
Japan Tankan Supports BOJ Tightening as Yen Rate Pricing Softens
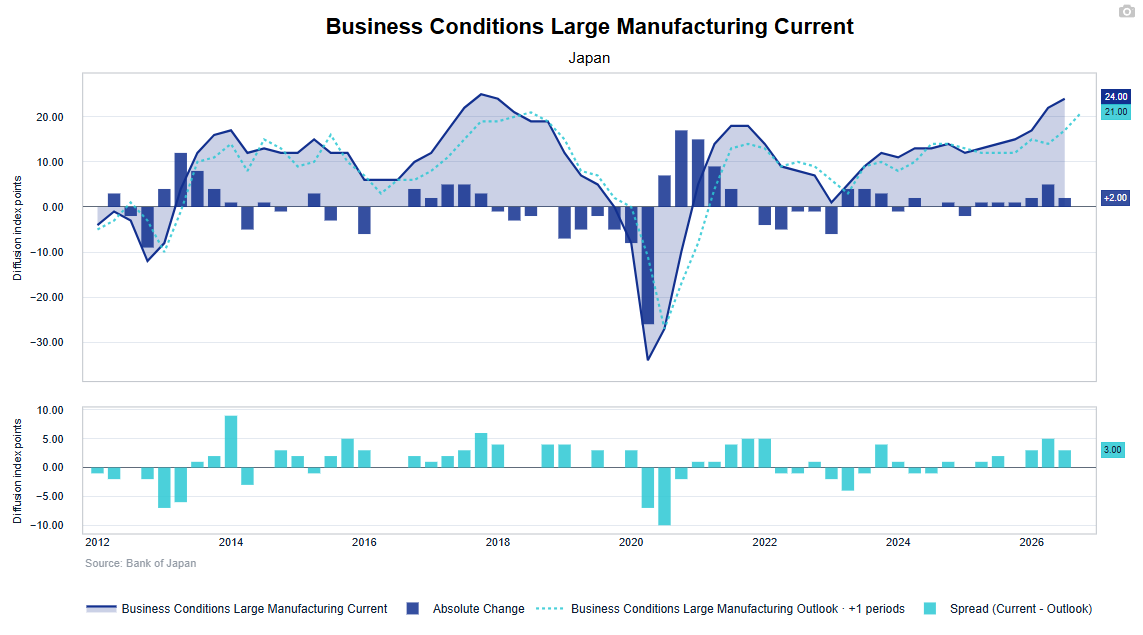
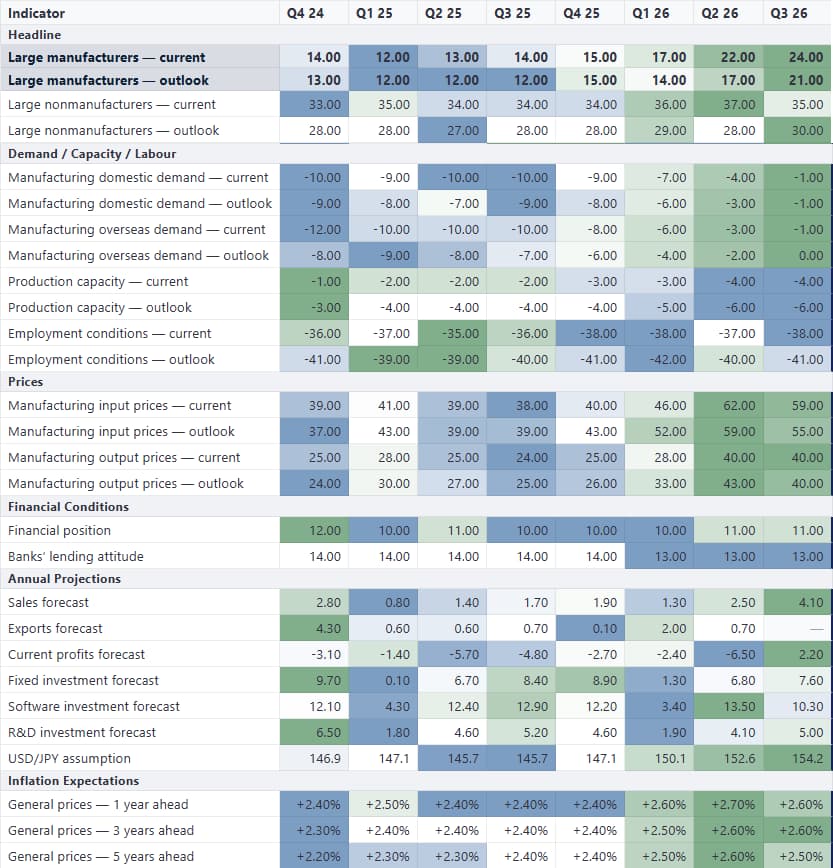
Japan’s latest Tankan report painted a reasonably constructive picture of the economy, even if the strength was far from uniform. Sentiment among large manufacturers improved to 24 from 22, its strongest reading in years, while small manufacturers strengthened to 14 from 9. The services side was less convincing, with large non-manufacturers slipping to 35 from 37 and small non-manufacturers holding at 15.
Manufacturers also expect conditions to soften over the coming quarter, with the large-manufacturing outlook at 21. Yet other parts of the survey remain relatively firm, with employment conditions staying deeply negative at -38 and signalling persistent labour shortages.
Firms Expect Further Output Price Increases
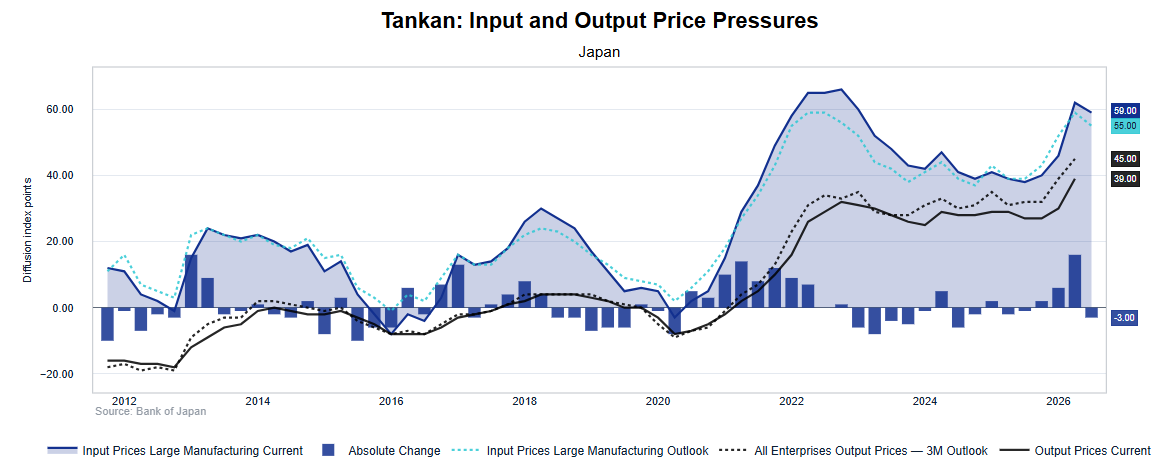
Price pressures also remain elevated, even if manufacturers expect some moderation in their input costs. The large-manufacturer input-price index eased to 59, with firms expecting it to fall to 55 next quarter. Yet the broader output-price index remains firm, with businesses expecting selling-price pressures to rise further.
That is an important detail for the BOJ. Easing upstream costs would be welcome, but rising output-price intentions suggest firms still expect to pass higher costs through to customers.
Inflation Expectations Keep BOJ Tightening in Play
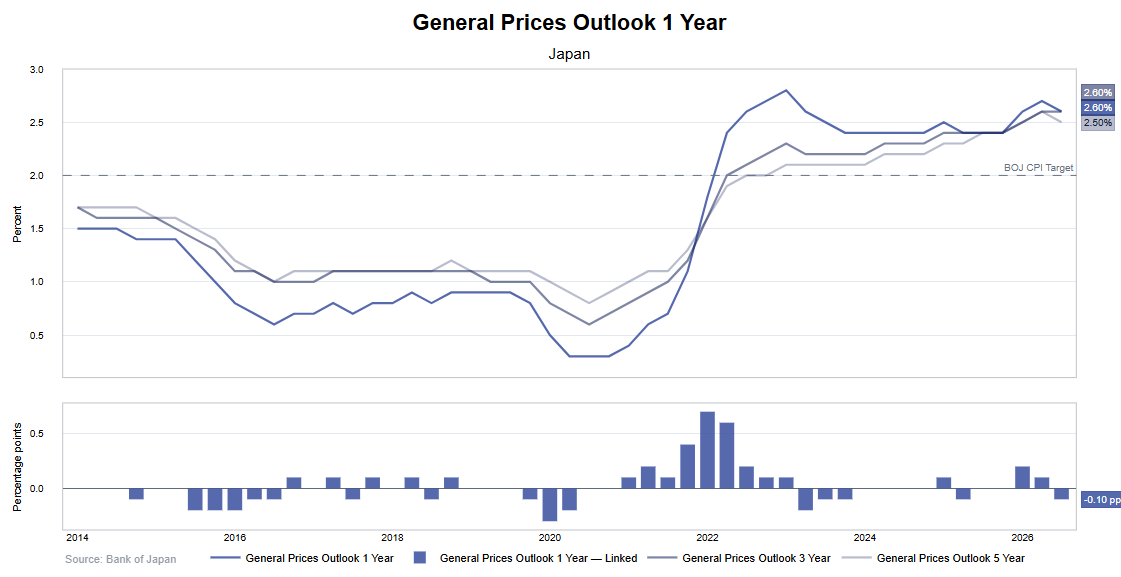
Inflation expectations also remain above the BOJ’s 2% target across the one-, three- and five-year horizons, with the one-year outlook easing only slightly to 2.6%.
Combined with persistent labour shortages and stronger output-price expectations, that should keep further policy normalisation on the table. But with inflation expectations showing little renewed acceleration and manufacturers expecting some moderation in conditions, the Tankan does not necessarily argue for a faster pace of tightening.
Softer BOJ Rate Pricing Could Limit Yen Support
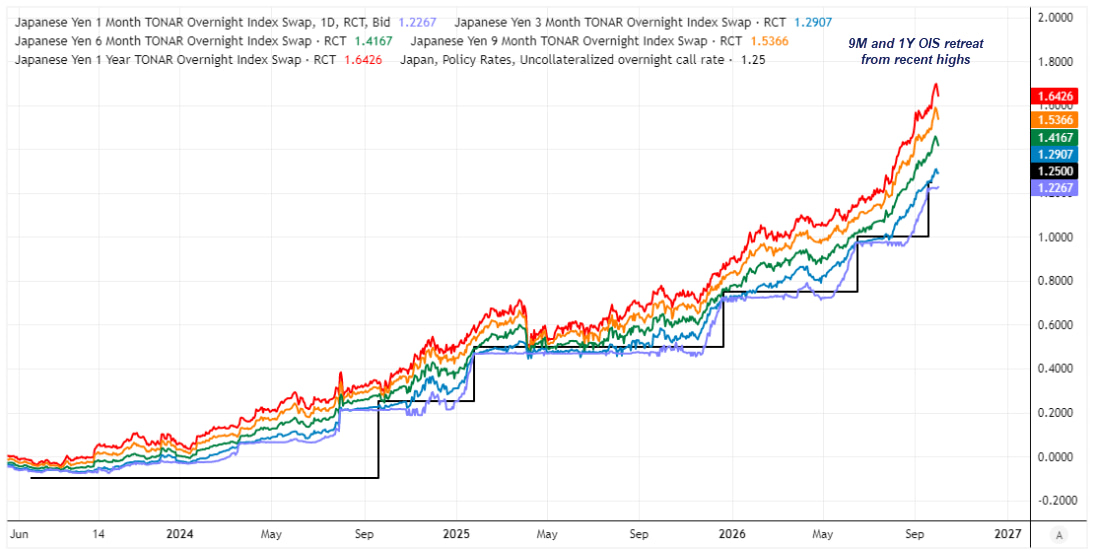
Despite the Tankan keeping further BOJ tightening in play, money markets have become less aggressive about the path ahead. JPY OIS rates have eased from recent highs, particularly across the six-month to one-year tenors, suggesting traders are trimming expectations for the pace of future hikes rather than abandoning the prospect of further tightening altogether.
That matters for the yen. Further BOJ tightening should remain supportive at the margin, but a softer implied rate path reduces one of the more obvious sources of support for JPY. A renewed rise in OIS pricing would strengthen the policy case for the yen, while further declines could leave it vulnerable even if the BOJ maintains a tightening bias.
The dashboard below summarises the main Tankan trends across business conditions, demand, labour, pricing, financial conditions and inflation expectations. It highlights a firmer manufacturing backdrop alongside persistent labour shortages, elevated price pressures and inflation expectations that remain above the BOJ’s 2% target.
Related tags:
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles

EUR/USD forecast: All eyes on Warsh at Jackson Hole - Forex Friday
For much of this week, the EUR/USD has been edging lower with the US dollar regaining some ground after last week’s sell-off that was triggered, in part, by the bond market worries. Investors have been unwilling to bet further against the US dollar so far this week ahead of Kevin Warsh’s keynote speech at the Jackson Hole summit, due later today.

DAX and EUR/USD forecast: Lower energy prices, yields offer support
But the question, of course, is how much further oil prices and bond yields can fall. For now, the combination is supportive of risk assets and is helping to sustain a relatively benign decline in the dollar. The focus today will be on US core PCE inflation, due for release shortly, while Nvidia’s second-quarter earnings will provide another test for risk appetite after the US markets close – not just for US indices but for global tech-heavy indices given the influence Nvidia has over the global tech and AI names.
AUD/USD Shorts Bear the Brunt of Hot CPI, Renewed RBA Hike Bets
Hot Australian CPI revives RBA hike bets, lifts bond yields and adds fresh pressure to crowded AUD/USD short positions.