DAX forecast: AI optimism offers relief ahead of central bank meetings
The DAX is finding some relief from the recent improvement in risk appetite, with investors becoming less concerned about the sustainability of the AI trade
Written by
Fawad Razaqzada
Market Analyst
The DAX is finding some relief from the recent improvement in risk appetite, with investors becoming less concerned about the sustainability of the AI trade. Strong earnings from SK Hynix have helped revive demand for AI-related shares, while the market awaits results from Alphabet and Microsoft later today. That has provided some support for European equities, although the picture remains uneven. Mixed bank reports have helped some indices while weighing on others such as Spain’s IBEX which was among the biggest laggards after Santander’s results. The German DAX, however, has been more resilient and was trading modestly higher at the time of writing.
The key question now is whether this recovery in risk appetite can extend, particularly with the Federal Reserve and ECB decisions taking centre stage over the next two days.
DAX benefits from improving AI sentiment
The recent improvement in AI-related sentiment has helped to lift the DAX given the index’s exposure to technology-related companies. Concerns about an AI-driven correction had contributed to the recent weakness across global equities, so any evidence that the AI investment cycle remains intact is supportive for certain sections of European markets.
SK Hynix’s blowout earnings provided just that. The strong results have helped lift shares linked to the AI buildout and, at least for now, eased concerns that spending on AI infrastructure is becoming excessive.
There are also further developments underpinning the theme. Anthropic is reportedly preparing for a potentially record-setting IPO and has selected JPMorgan to lead its US retail offering, while OpenAI is reportedly planning to use Google chips as part of its infrastructure expansion.
Mixed bank results
We have also had some important corporate updates from key European companies, including lenders today. UBS fell after a set of results that showed stronger wealth-management revenue and client inflows but weaker net income and investment-banking profits. Santander has come under heavy pressure, down 4%, despite broadly in-line results and confidence in meeting its 2026 targets.
By contrast, Deutsche Bank and Standard Chartered have provided stronger updates, and their shares were up more than 4% each, while BNP Paribas benefited from better-than-expected equity trading revenue and announced a €1.3bn share buyback.
For the DAX, the important point is that the broader risk backdrop has improved, even if corporate earnings remain far from uniformly positive.
Fed and ECB could determine the next move
The bigger risk for the DAX forecast may come from central banks rather than earnings.
The Fed is expected to leave rates unchanged today, but the accompanying communication could prove more important than the decision itself. Markets are currently pricing a roughly 84% probability of a December hike, meaning investors will be particularly sensitive to the vote split and Kevin Warsh’s comments on inflation.
The ECB faces a similarly awkward balancing act tomorrow. Rates are widely expected to remain unchanged after two increases this year, but the market will be looking for clues about whether another hike could arrive in December. Higher energy prices linked to the Iran conflict have complicated the inflation outlook, while rising French borrowing costs and political uncertainty add another layer of risk.
DAX forecast: technical analysis and levels to watch
From a technical analysis perspective, the DAX’s ability to stabilise despite the weakness elsewhere in Europe is encouraging.
The fact that it has broken above its 21-day exponential moving average is an additional sign that the buyers are returning.
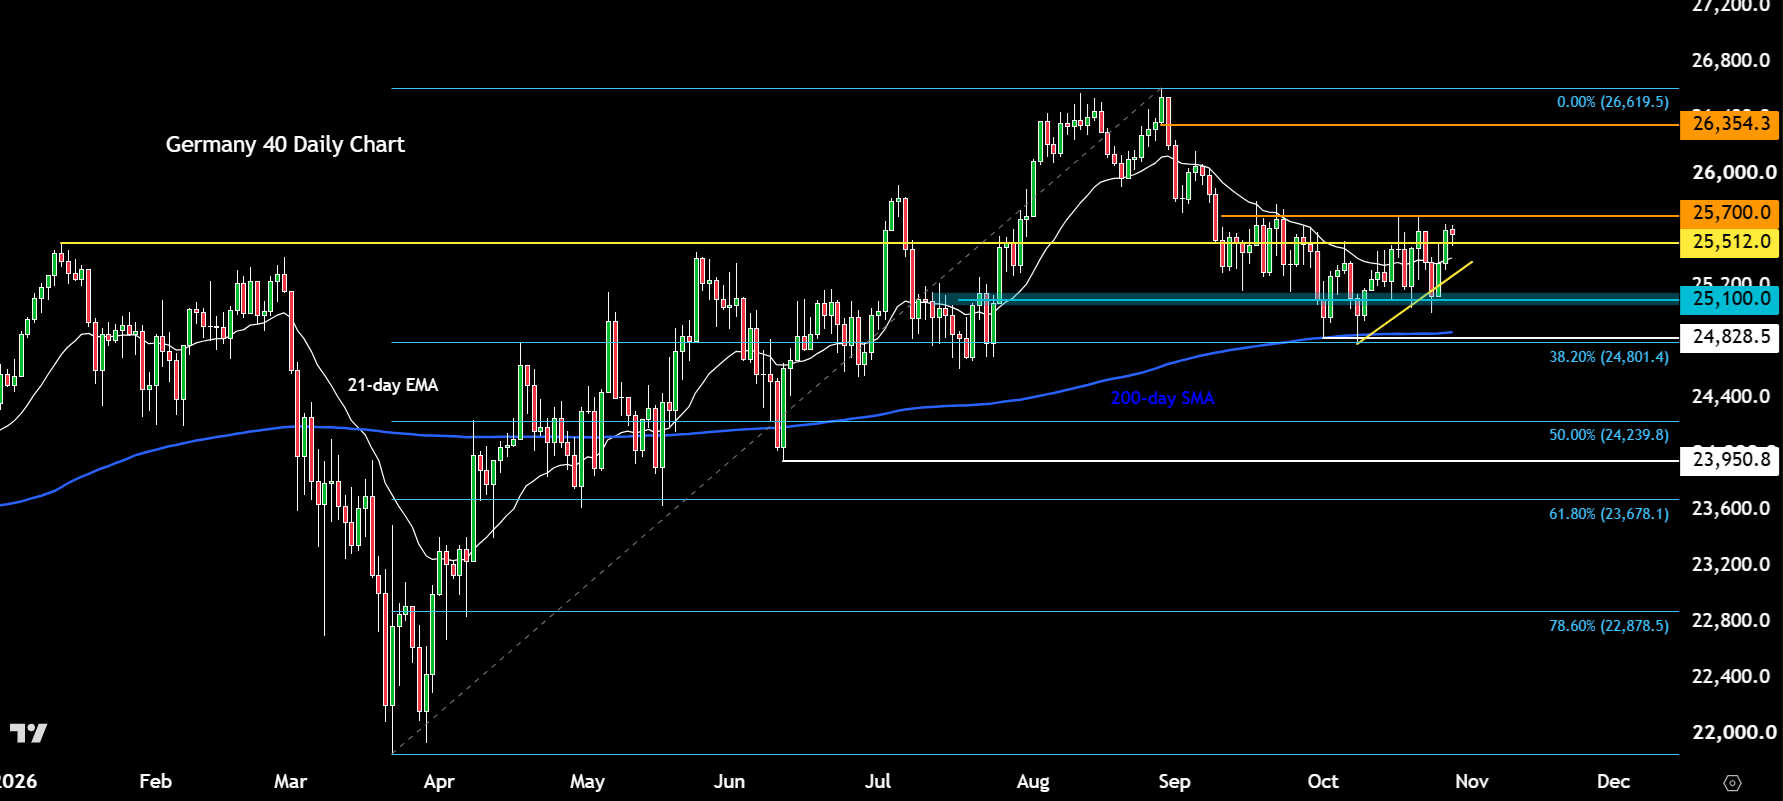
Recently it has also climbed back above 25,500, a prior support and resistance level as well as an old record high from earlier in the year.
If the DAX can now reclaim 25,700 resistance then the bulls will have gained the upper hand again. In that case, a run towards the 26,000 level could be on the cards next, with 26,355 being the next objective ahead of this year’s all time high at 26,620.
Support is now seen at 25,500 initially, followed by 25,400. Long term support is at 24,800-900 area where the 200 day average also comes into play. This area has held after the recent sell off.
The index needs to build on the recent rebound and, importantly, hold above its recent lows. A stronger performance from US technology shares following the Alphabet and Microsoft earnings could provide the catalyst for that move.
However, the Fed and ECB decisions create obvious event risk. A more hawkish-than-expected Fed could push yields higher and put renewed pressure on equities, while any deterioration in the Iran situation would provide another reason for investors to reduce risk.
For now, therefore, the bias is cautiously constructive on the DAX forecast rather than outright bullish. Improving AI sentiment is giving the DAX some breathing room, but the market still has to navigate central-bank risk, geopolitical uncertainty and an increasingly mixed earnings season.
Related tags:
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
Gold and S&P 500 analysis: What now after Warsh’s hawkish speech?
The dollar surged across the board after the Fed Chair Kevin Warsh surprised with a hawkish-leaning speech at the Jackson Hole summit. All the bearish dollar bets that had been accumulated since last Friday on the back of data weakness and bond market troubles had to be squared and that triggered a short squeeze rally for the dollar. Gold and silver dropped, as a result, as too did bitcoin, while US indices were giving back earlier gains.
EUR/USD forecast: All eyes on Warsh at Jackson Hole - Forex Friday
For much of this week, the EUR/USD has been edging lower with the US dollar regaining some ground after last week’s sell-off that was triggered, in part, by the bond market worries. Investors have been unwilling to bet further against the US dollar so far this week ahead of Kevin Warsh’s keynote speech at the Jackson Hole summit, due later today.
Nasdaq 100 forecast: Tech stocks shine as Nvidia results underpin AI trade
Much of this week’s attention has been on Nvidia’s earnings, and the chipmaker delivered the sort of numbers of investors had been hoping for. US index futures initially wobbled before moving higher overnight, with the results providing a fresh lift to the AI trade