EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
Written by
Michael Boutros
Sr. Technical Strategist
Key points for the Euro 2026 Q2 outlook
- The Fed delivered its first rate hike since 2023 in September, with updated projections reinforcing expectations for additional tightening into year-end.
- The ECB has raised rates twice this year as policymakers confront persistent inflation pressures alongside increasing risks to the growth outlook.
- The policy backdrop continues to favor the U.S. dollar, although the relative pace of Fed and ECB tightening will be critical for EUR/USD through Q4.
- EUR/USD has reversed more than 3% from the August high, bringing the pair back to the same major support region that underpinned the Q3 recovery.
- Monthly momentum is deteriorating into the quarterly close, raising the stakes for the October open as Euro tests a pivotal technical threshold.
EUR/USD enters the fourth quarter at a critical juncture after the summer recovery gave way to renewed selling into the close of September. The fundamental backdrop remains challenging as both the Fed and ECB confront persistent inflation, although differences in growth, policy expectations, and the pace of additional tightening could prove increasingly important into year-end. With Euro once again testing a major technical threshold, the coming quarter will hinge on whether the recent decline can stabilize or develops into a broader correction.
Fed Keeps Price Stability Front and Center
In September, the Federal Reserve raised its target range by 25 basis points to 3.75%–4.00%, marking the first rate increase since 2023. The decision was unanimous, with the accompanying policy statement highlighting solid economic activity, resilient domestic spending, strong productivity growth, robust capital investment, and a steady labor market. During the subsequent press conference, Fed Chair Kevin Warsh reaffirmed the central bank’s commitment to restoring price stability as inflation remains above target for a fifth consecutive year.
Warsh pointed to three developments since the previous meeting: evidence that the economy had strengthened, little evidence that underlying inflation trends had improved, and a changed geopolitical backdrop. He stressed that the Fed looks at trends across a range of information, not just an individual data release, and declined to signal a preset sequence of moves. Warsh characterized the rate hike as removing “a dose of accommodation,” while noting that he was hard-pressed to describe broad financial conditions as restrictive.
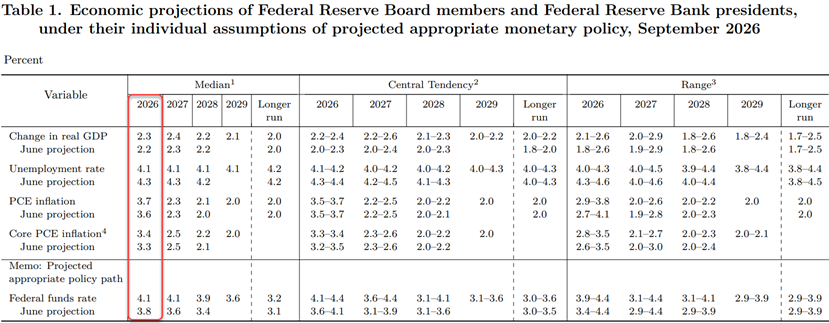
FOMC Summary of Economic Projections
Source: FOMC
The Fed Chair’s remarks reinforced expectations for a more aggressive tightening cycle, with the updated Summary of Economic Projections (SEP) pointing to a resilient labor market, stronger economic growth, and more persistent inflation through the end of 2026. The latest projections also show a median federal funds rate of 4.1% through year-end 2027, before gradually declining in 2028 and 2029. Taken together, the forecasts reinforce a higher-for-longer policy outlook, with additional tightening still projected before year-end.
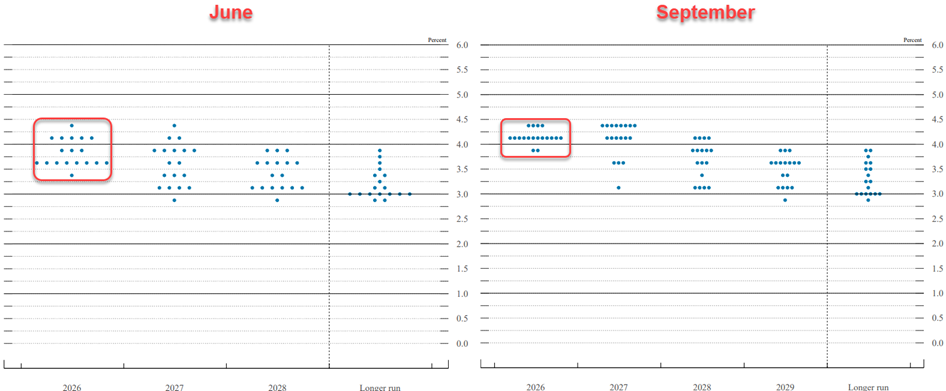
FOMC Interest Rate Dot Plot
Source: FOMC
The September dot plot shifted markedly higher from June, with twelve participants now see the rate at 4.125% by year-end, while four project 4.375% and two see it holding at 3.875%. The shift signals a stronger bias toward further tightening, with most policymakers now projecting at least one more quarter-point increase before year-end.
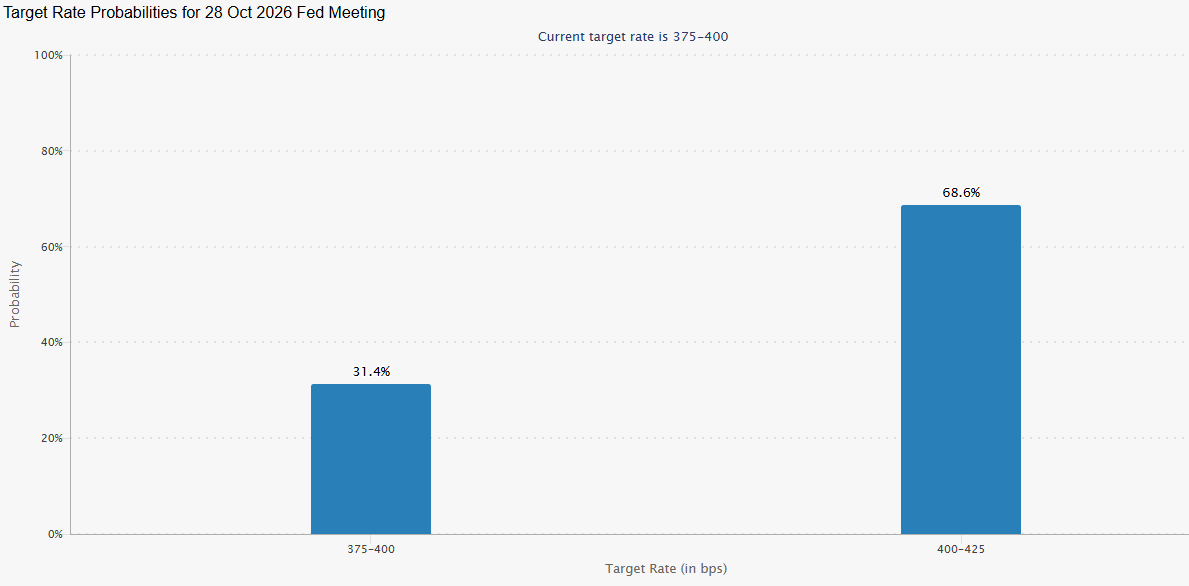
Fed Fund Futures- FedWatch Tool
Source: CME
As a result, markets are now pricing a 68% probability of another 25-basis-point Fed hike in October, with the odds of a third increase by December approaching 58%. The increasingly hawkish Fed outlook has strengthened the policy backdrop for the U.S. dollar, creating a significant headwind for EUR/USD and making it more difficult for the pair to stabilize before mounting a meaningful recovery into year-end. With additional tightening still on the table, the evolution of inflation and the relative Fed-ECB policy path will be critical in determining whether the dollar can extend its recent advance.
ECB Policy Caught Between Inflation and Growth
The European Central Bank has delivered two 25-basis-point hikes so far this year: in June, then again in September, lifting the deposit rate to 2.50%. The ECB has adopted a more restrictive policy stance as the Middle East conflict and associated energy shock intensify inflation risks across the Eurozone. The Governing Council expects inflation to remain above target for an extended period, with President Christine Lagarde emphasizing that risks remain tilted to the upside for prices and to the downside for growth.
ECB Staff Inflation Projections
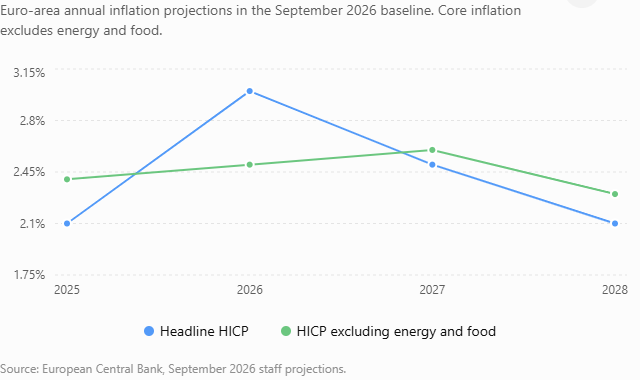
Policymakers are closely monitoring the magnitude and duration of the energy shock, particularly the extent to which higher costs feed through to broader prices and wages. The baseline shows headline inflation peaking this year, while core inflation edges higher into 2027 before easing.
ECB Staff GDP Growth Projections
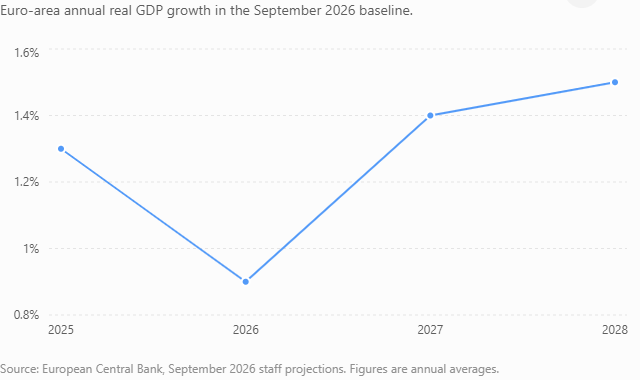
For now, the Eurozone economy has remained resilient, supported by broad-based second-quarter growth, improving consumer confidence, and public spending. At the same time, headline inflation accelerated to 3.3% in August from 2.9% in July, reinforcing concerns over persistent price pressures. While the ECB has not pre-committed to another increase, markets are increasingly positioned for further tightening, with traders pricing roughly a 93% probability of a December hike that would lift the deposit rate to 2.75%. A deterioration in growth or moderation in energy-driven inflation, however, could challenge those expectations
The policy backdrop continues to favor the U.S. dollar, with the federal funds target range at 3.75%–4.00% compared with an ECB deposit rate of 2.50%. But for EUR/USD, the current rate differential may be less important than how that gap evolves into year-end. The ECB’s increasingly hawkish response to persistent inflation provides some fundamental support for the euro, while the Fed’s own tightening bias continues to underpin the greenback. With both central banks leaving the door open to further action, the relative pace of tightening—and the incoming inflation and growth data driving those expectations—will likely remain a key catalyst for EUR/USD through the fourth quarter. That said, the technical backdrop puts EUR/USD back at a major inflection zone into the close September, and the focus is on whether the bulls can stabilize this recent decline heading into the close of the year.
EUR/USD Technical Outlook: Q4 Outlook Hinges on Make-or-Break Support
Euro Price Chart – EUR/USD Monthly
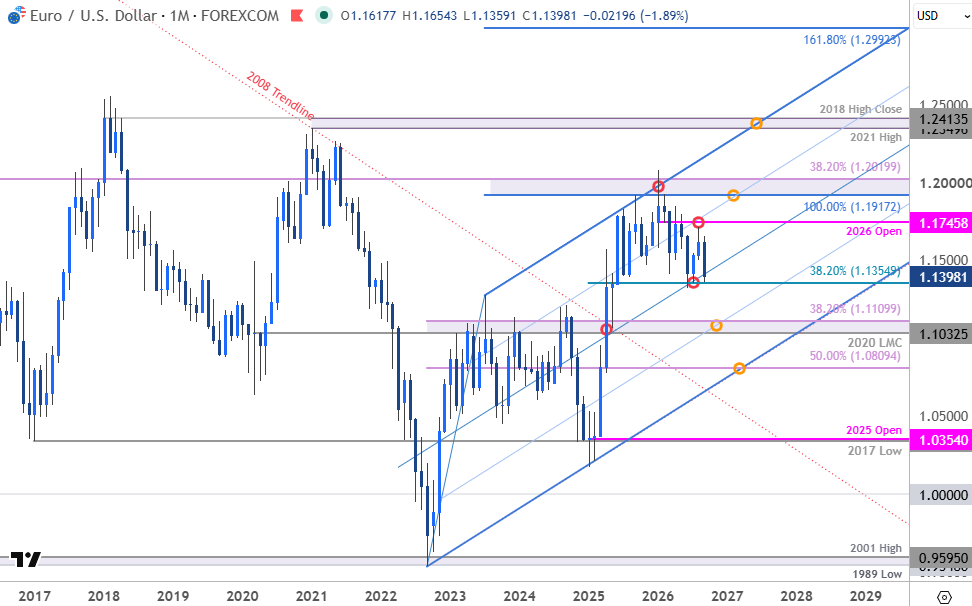
Chart Prepared by Michael Boutros, Sr. Technical Strategist; EUR/USD on TradingView
In our 2026 EUR/USD Q3 Outlook, we noted that Euro was testing critical support into the close of June at 1.1355/94- a region defined by the 38.2% retracement of the 2025 advance, the 2025 April high close, and the July low. We highlighted, “The risk / focus is on possible inflection off this zone into the start of Q3. From a trading standpoint, a good zone to reduce portions of short exposure / lower protective stops..” EUR/USD registered a close low at 1.1369 the following month before rebounding sharply with the rally extending more than 3.4% off the yearly low. The bulls exhausted just head of the yearly open in mid-August before plunging more than 3% with price once again testing key support into the close of the quarter. The focus remains on a possible inflection from this threshold heading into the October open.
EUR/USD Monthly RSI (14)
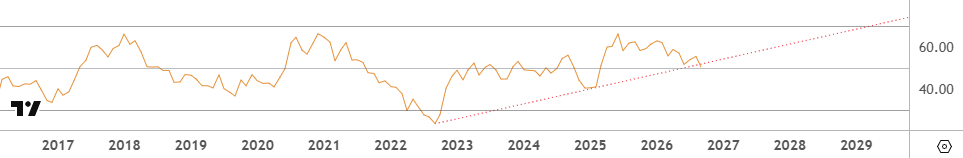
Note that monthly momentum has now fallen to the lowest levels since March of 2025 with RSI attempting to break below the 50-level. A monthly close below 1.1355 alongside a momentum break below 50 would be needed to signal that a deeper correction may be unfolding within the broader uptrend from 2022.
Euro Price Chart – EUR/USD Weekly
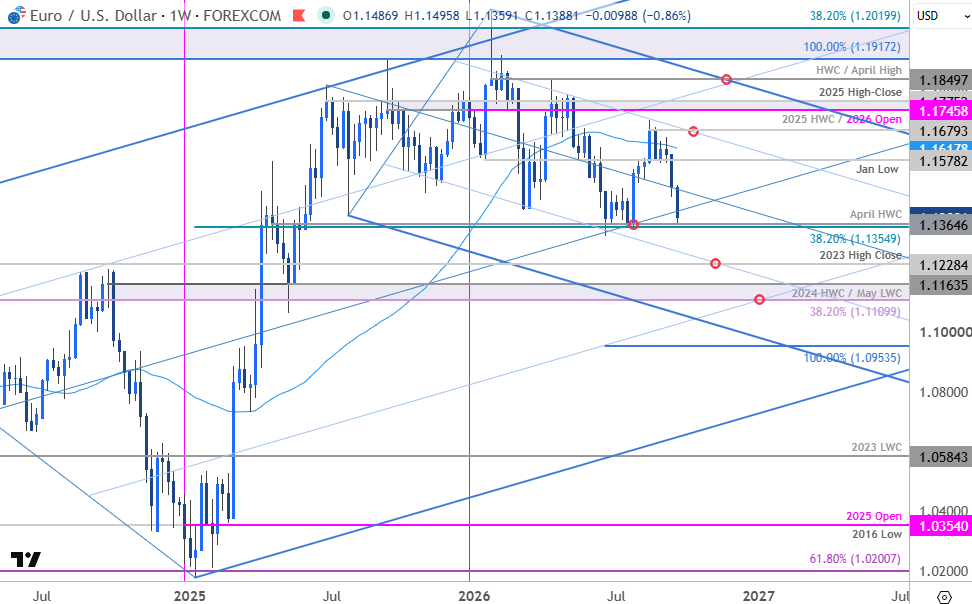
Chart Prepared by Michael Boutros, Sr. Technical Strategist; EUR/USD on TradingView
A closer look at the weekly chart shows EUR/USD continuing to trade within the confines of a descending pitchfork extending off the yearly high. A reversal off the 75% parallel in August has broken the median-line with Euro trading just above support into the close of September at the 38.2% retracement and the April high week close (HWC) at 0.. A break / weekly close below this threshold exposes subsequent support objectives at the 2023 high close at 1.1228 and 1.1110/64- a region defined by the 38.2% retracement of the broader 2022 advance, the 2024 high-week close (HWC), and the 2025 May low-week close (LWC). Note that the 25% parallel of the broader uptrend converges on this threshold into the close of the year. Look for a larger reaction there IF reached. The next major technical consideration rests with the 100% extension of the January decline neat 1.0954.
Resistance is now eyed back at the January swing low at 1.1578 and is backed by the August high-week close at 1.1679. Note that the 75% parallel of the yearly pitchfork converges on this level in mid-October and a breach / weekly close above would be needed to suggest a more significant low is in place, and a larger recovery is underway. Subsequent resistance objectives are eyed at the yearly open, the 2025 HWC and the 2025 high close at 1.1745/75, and the 2025 high close at 1.1850. Strength surpassing this level would invalidate the yearly downtrend and mark potential resumption of the 2025 uptrend towards 1.1917 and 1.2020.
Bottom Line: EUR/USD is trading just above pivotal support into the close of Q3, and the focus is on possible inflection off this zone for guidance into year end. A good zone to reduce portions of short exposure / lower protective stops. From a trading standpoint, rallies would need to be limited to 1.1578 IF price is heading for a break lower on this stretch with a close below 1.1355 needed to fuel the next major leg of the decline.
--- Written by Michael Boutros, Senior Market Analyst
Follow Michael on X @MBForex
Latest market news

Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles

EUR/USD forecast: All eyes on Warsh at Jackson Hole - Forex Friday
For much of this week, the EUR/USD has been edging lower with the US dollar regaining some ground after last week’s sell-off that was triggered, in part, by the bond market worries. Investors have been unwilling to bet further against the US dollar so far this week ahead of Kevin Warsh’s keynote speech at the Jackson Hole summit, due later today.

Bitcoin Forecast: BTC/USD Back to $80K Ahead of Warsh’s Jackson Hole Speech
After surging over $15,000 in the past 10 days alone, there is risk of a near-term pullback if Warsh says anything remotely hawkish at Jackson Hole - what are the levels to watch from here?

DAX and EUR/USD forecast: Lower energy prices, yields offer support
But the question, of course, is how much further oil prices and bond yields can fall. For now, the combination is supportive of risk assets and is helping to sustain a relatively benign decline in the dollar. The focus today will be on US core PCE inflation, due for release shortly, while Nvidia’s second-quarter earnings will provide another test for risk appetite after the US markets close – not just for US indices but for global tech-heavy indices given the influence Nvidia has over the global tech and AI names.