FOMC Recap: Fed Holds, but Warsh Falls Short of a Full Hawkish Hold
FOMC Chairman Warsh fell short of delivering a clear hint that the Fed would raise rates again in December, resulting in a modestly less-hawkish-than-anticipated short-term interpretation of the event - what does that mean for the US dollar?
Written by
Matt Weller
Head of Market Research
Federal Reserve, FOMC Key Points
- The Federal Reserve’s FOMC held interest rates in the 3.75-4.00% range, as expected, in a 10-2 vote.
- Warsh fell short of delivering a clear hint that the Fed would raise rates again in December, resulting in a modestly less-hawkish-than-anticipated short-term interpretation of the event.
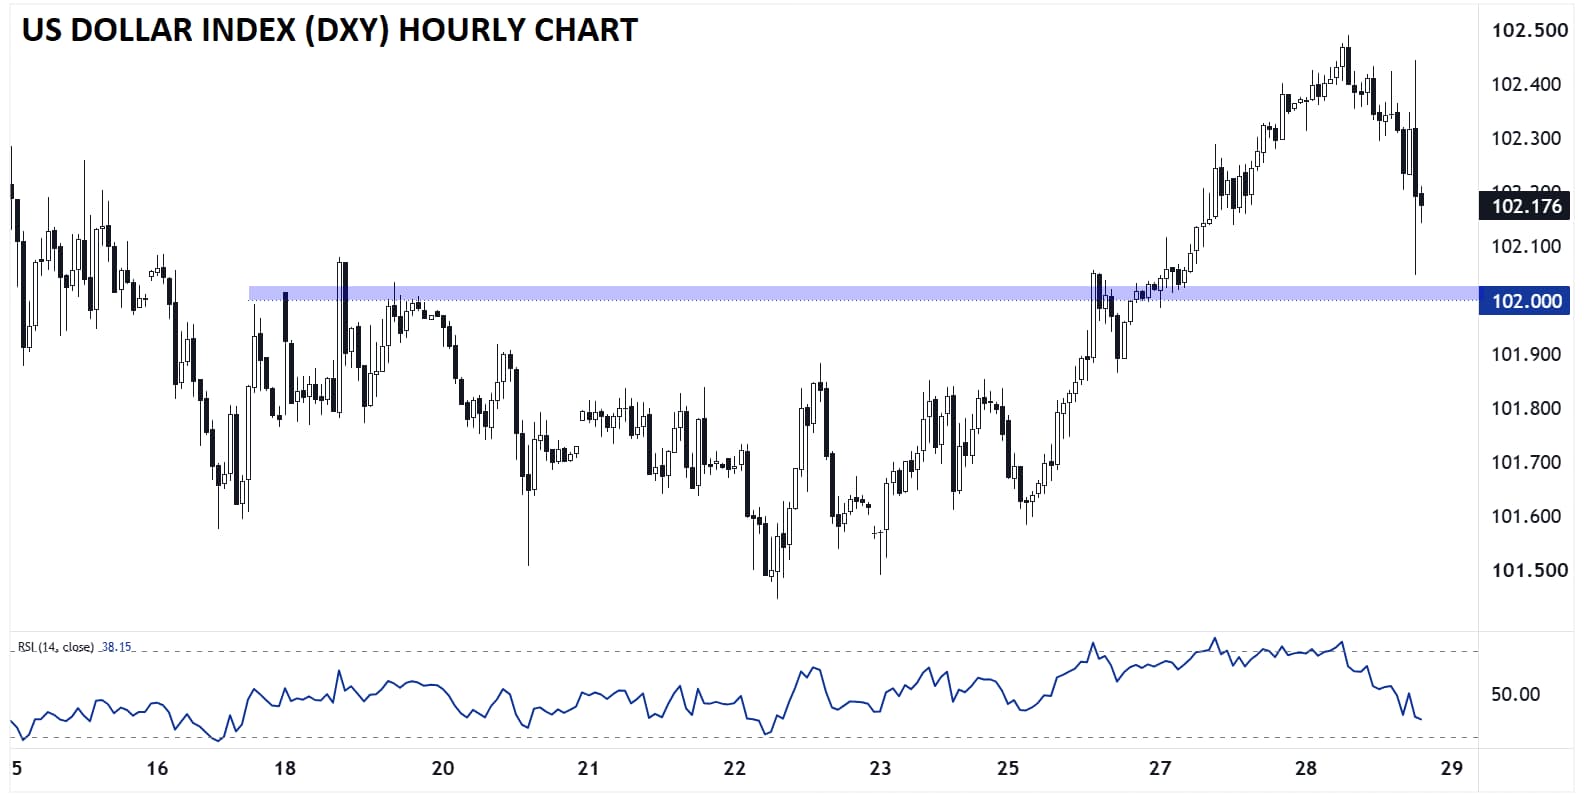
- The US Dollar Index (DXY) could bounce back from 102.00 support in the coming days, with only a break below that level shifting the near-term bias back to the downside.
FOMC Interest Rate Decision
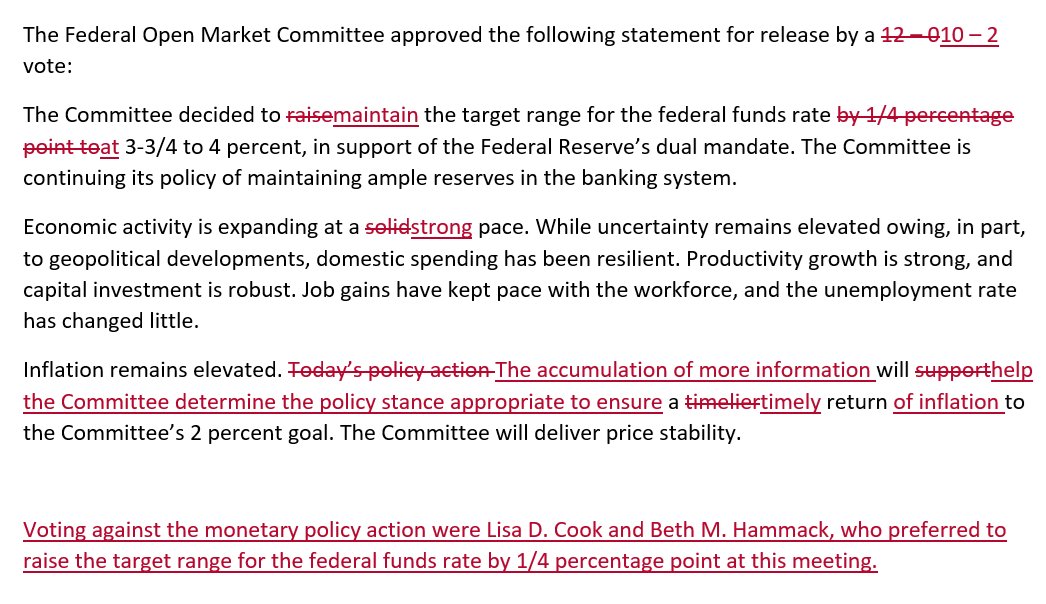
The Federal Reserve’s FOMC kept interest rates unchanged in the 3.75-4.00% range, as expected. The vote was 10-2, with Beth Hammack and Lisa Cook dissenting.
There were no other changes to monetary policy at today’s meeting.
FOMC Monetary Policy Statement
In its accompanying monetary policy statement, the FOMC made essentially one adjustment to its economic assessment, upgrading its appraisal of economic activity from “solid” to “strong.” While not particularly significant in and of itself, this tweak does suggest that inflation remains a bigger concern for the central bank, not economic growth or employment:
Source: Federal Reserve
FOMC Chairman Warsh’s Press Conference
In his press conference, FOMC Chairman Kevin Warsh broadly stuck to the script, implying that the FOMC may still raise interest rates again in December, while noting that the September hike “is starting to work some.” For traders who were expecting a clear hint that the central bank would raise interest rates again this year, Warsh fell short, resulting in a modestly less-hawkish-than-anticipated short-term interpretation of the event.
Highlights from his comments follow [emphasis mine]:
- INFLATION IS TOO HIGH
- OUR JOB TO ENSURE INFLATION EXPECTATIONS REMAIN ANCHORED
- MUST ENSURE RELATIVE PRICE CHANGES DON'T BROADEN OUT
- FED BELIEVES MORE INFORMATION WILL HELP DETERMINE STANCE
- COMMITTEE WILL DELIVER PRICE STABILITY
- 3Q GDP LIKELY ABOVE 3%
- FOMC SCHEDULE WILL CHANGE AS OF NEXT FALL
- IN SEPTEMBER WE REMOVED A DOSE OF ACCOMMODATION *WARSH: INFLATION COMPENSATION IS GOING THE RIGHT WAY
- FOMC SCHEDULE WILL CHANGE AS OF NEXT FALL
- 8 MEETINGS IS RIGHT NUMBER A YEAR
- ONE MEETING WILL NOT HAVE A VOTE ON POLICY RATE, WILL BE FOCUSED ON STRATEGY
- EXPECT IN 2028 TO HAVE 6 POLICY-SETTING MEETINGS
- OVERWHELMING CONSENSUS IS MEDICINE STARTING TO WORK SOME
- THERE'S NO FIRM CONCLUSIONS NOW ABOUT MONETARY POLICY
- I TAKE NOTE THAT OIL FUTURES PRICES HAVE MOVED UP
- ASKED IF MIDTERM ELECTIONS FACTORED INTO RATE DECISION, SAYS POLITICS PLAYED NO ROLE
The longer-term shift toward fewer policy meetings will ultimately raise the importance of economic data, rather than Fed speaker comments, and likely increase the volatility around future FOMC meetings.
In terms of the market’s reaction, moves are relatively limited. Traders are selling near-term bonds and buying longer-term bonds, hinting at the potential for a slightly less aggressive rate hike path but risk of a higher interest rates in the future. US indices are edging higher while the US dollar ticks lower.
US Dollar Technical Analysis – DXY Daily Chart
Source: StoneX, TradingView
Speaking of the world’s reserve currency, the US Dollar Index (DXY) is pulling back from its daily highs in the mid-102.00s, but remains above previous-resistance-turned-support at the 102.00 handle.
With the FOMC meeting behind us, traders will be turning their attention to earnings from key technology names (Microsoft, Google/Alphabet, and Amazon) and the midterm elections as the next drivers for the greenback. As long as we see solid earnings and a smooth election, the USD could bounce back from 102.00 support in the coming days, with only a break below that level shifting the near-term bias back to the downside.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX
Latest market news

Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
USD/JPY Weekly Outlook: AI earnings could overshadow the Fed and BoJ
AI sentiment has become a major driver of US Treasury yields and USD/JPY. With Microsoft, Alphabet and Amazon reporting this week, central bank decisions may have competition for traders' attention.

Nasdaq 100 Forecast: NDX slips ahead of Fed Chair Warsh’s speech
U.S. stocks are edging lower on Friday, giving back some of yesterday's gains after Nvidia's strong outlook revived the tech trade. The focus has now shifted firmly to Fed Chair Kevin Warsh's Jackson Hole speech, with investors looking for more clarity on the outlook for interest rates.

Bitcoin Forecast: BTC/USD Back to $80K Ahead of Warsh’s Jackson Hole Speech
After surging over $15,000 in the past 10 days alone, there is risk of a near-term pullback if Warsh says anything remotely hawkish at Jackson Hole - what are the levels to watch from here?