
Top 5 Charts for This Week: Yields, Oil and USD/JPY
It’s a big week ahead with a widely expected FOMC rate hike followed by a Bank of Japan rate decision. But perhaps more pressing are moves showing in US Treasuries and Oil and what that might entail for the macro landscape.
Written by
James Stanley
Sr. Strategist
Talking Points:
- FOMC and BoJ rate decisions highlight this week’s calendar with both banks expected to hike rates.
- Those moves are largely priced-in so perhaps more important is what they say about future conditions.
- And maybe even more important than that are moves that have already shown in US Treasuries and Oil, which could have massive connotations on inflation which is driving (and leading) the actions from both of those banks.
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of Forex.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
In this week’s Five Charts for the Week Ahead, the move in Treasury yields is the headline as the 10-year note is on the verge of a very important test. For the past 19 years there’s been but one single instance on the morning of October 23rd, 2023 in which the benchmark UST yielded 5%.
That ended up being a pretty epic buying opportunity as ZN rallied, and that was followed by US Treasury Secretary at the time, Janet Yellen, shifting upcoming Treasury issuance via the Quarterly Refunding Announcement, and that just further extended the move. The 10-year note futures contract rallied by 7.64% over the next couple of months, with 10-year yields dipping down to 3.8%.
10-Year Treasury Note Futures (ZN) Weekly Chart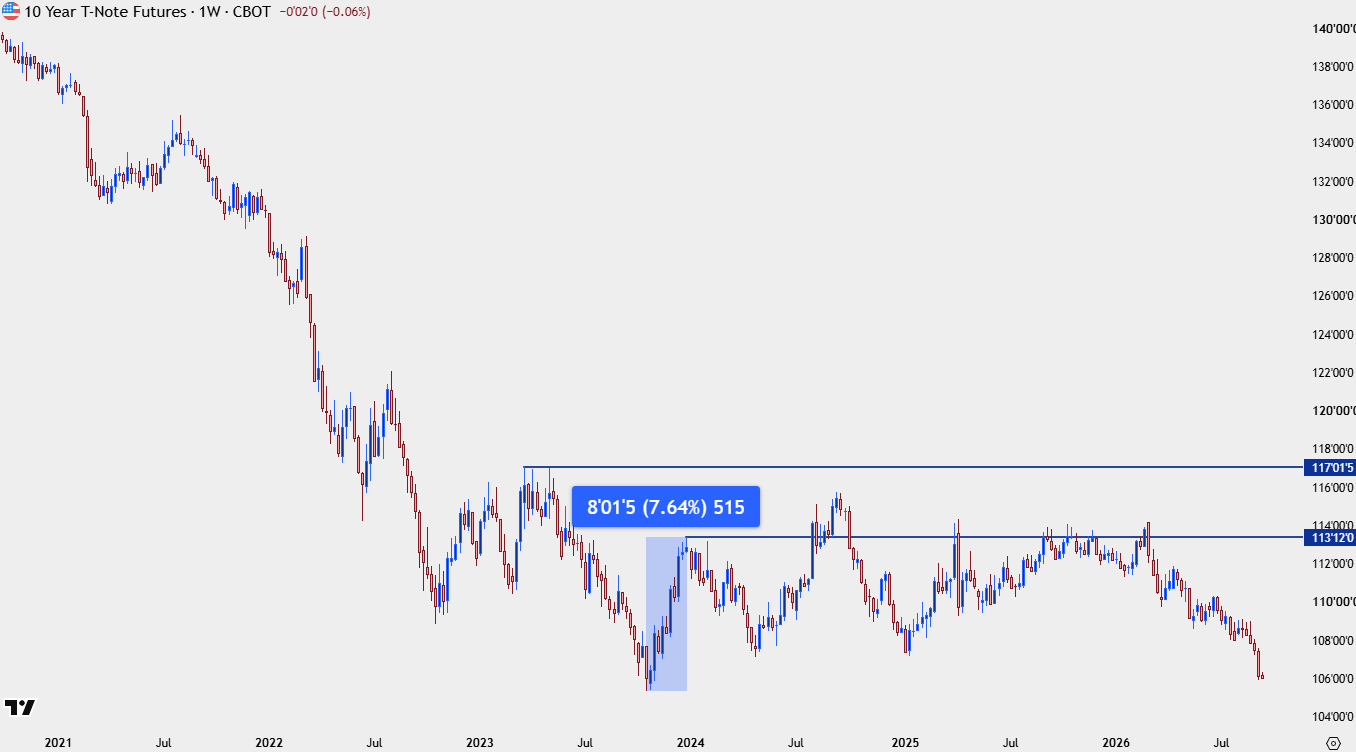
Chart prepared by James Stanley; data derived from Tradingview
Last week the 10-year came less than one basis point away from that 5% marker, and buyers already showed up. So logically that first test above 5% could lead to similar buying behavior.
But perhaps the bigger question is whether there’s enough power on the long side of the trade to lead to a similar reversal that showed back in 2023, because it was the shifting in the QRA that ultimately extended the move and with an upcoming maturity wall, current US Treasury Secretary Scott Bessent may not have as much flexibility as his predecessor.
The bigger level, in my opinion, is 5.25%, which traded twice back in 2006 and 2007 and this is where matters across markets shifted quickly, as the financial collapse drove capital flows into Treasuries and yields cratered soon after.
The attraction of locking in 10-year rates at 5.25% or 5% or even 4.5% in the midst of falling equity prices is undoubtably one of the factors that led to an exodus of capital from risk markets.
US 10-Year Note Yields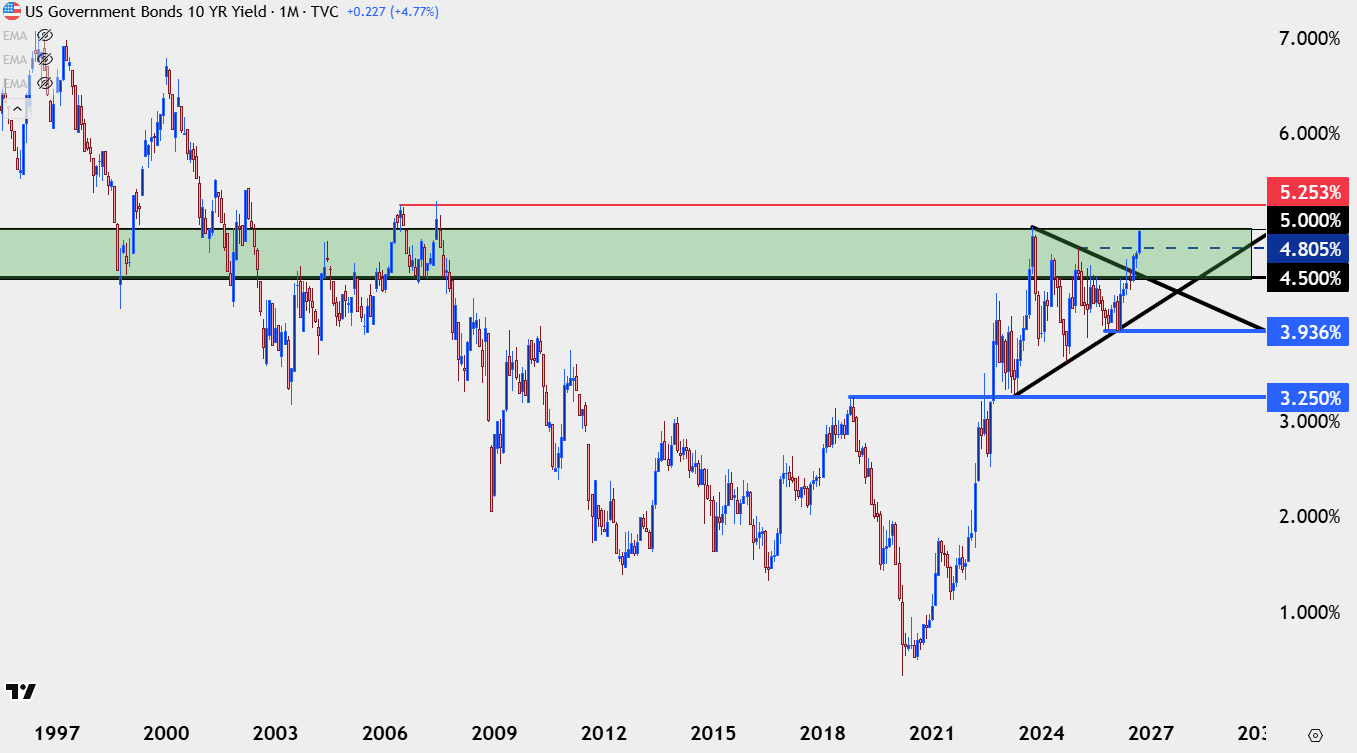
Chart prepared by James Stanley; data derived from Tradingview
Oil
Inflation data has been a major push point in the hawkish shift around the Fed in the past few months, and this has been even as oil prices have been relatively relaxed following the flare back in March. But oil strength is back again and WTI is testing above the $100 level.
This is the type of risk factor that’s difficult to ignore and it may even overshadow inflation to a degree because of the lag with which it takes for this to show in the data. With inflation already above target, and the Fed already expected to hike, higher oil prices aren’t doing any favors for the dovish crowd and this is something that can further press weakness in risk markets, especially if accompanied by a breakout in yields.
WTI Crude Oil Weekly Chart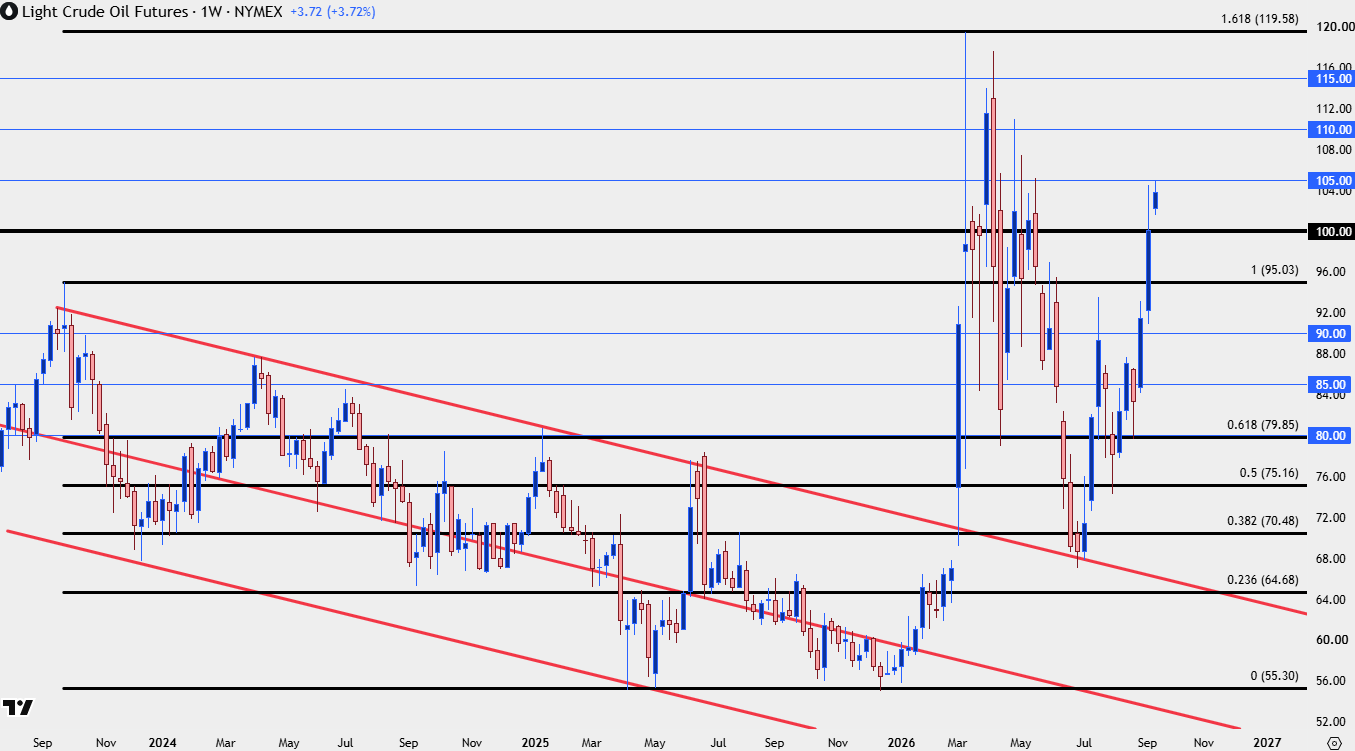
Chart prepared by James Stanley; data derived from Tradingview
USD/JPY
Both the Fed and BoJ are expected to hike rates this week but from a fundamental perspective there’s still logic for a bias towards the US side of the matter. Inflation data has generally been higher in the States with the exception of the recent PPI release and with both hikes largely priced-in, the bigger matter is what happens next.
In the US there’s already expectation for another hike by the end of the year, but with recent Japanese CPI at 1.9%, below their 2% target, is there really expectation for the BoJ to keep pace?
US Treasury Secretary Scott Bessent has certainly alluded to that case and this is a big reason why the pair isn’t back above the 160.00 level. He’s said he has asymmetric information, and he knows what the BoJ and Japanese policymakers will do, which thickens the drama for the Bank of Japan meeting later in the week.
In USD/JPY, the big question is whether we see sellers – whether that’s longs closing or shorts opening – in response to test of resistance at prior support.
USD/JPY Daily Price Chart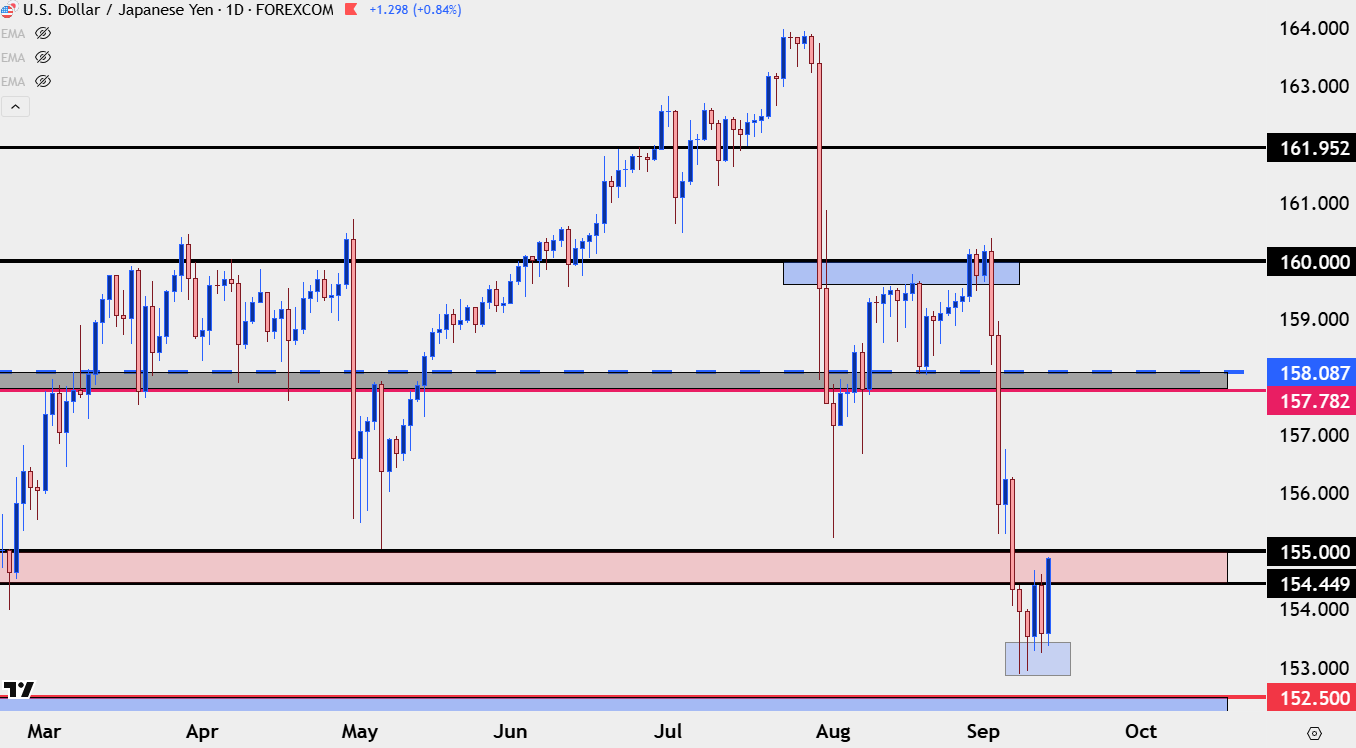
Chart prepared by James Stanley; data derived from Tradingview
SPX
It’s a Fed week and there’s massive interest around the yields move and the oil move and there was some drama around the AI trade over the weekend, so stocks have to make an appearance in this week’s edition.
I covered this in the weekend forecasts but at this point, SPX still retains a degree of strength given the hold of support at prior resistance. This looks a bit healthier than what’s shown in the tech-heavy Nasdaq and, collectively, that can be a worrisome sign that I’ll touch on below. But, for now, structure is bullish and if looking to buy the dip in stocks I think there’s a more cogent argument to be made here rather than in the Nasdaq.
SPX Daily Chart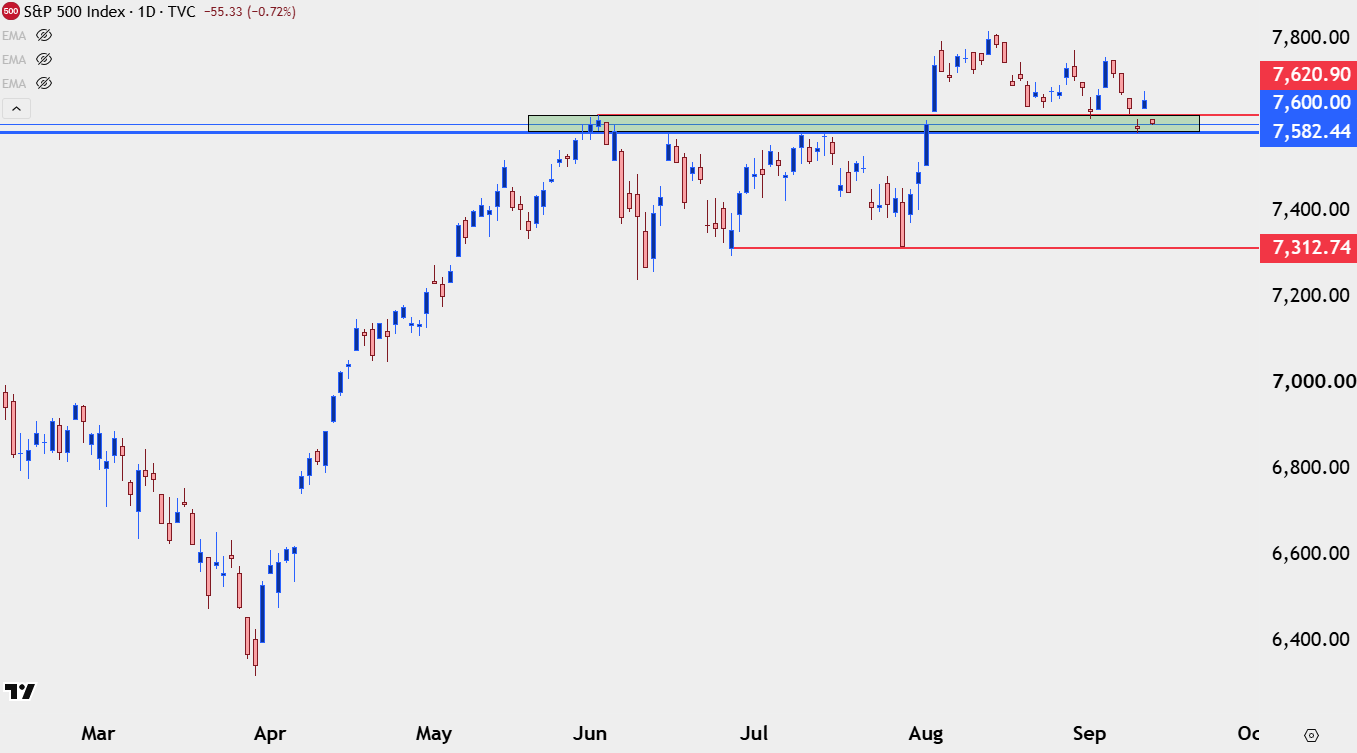
Chart prepared by James Stanley; data derived from Tradingview
Nasdaq 100
When the leader becomes the laggard, look out below. That was the case back in the year 2000 when tech stocks topped and started to sell-off a couple months ahead of the S&P 500. There was even a similar backdrop in yields at the time.
The logic of something like this is that late-stage equity buyers push in to markets with less aggressive valuations, and as chasing dips in high beta stocks becomes more and more painful. This type of dynamic has shown many other times, such as in July of 2024 when NQ started to sell-off almost instantly on the morning of July 11th, when a below-expected CPI print was coupled with a Japanese Yen intervention, and despite surging odds of rate cuts stocks began to tank. The S&P 500 took about a week to turn after the Nasdaq. And I had another prior instance of this back in February of 2020, just before the Covid pandemic came to light a month later although that instance is easier to dismiss given the shock of what happened.
At this point, I have the Nasdaq breaking a symmetrical triangle and testing a pretty major spot of support. If we do see fear taking over, whether that’s because of a super hawkish Fed or surging oil prices or Treasury yields breaking out- or perhaps a combination of those reasons – the Nasdaq makes for a more compelling case for shorts.
Nasdaq 100 Daily Chart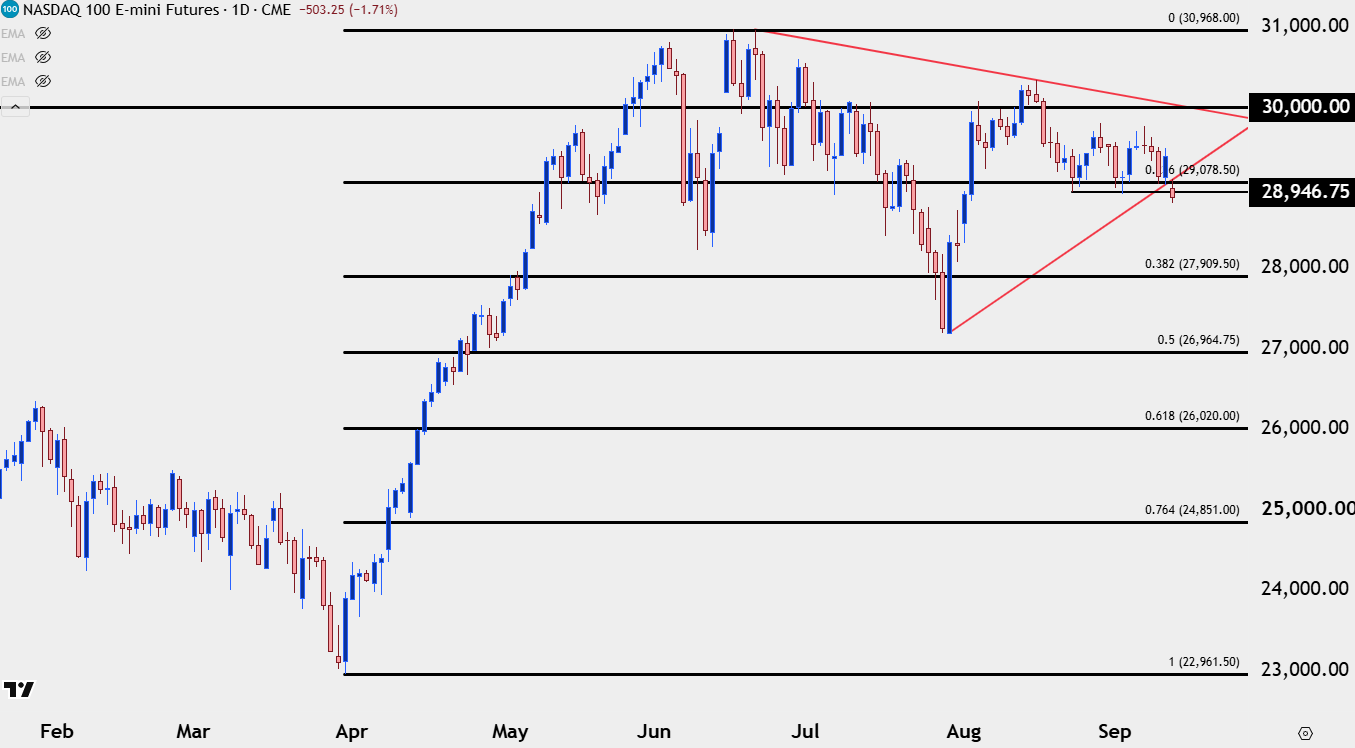
Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Market Analyst, Global Macro
Related tags:
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
FX Futures Positioning: Dollar Rebound Meets Diverging Forex Bets | COT Report
US dollar longs held firm into Jackson Hole, while euro, yen and commodity FX positioning diverged ahead of ISM and NFP.

Gold and S&P 500 analysis: What now after Warsh’s hawkish speech?
The dollar surged across the board after the Fed Chair Kevin Warsh surprised with a hawkish-leaning speech at the Jackson Hole summit. All the bearish dollar bets that had been accumulated since last Friday on the back of data weakness and bond market troubles had to be squared and that triggered a short squeeze rally for the dollar. Gold and silver dropped, as a result, as too did bitcoin, while US indices were giving back earlier gains.
Nasdaq 100 Forecast: NDX slips ahead of Fed Chair Warsh’s speech
U.S. stocks are edging lower on Friday, giving back some of yesterday's gains after Nvidia's strong outlook revived the tech trade. The focus has now shifted firmly to Fed Chair Kevin Warsh's Jackson Hole speech, with investors looking for more clarity on the outlook for interest rates.
