
Indices weekly outlook: Can the DAX rebound turn into a reversal?
Global indices managed to bounce back towards the end of the week as risk mood improved following Thursday’s drop in bond yields and a slight decline in oil prices. But by late Friday afternoon, oil prices had made back most of Thursday’s drop and the bond markets remained under some pressure as European bourses closed for trading.
Written by
Fawad Razaqzada
Market Analyst
Global indices managed to bounce back towards the end of the week as risk mood improved following Thursday’s drop in bond yields and a slight decline in oil prices. But by late Friday afternoon, oil prices had made back most of Thursday’s drop and the bond markets remained under some pressure as European bourses closed for trading. Earlier in the day on Friday, the German DAX index had bounced sharply after the turbulence of recent sessions. That rebound had improved the technical backdrop a bit ahead of the new trading week, but it is too early to conclude that the recent pressure has disappeared entirely. Much of the improvement still reflects a reduction in immediate risks rather than a fundamental change in the underlying backdrop. We maintain a cautious DAX outlook heading into the new week.
French fiscal risk premium and oil remain key risk factors
Some of the existing risks associated with European markets were still evident in the FX markets. The euro, for one, failed to stage a recovery on Friday against most major currencies, including the US dollar and Swiss franc, suggesting FX markets were still reluctant to scale back the French fiscal risk premium. That could become an increasingly important headwind for European equities next week if the situation deteriorates further.
Marine Le Pen’s pledge for significant fiscal tightening is unlikely, in our view, to be enough to turn the tide for French government bonds. Unless there are clearer signs of improvement in France’s fiscal position, European markets could remain vulnerable to renewed pressure from the French debt situation.
Energy prices are another risk factor for Europe. US President Donald Trump has said the US will not attack Iran before the 3 November midterms, but the oil market has been reluctant to fully unwind the geopolitical risk premium, with crude still trading above $100 a barrel despite an apparent improvement in Gulf supply.
That is hardly a favourable backdrop for the eurozone, where all of the major economies remain heavily reliant on energy imports. If oil prices stay elevated or move higher again, the resulting inflationary pressure could further complicate the outlook for both European growth and monetary policy.
Iranian Foreign Minister Araghchi said Tehran was reviewing Washington’s response and expected to reply within the next few days, so this remains an important risk for markets. Anything positive should boost stocks.
Week ahead: US inflation takes centre stage
The big event for markets next week will be US inflation.
September CPI is due on Wednesday, followed by PPI, retail sales, jobless claims and several regional manufacturing indicators on Thursday. CPI has been easing in recent months, standing at 2.4% year-on-year in August, and investors will be watching closely for any sign that the disinflationary trend is losing momentum.
A softer-than-expected inflation reading would probably reinforce the recent decline in yields and support risk assets, potentially giving the DAX another leg higher.
A hotter number, on the other hand, could quickly revive concerns about interest rates and put renewed pressure on bonds and equities.
The data will also be important for the dollar. Following the recent softer patch in US economic data, the greenback has lost some momentum, and another benign inflation report could reinforce that trend.
Central bank speakers will also be in focus. BoE Governor Bailey, ECB President Lagarde and BoC Governor Macklem are due to speak on Wednesday at the IMF and World Bank meetings in Bangkok, followed by SNB Chairman Schlegel on Thursday and Fed Governor Warsh on Friday.
Technical DAX outlook: potential double bottom?
The technical picture has improved, but the index still has something to prove.
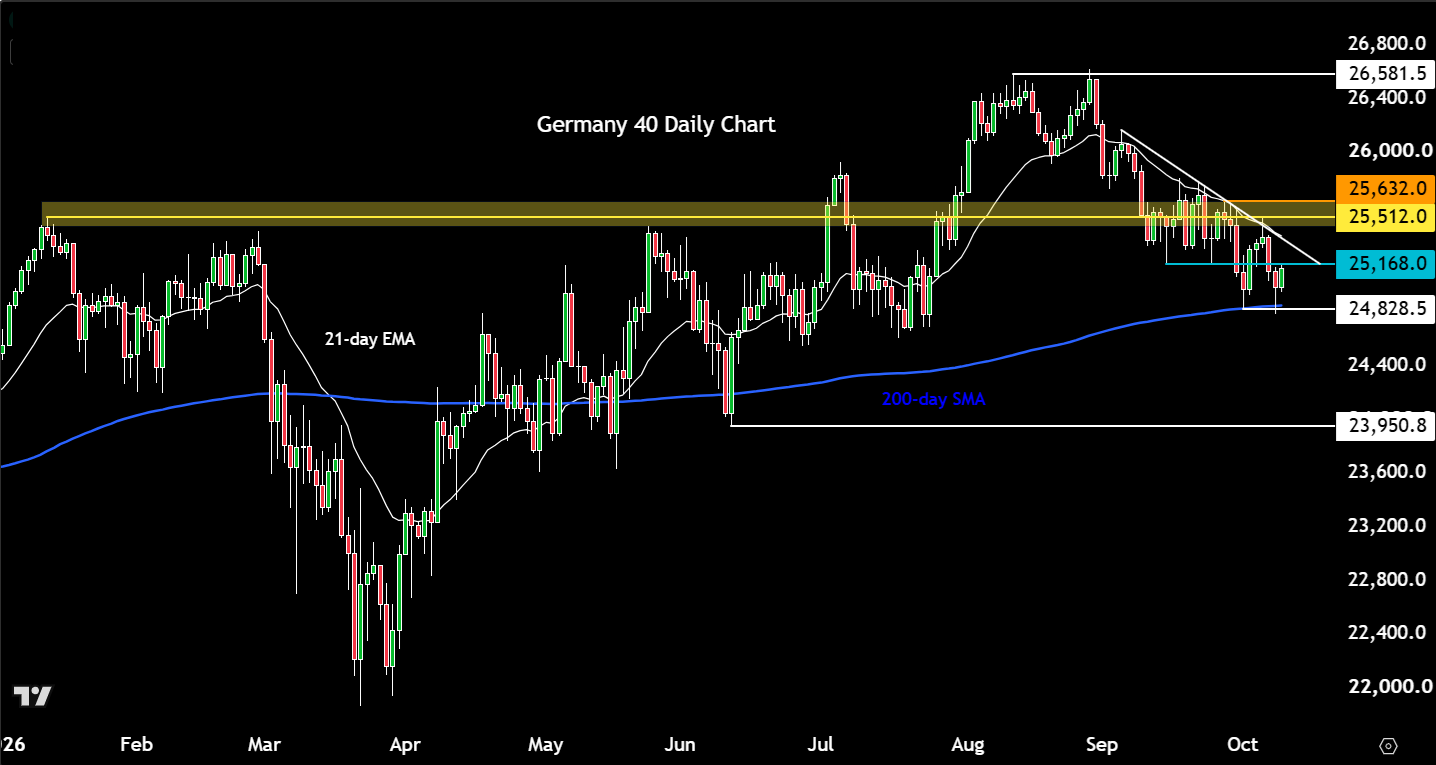
The DAX has formed what could become a double-bottom reversal pattern around its 200-day moving average, near the 24,800 area. This is an important technical zone, so the fact that buyers have managed to defend it is encouraging.
That said, the reversal is not confirmed yet.
The index still needs to break above the bearish trend line that has been defining the recent correction. A sustained move above that resistance would provide a much stronger signal that the sellers are losing control and potentially open the door to a broader recovery.
Conversely, failure to clear the trend line would leave the DAX vulnerable to another test of the 24,800 area. A decisive break below the 200-day average would invalidate the double-bottom setup and put the bears back in charge.
So, for now, the message from the chart is cautiously constructive rather than outright bullish.
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
Gold and S&P 500 analysis: What now after Warsh’s hawkish speech?
The dollar surged across the board after the Fed Chair Kevin Warsh surprised with a hawkish-leaning speech at the Jackson Hole summit. All the bearish dollar bets that had been accumulated since last Friday on the back of data weakness and bond market troubles had to be squared and that triggered a short squeeze rally for the dollar. Gold and silver dropped, as a result, as too did bitcoin, while US indices were giving back earlier gains.
EUR/USD forecast: All eyes on Warsh at Jackson Hole - Forex Friday
For much of this week, the EUR/USD has been edging lower with the US dollar regaining some ground after last week’s sell-off that was triggered, in part, by the bond market worries. Investors have been unwilling to bet further against the US dollar so far this week ahead of Kevin Warsh’s keynote speech at the Jackson Hole summit, due later today.
Nasdaq 100 forecast: Tech stocks shine as Nvidia results underpin AI trade
Much of this week’s attention has been on Nvidia’s earnings, and the chipmaker delivered the sort of numbers of investors had been hoping for. US index futures initially wobbled before moving higher overnight, with the results providing a fresh lift to the AI trade